Iran Update, Job Growth, Consumer Spending, Inflation Data, & Next Week’s Fed Meeting
Weekly Market Recap
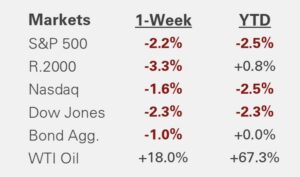 It wasn’t pretty – markets finished lower as an early-week rally faded into a late-week selloff. Stocks initially rallied as the White House said the “war is very complete, pretty much” and oil prices plunged, but the strength reversed as geopolitical tensions escalated and oil rebounded. The S&P 500 fell -2%, with Energy the only sector in positive territory. The Nasdaq outperformed with a -1.5% return as investors rotated toward tech stocks and mega caps amid the volatility, while the Russell 2000 returned -3%. *I apologize for the delay in sending this, as I was out of town.
Bonds traded lower as rising oil prices and inflation concerns pushed Treasury yields higher. Commodities were mixed: oil rebounded toward $100 per barrel as the Strait of Hormuz remained closed, while gold posted a modest loss despite the market volatility. The VIX Index fell below 30 as oil stabilized but remains elevated with tensions unresolved.
Key Takeaways
Tensions Remain Elevated in the Middle East & Continue to Impact Markets
The Strait of Hormuz remains effectively closed, and the energy shock remains the dominant market story. Oil has surged ~40% since the strike, the VIX spiked to an 11-month high before partially recovering, and Fed rate-cut expectations for 2026 have dropped from three to one. Equity markets have held up better than might be expected, with the S&P 500 down less than -3% since February 28. The key question is how quickly oil flows normalize, which will determine whether the supply disruption is contained or becomes a drag on economic growth. Why it matters: Markets are likely to remain volatile until geopolitical tensions ease.
Labor Market Conditions Continue to Soften
The U.S. economy lost -92,000 jobs in February, below expectations for +50,000–60,000. Prior months were also revised lower, with December flipping from +48,000 to -17,000, meaning the labor market has shed jobs in three of the past five months. Unemployment edged up to 4.4% from 4.3%. Part of the weakness was due to a Kaiser Permanente strike that kept ~31,000 healthcare workers off payrolls during the survey period, though it has since been resolved. Why it matters: Labor market conditions increase pressure on the Fed to resume cutting rates, though the timing remains uncertain heading into the March 17–18 meeting. While some of the weakness reflects temporary distortions, the broader trend points to a softening labor market.
Consumer Spending Remains Solid Despite Headline Decline
The January retail sales report showed a modest decline of -0.2% m/m, below expectations for a flat reading. Weakness in motor vehicles and gasoline stations pulled the headline lower, though reduced gas spending mostly reflected lower January fuel prices rather than weaker demand. Stripping out those categories, sales rose +0.3%, and the control group, which feeds directly into GDP calculations, also gained +0.3%, suggesting underlying consumer spending was more resilient than the headline implied. Why it matters: The underlying consumer picture in January was stronger than the headline suggested. However, the recent oil shock introduces a new variable that could weigh on consumer spending in the months ahead.
Inflation Was Easing, But the Oil Price Shock Could Create New Pressures
Headline CPI rose +0.3% m/m and +2.4% y/y, in line with January. Core inflation, which excludes the volatile food and energy categories, rose +0.2% m/m and +2.5% y/y. Shelter costs, which have been the most stubborn component of inflation, continued to ease, with rent posting its smallest monthly gain since January 2021. The data suggests inflation continued to ease early in 2026. Why it matters: February’s data is encouraging, but it was collected before the oil shock. Looking ahead, the question is whether the rise in oil prices will impact inflation and complicate Fed policy.
The Fed’s Meeting is the Big Event Next Week
Investors expect the Fed to hold rates steady at 3.50–3.75%. The focus will shift to the updated dot plot, which will signal how many cuts policymakers expect in 2026 and whether higher oil prices are influencing their inflation outlook. The Fed faces a difficult balancing act: inflation is stabilizing and the labor market is softening, but rising oil prices introduce a new inflation risk. The market expects one 0.25% rate cut this year, though two cuts are possible if energy stabilizes. Why it matters: Until the oil shock’s impact on inflation becomes clearer, the Fed is unlikely to provide the policy clarity markets want.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Weekly Market Recap | March 14, 2026
Iran Update, Job Growth, Consumer Spending, Inflation Data, & Next Week’s Fed Meeting
Weekly Market Recap
Bonds traded lower as rising oil prices and inflation concerns pushed Treasury yields higher. Commodities were mixed: oil rebounded toward $100 per barrel as the Strait of Hormuz remained closed, while gold posted a modest loss despite the market volatility. The VIX Index fell below 30 as oil stabilized but remains elevated with tensions unresolved.
Key Takeaways
Tensions Remain Elevated in the Middle East & Continue to Impact Markets
The Strait of Hormuz remains effectively closed, and the energy shock remains the dominant market story. Oil has surged ~40% since the strike, the VIX spiked to an 11-month high before partially recovering, and Fed rate-cut expectations for 2026 have dropped from three to one. Equity markets have held up better than might be expected, with the S&P 500 down less than -3% since February 28. The key question is how quickly oil flows normalize, which will determine whether the supply disruption is contained or becomes a drag on economic growth. Why it matters: Markets are likely to remain volatile until geopolitical tensions ease.
Labor Market Conditions Continue to Soften
The U.S. economy lost -92,000 jobs in February, below expectations for +50,000–60,000. Prior months were also revised lower, with December flipping from +48,000 to -17,000, meaning the labor market has shed jobs in three of the past five months. Unemployment edged up to 4.4% from 4.3%. Part of the weakness was due to a Kaiser Permanente strike that kept ~31,000 healthcare workers off payrolls during the survey period, though it has since been resolved. Why it matters: Labor market conditions increase pressure on the Fed to resume cutting rates, though the timing remains uncertain heading into the March 17–18 meeting. While some of the weakness reflects temporary distortions, the broader trend points to a softening labor market.
Consumer Spending Remains Solid Despite Headline Decline
The January retail sales report showed a modest decline of -0.2% m/m, below expectations for a flat reading. Weakness in motor vehicles and gasoline stations pulled the headline lower, though reduced gas spending mostly reflected lower January fuel prices rather than weaker demand. Stripping out those categories, sales rose +0.3%, and the control group, which feeds directly into GDP calculations, also gained +0.3%, suggesting underlying consumer spending was more resilient than the headline implied. Why it matters: The underlying consumer picture in January was stronger than the headline suggested. However, the recent oil shock introduces a new variable that could weigh on consumer spending in the months ahead.
Inflation Was Easing, But the Oil Price Shock Could Create New Pressures
Headline CPI rose +0.3% m/m and +2.4% y/y, in line with January. Core inflation, which excludes the volatile food and energy categories, rose +0.2% m/m and +2.5% y/y. Shelter costs, which have been the most stubborn component of inflation, continued to ease, with rent posting its smallest monthly gain since January 2021. The data suggests inflation continued to ease early in 2026. Why it matters: February’s data is encouraging, but it was collected before the oil shock. Looking ahead, the question is whether the rise in oil prices will impact inflation and complicate Fed policy.
The Fed’s Meeting is the Big Event Next Week
Investors expect the Fed to hold rates steady at 3.50–3.75%. The focus will shift to the updated dot plot, which will signal how many cuts policymakers expect in 2026 and whether higher oil prices are influencing their inflation outlook. The Fed faces a difficult balancing act: inflation is stabilizing and the labor market is softening, but rising oil prices introduce a new inflation risk. The market expects one 0.25% rate cut this year, though two cuts are possible if energy stabilizes. Why it matters: Until the oil shock’s impact on inflation becomes clearer, the Fed is unlikely to provide the policy clarity markets want.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Asset Location vs. Asset Allocation in Financial Planning
Putting This Week’s Market Volatility in Perspective
The Midterms Changed Congress, Not the Fundamentals
Subscribe to Our Blog
Chief Investment Officer | Managing Partner