Gold, silver, and other precious metals have rallied over the past two years, capturing investor attention. Gold recently surpassed $5,000 per ounce while silver now trades above $100 per ounce, marking historic milestones for both metals.
This strong recent performance may lead some investors to wonder whether they should be investing in these assets. As with all investments, it’s important to maintain a broader perspective to understand their history and how they fit into a well-constructed portfolio.
While many investors often turn to precious metals as “safe haven” investments, these and other commodities are prone to boom and bust cycles. In today’s environment, the rallies in gold and silver are occurring alongside many other asset classes due to heightened uncertainty around monetary policy, fiscal policy, and geopolitical risk. It’s important to view these assets not as speculative trading instruments, but as components of a broader investment strategy aligned with financial goals.
Precious metals often respond to uncertainty
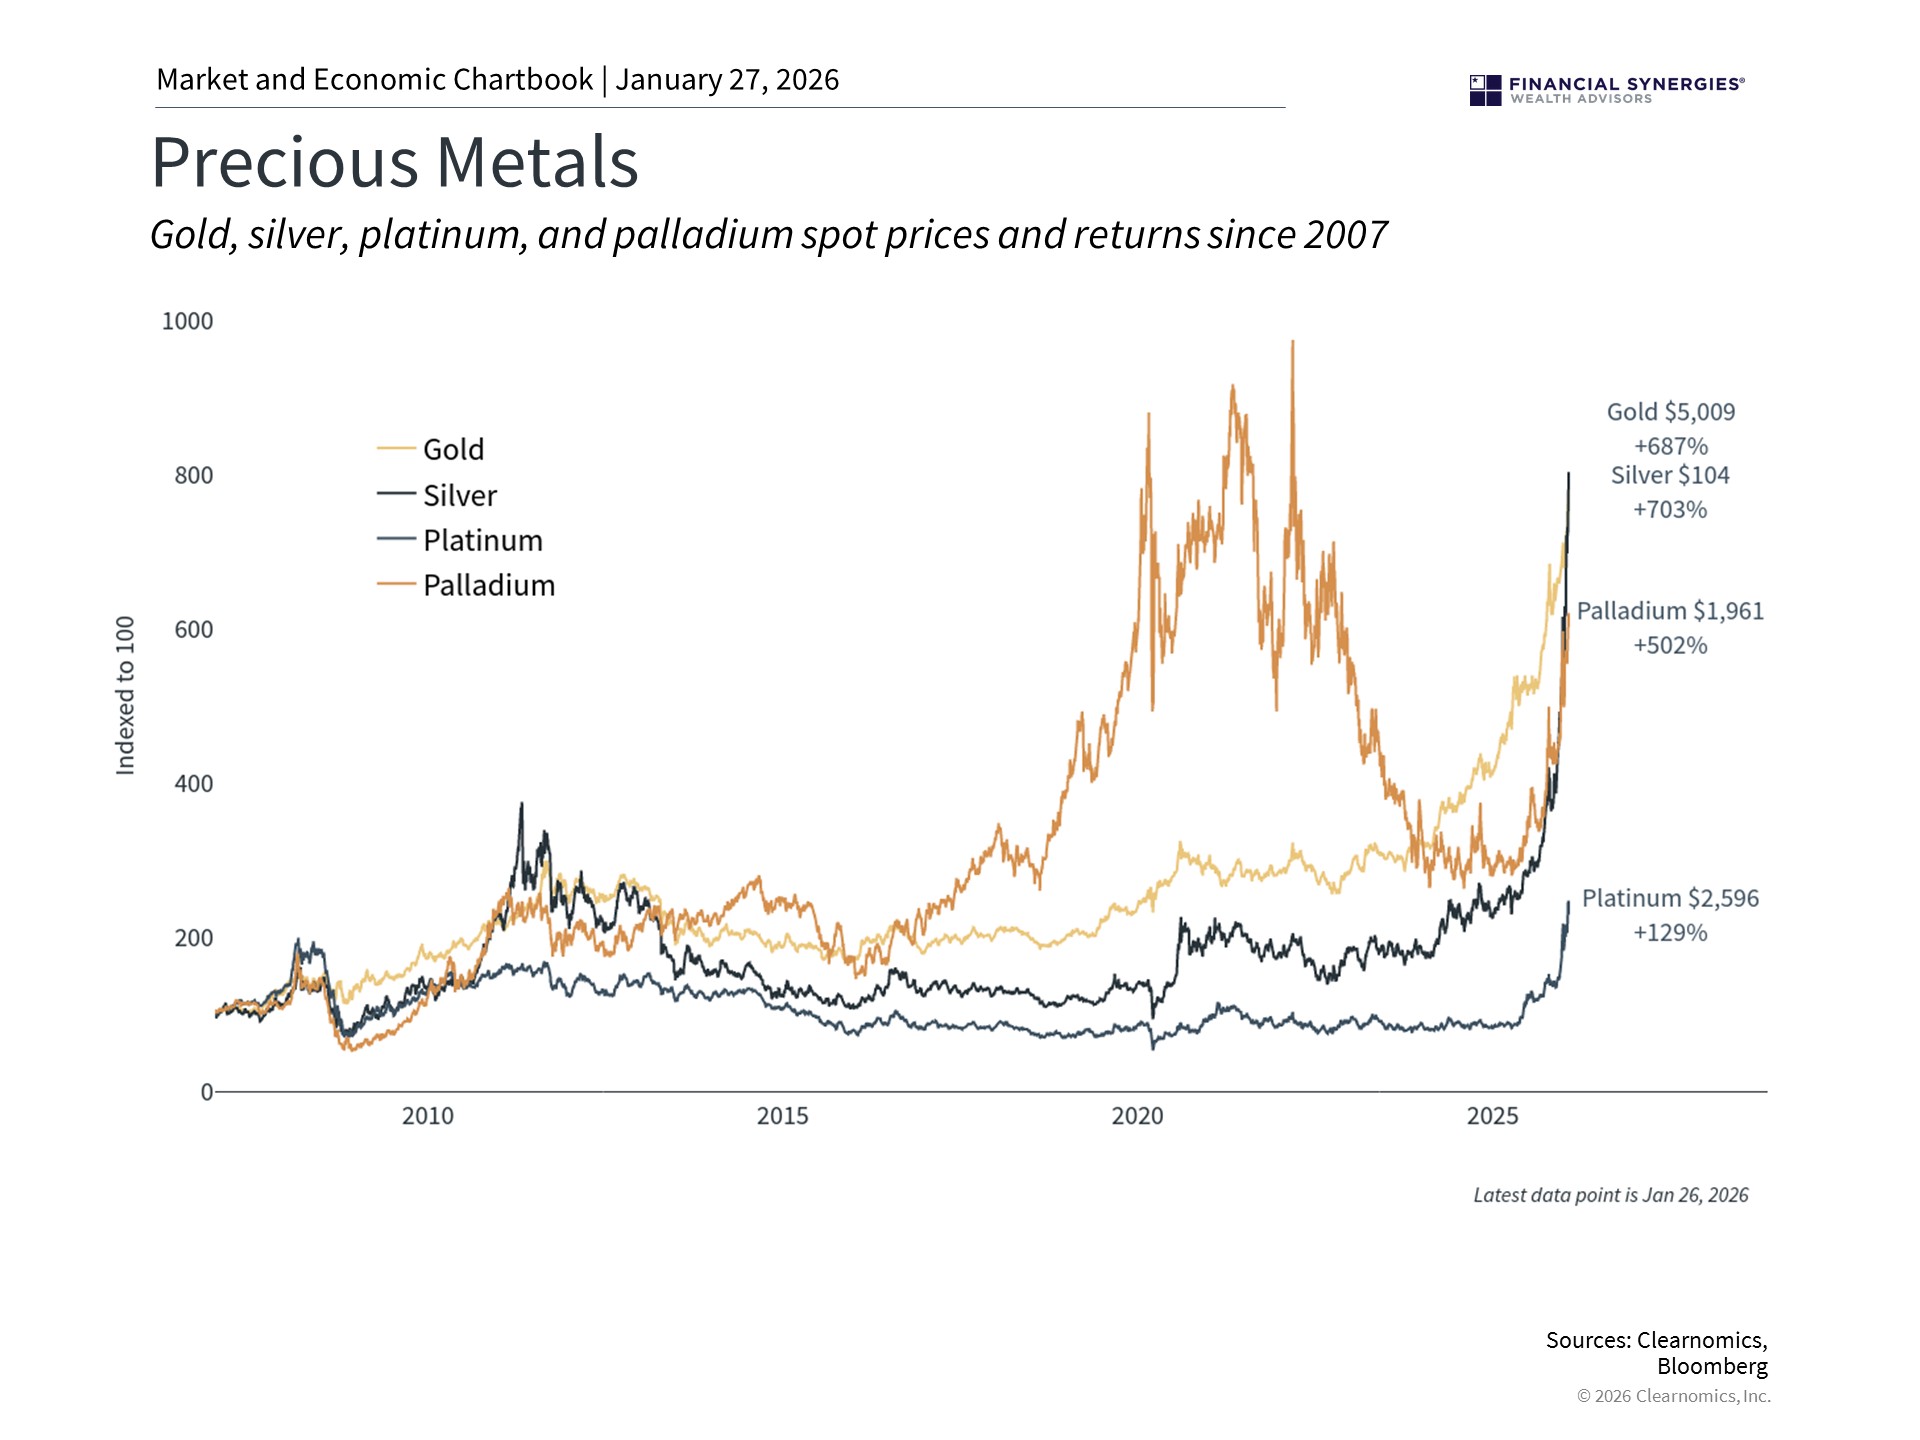
Several factors have driven the surge in gold and silver prices. One of the most important has been the recent tension between the White House and the Fed. This has raised questions about central bank independence and the direction of monetary policy, especially as Jerome Powell’s term as Fed chair ends in May 2026. Lower rates and the prospect of inflation put downward pressure on the dollar, so it’s natural for some investors to seek assets that can serve as a “store of value.”
Equally important is that central banks around the world have been consistent buyers of gold in recent years as they have diversified away from dollar-denominated reserves. Central banks need to hold enough reserves to manage their monetary policy and maintain the value of their currencies. These purchases of gold and other assets have accelerated amid heightened geopolitical uncertainty and concerns about currency stability.
Both metals have also benefited from their industrial applications, including in electric vehicles, solar panels, and artificial intelligence hardware. Thus, they serve roles as precious metals, safe haven assets, as well as industrial commodities.
Precious metal rallies are difficult to predict
Throughout history, periods of monetary policy uncertainty have coincided with strong precious metals performance. In the 1970s, for instance, both gold and silver climbed dramatically as stagflation hit the economy, peaking around 1980. Similarly, both rose from 2008 to 2011 during the global financial crisis, and then again during the 2020 pandemic.
In each of these cases, investors turned to precious metals when uncertainty about monetary policy and economic conditions peaked. However, both gold and silver prices began to reverse soon thereafter once conditions began to improve.
This creates at least two challenges for investors who are attracted to these investments based on recent performance. First, attempting to forecast gold and silver prices amounts to predicting the path of interest rates, inflation, and other factors like terms of trade. As the past several years have shown, these factors are difficult to forecast with certainty. Many concerns among investors and professional economists as inflation spiked in 2021 and 2022 did not materialize as expected.
Second, while it’s understandable that investors are drawn to assets that have performed well, history shows that precious metal rallies are notoriously difficult to time. The 1970s gold rally, for instance, was followed by two decades of declining prices. Gold peaked above $800 in 1980, a level it wouldn’t reach again until 2007.
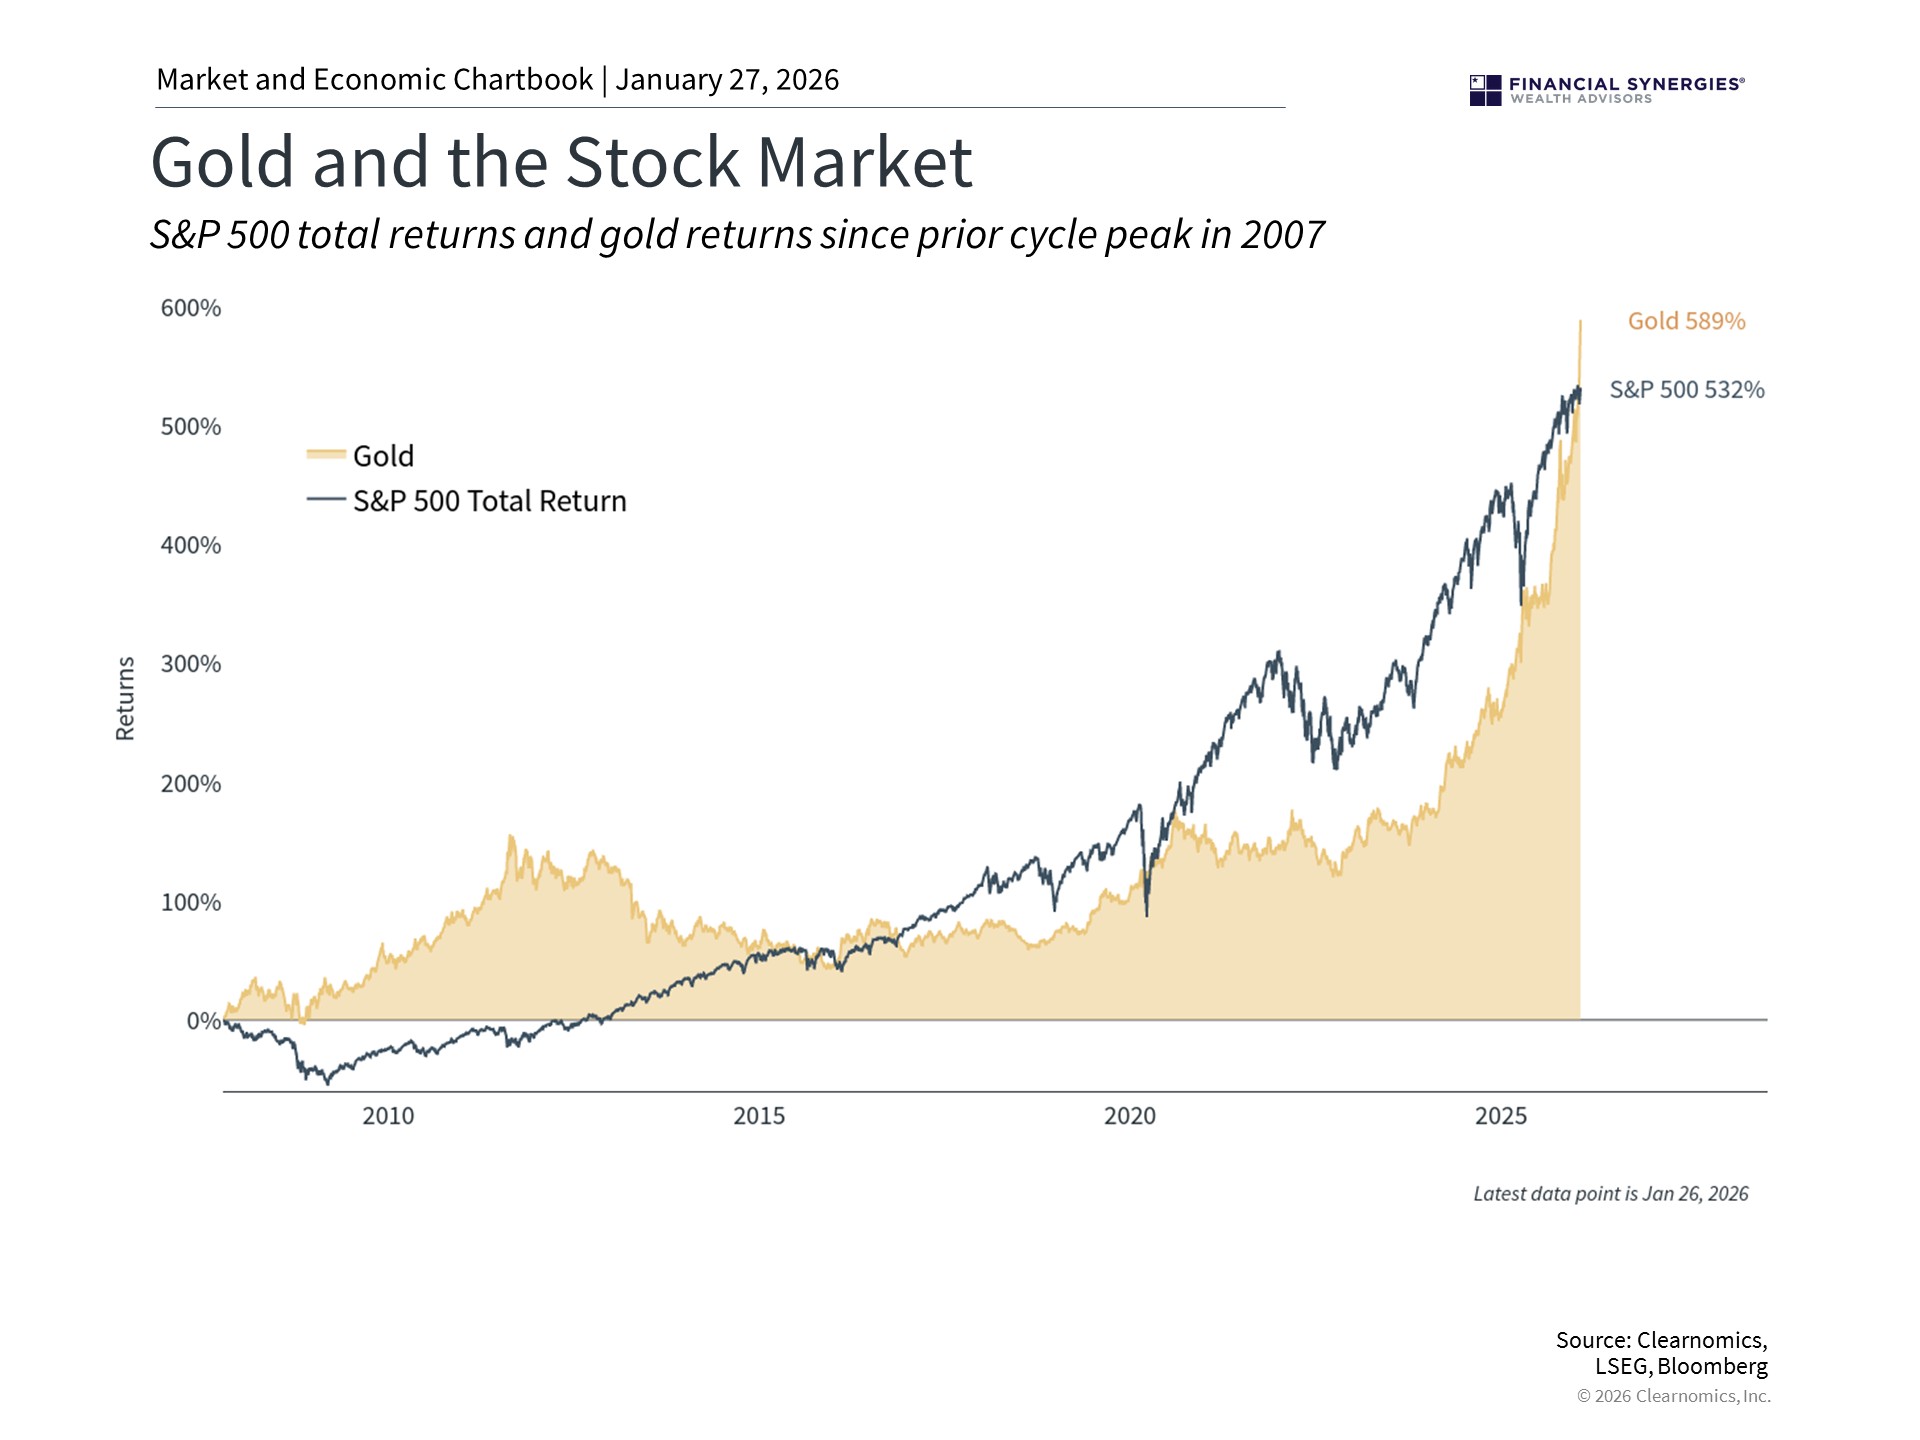
The accompanying chart shows gold’s performance compared to the S&P 500 since the 2007 market peak. While gold has had periods of strong performance, the stock market has also performed well over these periods. For investors focused on recent precious metals rallies, this longer-term perspective may seem surprising. However, it makes sense since the stock market has historically risen over long periods of time.
This pattern extends to silver as well. Despite its strong industrial demand story, silver has experienced long periods of underperformance between rallies. For instance, silver experienced a strong rally in the late 1970s. As stagflation pushed silver higher, a famous episode occurred in which the Hunt brothers attempted to corner the market by accumulating stockpiles and buying futures contracts. While they drove prices higher for a time, prices eventually plummeted as new supply entered the market and when regulators introduced restrictions on leveraged buying of commodities.
Other precious metals exhibit similar behavior. Between 2016 and early 2022, palladium gained over 500%. This rally was driven by restricted global supply and greater use in applications such as catalytic converters for cars. However, after peaking, prices declined sharply over a two-year period.
Precious metals should be aligned with financial goals
These episodes demonstrate that, in situations where it makes sense for investors to have exposure to precious metals and commodities, gold and silver are best viewed as components of a broader commodities allocation or as part of alternative investments. The Bloomberg Commodity Index, for instance, currently allocates 14.9% to gold and 3.9% to silver, alongside other commodities such as industrial metals, energy, and agricultural products. This diversified approach to commodities exposure helps manage the volatility inherent in any single commodity.
The case for including precious metals in portfolios is based on the fact that they behave differently from stocks and bonds. Their value derives from scarcity, their roles as stores of value, and industrial uses. This means they often react to market and economic events differently from traditional asset classes, which can help to stabilize portfolios.
However, precious metals also carry important limitations. Most notably, they generate no income, unlike bonds or dividend-paying stocks. This lack of income also makes these assets difficult to value, which is another reason they are prone to booms and busts. A portfolio inappropriately weighted toward gold and silver may sacrifice the long-term growth potential of equities and the income generation of fixed income. So, even if precious metals might help in specific market environments, they may not be aligned with long-term goals.
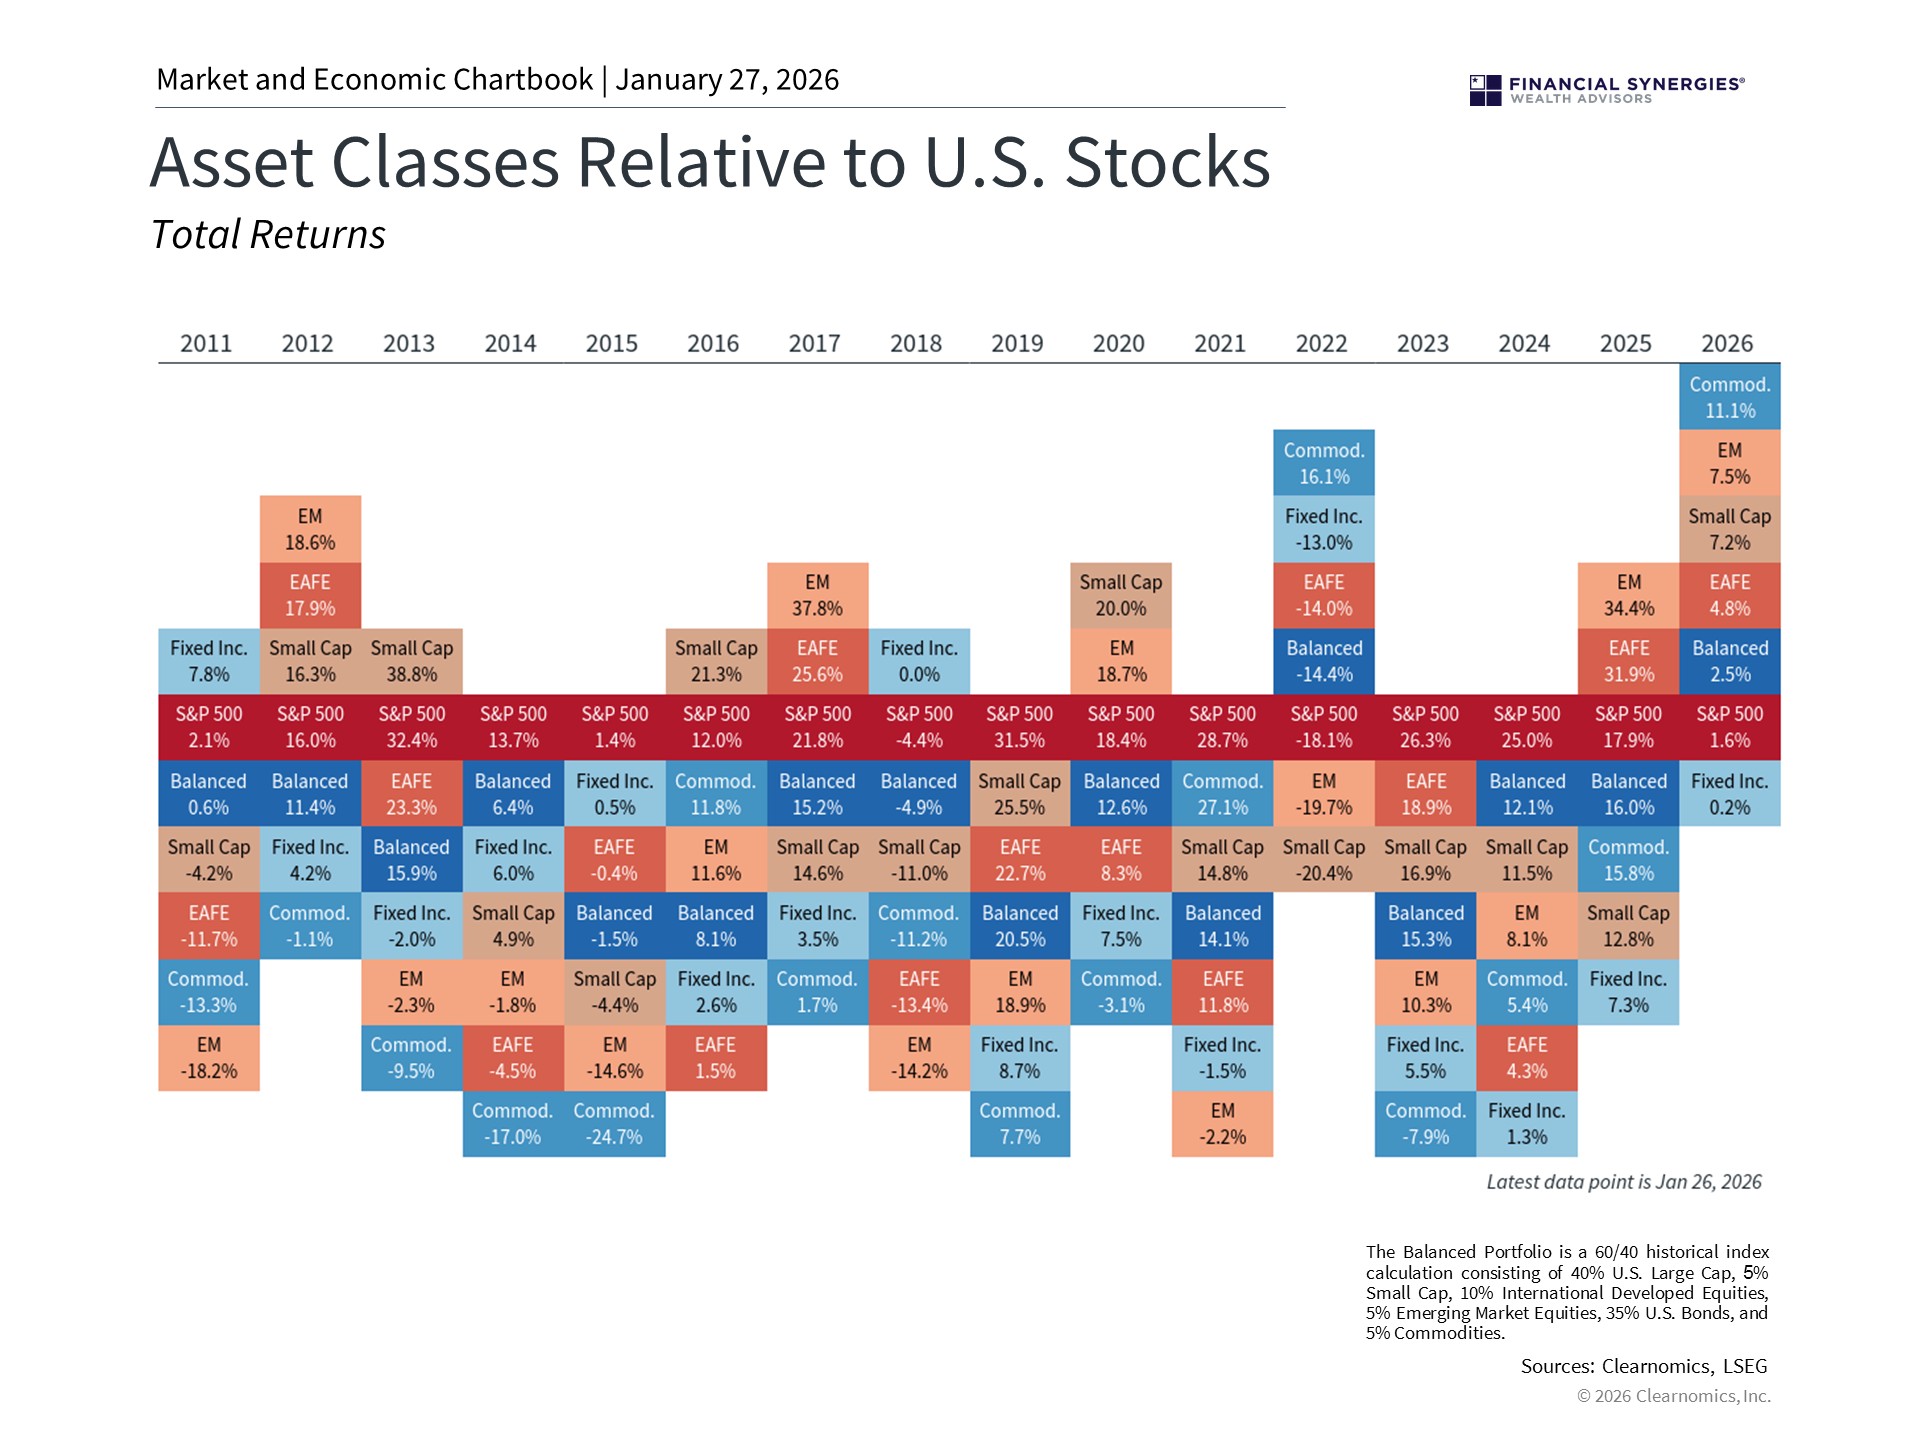
The accompanying chart shows that many asset classes have contributed to portfolio returns recently, not just precious metals. While gold and silver have certainly performed well, there will always be individual investments that shine in particular periods. The key is constructing portfolios that can benefit from various market conditions rather than concentrating on recent winners.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Gold and Silver: Current Perspectives
Gold, silver, and other precious metals have rallied over the past two years, capturing investor attention. Gold recently surpassed $5,000 per ounce while silver now trades above $100 per ounce, marking historic milestones for both metals.
This strong recent performance may lead some investors to wonder whether they should be investing in these assets. As with all investments, it’s important to maintain a broader perspective to understand their history and how they fit into a well-constructed portfolio.
While many investors often turn to precious metals as “safe haven” investments, these and other commodities are prone to boom and bust cycles. In today’s environment, the rallies in gold and silver are occurring alongside many other asset classes due to heightened uncertainty around monetary policy, fiscal policy, and geopolitical risk. It’s important to view these assets not as speculative trading instruments, but as components of a broader investment strategy aligned with financial goals.
Precious metals often respond to uncertainty
Several factors have driven the surge in gold and silver prices. One of the most important has been the recent tension between the White House and the Fed. This has raised questions about central bank independence and the direction of monetary policy, especially as Jerome Powell’s term as Fed chair ends in May 2026. Lower rates and the prospect of inflation put downward pressure on the dollar, so it’s natural for some investors to seek assets that can serve as a “store of value.”
Equally important is that central banks around the world have been consistent buyers of gold in recent years as they have diversified away from dollar-denominated reserves. Central banks need to hold enough reserves to manage their monetary policy and maintain the value of their currencies. These purchases of gold and other assets have accelerated amid heightened geopolitical uncertainty and concerns about currency stability.
Both metals have also benefited from their industrial applications, including in electric vehicles, solar panels, and artificial intelligence hardware. Thus, they serve roles as precious metals, safe haven assets, as well as industrial commodities.
Precious metal rallies are difficult to predict
Throughout history, periods of monetary policy uncertainty have coincided with strong precious metals performance. In the 1970s, for instance, both gold and silver climbed dramatically as stagflation hit the economy, peaking around 1980. Similarly, both rose from 2008 to 2011 during the global financial crisis, and then again during the 2020 pandemic.
In each of these cases, investors turned to precious metals when uncertainty about monetary policy and economic conditions peaked. However, both gold and silver prices began to reverse soon thereafter once conditions began to improve.
This creates at least two challenges for investors who are attracted to these investments based on recent performance. First, attempting to forecast gold and silver prices amounts to predicting the path of interest rates, inflation, and other factors like terms of trade. As the past several years have shown, these factors are difficult to forecast with certainty. Many concerns among investors and professional economists as inflation spiked in 2021 and 2022 did not materialize as expected.
Second, while it’s understandable that investors are drawn to assets that have performed well, history shows that precious metal rallies are notoriously difficult to time. The 1970s gold rally, for instance, was followed by two decades of declining prices. Gold peaked above $800 in 1980, a level it wouldn’t reach again until 2007.
The accompanying chart shows gold’s performance compared to the S&P 500 since the 2007 market peak. While gold has had periods of strong performance, the stock market has also performed well over these periods. For investors focused on recent precious metals rallies, this longer-term perspective may seem surprising. However, it makes sense since the stock market has historically risen over long periods of time.
This pattern extends to silver as well. Despite its strong industrial demand story, silver has experienced long periods of underperformance between rallies. For instance, silver experienced a strong rally in the late 1970s. As stagflation pushed silver higher, a famous episode occurred in which the Hunt brothers attempted to corner the market by accumulating stockpiles and buying futures contracts. While they drove prices higher for a time, prices eventually plummeted as new supply entered the market and when regulators introduced restrictions on leveraged buying of commodities.
Other precious metals exhibit similar behavior. Between 2016 and early 2022, palladium gained over 500%. This rally was driven by restricted global supply and greater use in applications such as catalytic converters for cars. However, after peaking, prices declined sharply over a two-year period.
Precious metals should be aligned with financial goals
These episodes demonstrate that, in situations where it makes sense for investors to have exposure to precious metals and commodities, gold and silver are best viewed as components of a broader commodities allocation or as part of alternative investments. The Bloomberg Commodity Index, for instance, currently allocates 14.9% to gold and 3.9% to silver, alongside other commodities such as industrial metals, energy, and agricultural products. This diversified approach to commodities exposure helps manage the volatility inherent in any single commodity.
The case for including precious metals in portfolios is based on the fact that they behave differently from stocks and bonds. Their value derives from scarcity, their roles as stores of value, and industrial uses. This means they often react to market and economic events differently from traditional asset classes, which can help to stabilize portfolios.
However, precious metals also carry important limitations. Most notably, they generate no income, unlike bonds or dividend-paying stocks. This lack of income also makes these assets difficult to value, which is another reason they are prone to booms and busts. A portfolio inappropriately weighted toward gold and silver may sacrifice the long-term growth potential of equities and the income generation of fixed income. So, even if precious metals might help in specific market environments, they may not be aligned with long-term goals.
The accompanying chart shows that many asset classes have contributed to portfolio returns recently, not just precious metals. While gold and silver have certainly performed well, there will always be individual investments that shine in particular periods. The key is constructing portfolios that can benefit from various market conditions rather than concentrating on recent winners.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Weekly Market Recap – The Fed Takes Action
Chart of the Month | 2026 Is Outperforming the Average Midterm Year
What’s Driving Portfolios: The Impact of High Oil and Copper Prices
Subscribe to Our Blog
Shareholder | Chief Investment Officer