Market Leadership Rotates as Investors Reassess the AI Trade
For your convenience, we’ve also provided a PDF copy of the Monthly Market Update: Market Leadership Rotates as Investors Reassess the AI Trade.
Monthly Market Summary
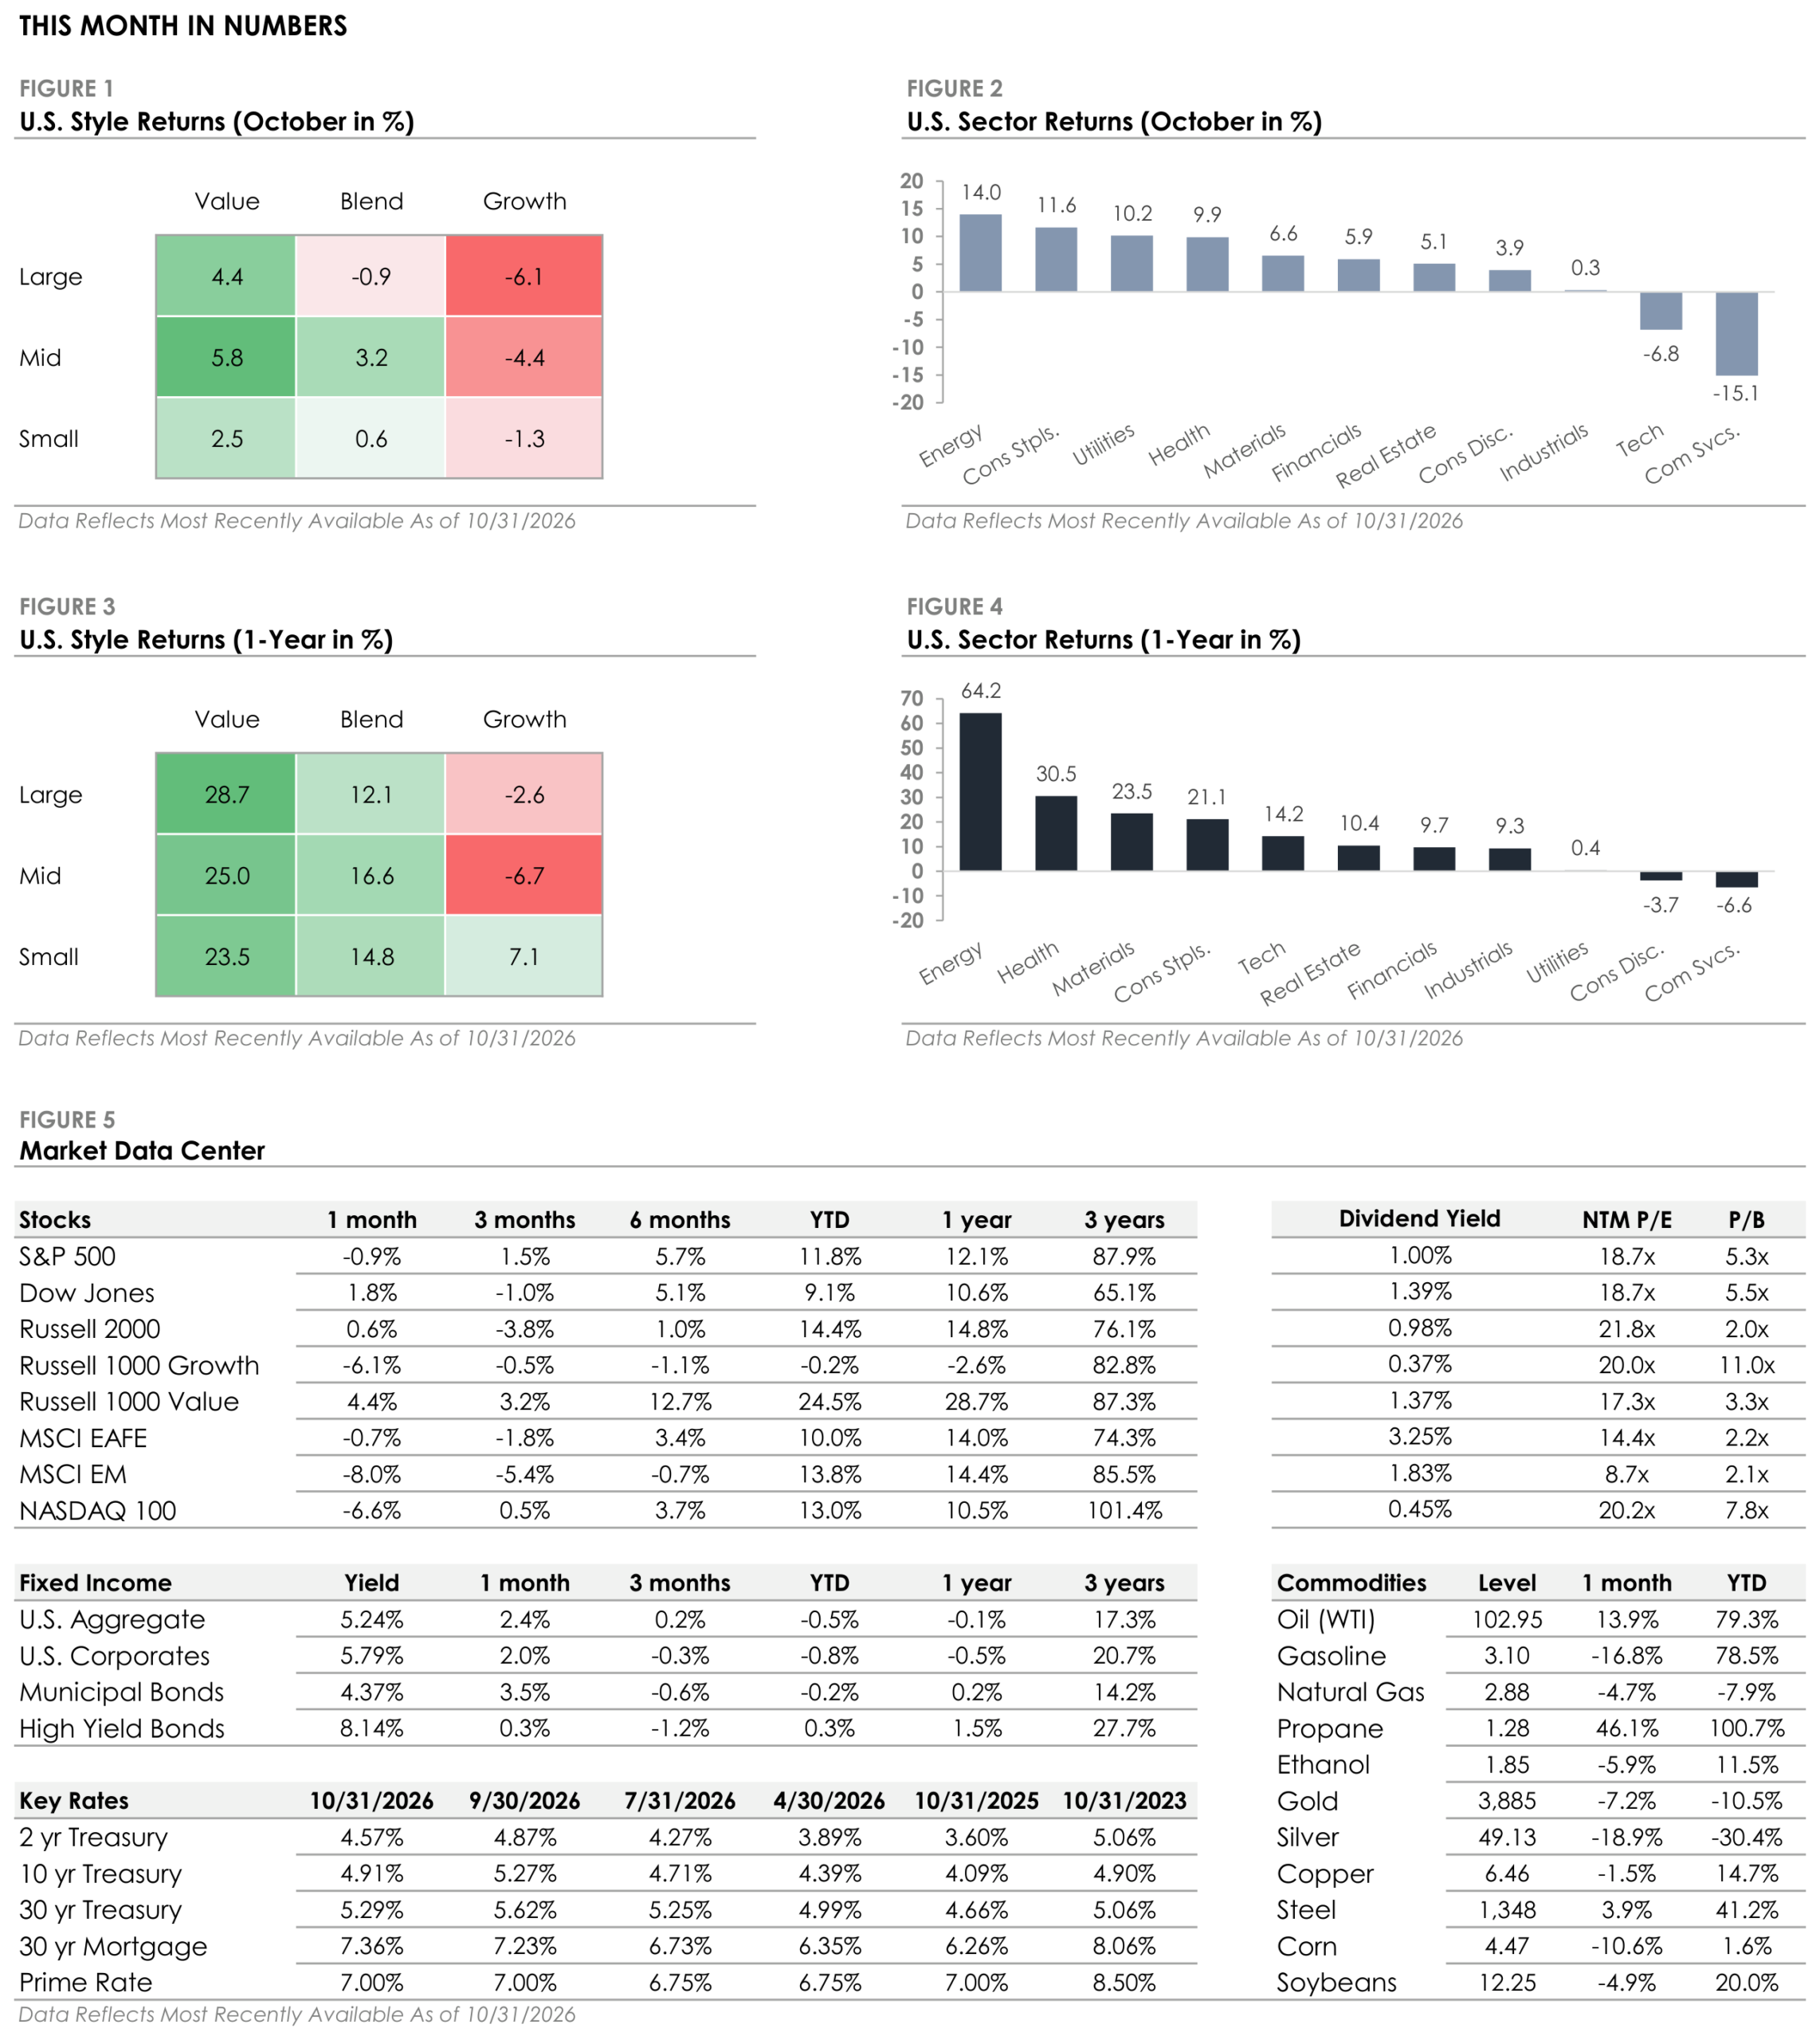
- The S&P 500 Index returned -0.9% in October, but the index’s decline masked broad strength across the market. The equal-weighted S&P 500 gained +5.0% and Large Cap Value rose +4.4%, while Large Cap Growth declined -6.1% and the Nasdaq 100 fell -6.6% as technology stocks traded lower.
- Energy (+14.0%) led all S&P 500 sectors as oil prices rose. Consumer Staples (+11.6%), Utilities (+10.2%), and Health Care (+9.9%) followed, as defensive sectors outperformed. Nine of the eleven sectors traded higher and outperformed the index, while Technology (-6.8%) and Communication Services (-15.1%) traded lower.
- Bonds traded higher as Treasury yields declined, with the U.S. Bond Aggregate returning +2.4%. Investment-grade corporate bonds gained +2.0% and outperformed high-yield’s +0.3% return as falling yields lifted higher-quality bonds.
- International stocks traded lower, led by emerging markets, which declined -8.0% as the selloff in semiconductor stocks weighed on South Korean and Taiwanese stocks. Developed markets were little changed, returning -0.7%.
Market Breadth Improves Even as Large Cap Tech Stocks Trade Lower
October was a better month for most stocks than the S&P 500’s small decline suggests. The index set a new all-time high early in the month, then traded lower as the largest technology companies came under pressure. The pressure carried into the final day of the month, when a weak outlook from Intel weighed on semiconductor and other AI-related stocks. However, the decline was relatively concentrated, with most of the market trading higher.
The equal-weighted S&P 500, which gives every company the same weight, outperformed the traditional index by nearly +6%, the widest margin in a single month since 2009. The performance gap comes from the way the traditional index gives its largest companies the most weight, so a pullback in a handful of mega-cap technology stocks can outweigh gains across hundreds of other companies.
The shift centered on artificial intelligence. Earlier this year, investors began asking whether the heavy spending on AI would pay off. October’s earnings reports sharpened that question. Demand for AI infrastructure remains strong, with cloud revenue at the largest technology companies growing rapidly. At the same time, investors drew a clearer line between companies that can pay for their capex with the cash flow their businesses generate and those that rely more on borrowing and issuing new shares.
Alphabet’s shares fell sharply after its quarterly spending exceeded the cash its business brought in. In contrast, Microsoft’s shares held steady after the company reported strong cloud growth and generated more than enough cash to cover its spending. Even after October’s market decline, semiconductor stocks are still up more than +50% this year, and the S&P 500 has gained more than +10%. Overall, the month looked less like a retreat from stocks and more like rotation, with gains broadening beyond the largest companies.
Bonds Rally as Treasury Yields Fall from Multi-Decade Highs
After a difficult third quarter, bonds rebounded in October and provided balance as technology stocks traded lower. The month didn’t start that way. Treasury yields rose in early October on concerns about inflation and heavy government borrowing, and the 30-year yield reached its highest level in more than two decades. Yields then reversed lower as investors turned to bonds during the stock market rotation. The 10-year Treasury yield ended the month just below 5%, down from about 5.3% in early October.
Because bond prices rise when yields fall, the decline lifted bond returns, with long-term Treasuries gaining more than +5%. Corporate bonds also traded higher, led by investment-grade bonds, which benefited most from falling yields. High-yield corporate bonds produced modest gains as corporate credit spreads widened, particularly among the lowest-rated high-yield borrowers.
The Federal Reserve held interest rates steady at its late-October meeting after raising rates in September, though two policymakers voted for another increase. The split reflects a tension that has run through much of this year. The economy remains on solid footing, growing at a +3.4% annual rate in the third quarter as consumers kept spending and businesses kept investing in AI.
However, inflation is still running above the Fed’s 2% target. Oil prices added to the pressure, rising about +14% in October after attacks on Saudi energy facilities renewed concerns about supply from the Middle East. Against this backdrop, markets expect another rate increase at the December meeting, and the inflation reports between now and then will help shape that decision.
Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Stock performance and fundamental data is based on the following instruments: SPDR S&P 500 ETF (SPY), SPDR Dow Jones ETF (DIA), iShares Russell 2000 ETF (IWM), iShares Russell 1000 Growth ETF (IWF), iShares Russell 1000 Value ETF (IWD), iShares MSCI EAFE ETF (EFA), iShares MSCI Emerging Markets ETF (EEM), Invesco QQQ Trust (QQQ).
Fixed Income performance is based on the following instruments: iShares Core U.S. Aggregate Bond ETF (AGG), iShares Investment Grade Corporate ETF (LQD), iShares National Muni Bond ETF (MUB), iShares High Yield Corporate ETF (HYG).
Fixed Income yields and key rates are based on the following instruments: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Benchmark Bond, 10 Year US Benchmark Bond, 30 Year US Benchmark Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate.
Commodity prices are based on the following instruments: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).
U.S. Style performance is based on the following instruments: iShares Russell 1000 Value ETF (IWD), SPDR S&P 500 ETF Trust (SPY), iShares Russell 1000 Growth ETF (IWF), iShares Russell Mid-Cap Value ETF (IWS), iShares Russell Midcap ETF (IWR), iShares Russell Mid-Cap Growth ETF (IWP), iShares Russell 2000 Value ETF (IWN), iShares Russell 2000 ETF (IWM), iShares Russell 2000 Growth ETF (IWO).
U.S. Sector performance is based on the following instruments: Consumer Discretionary Sector SPDR ETF (XLY), Consumer Staples Sector SPDR ETF (XLP), Energy Sector SPDR ETF (XLE), Financial Sector SPDR ETF (XLF), Health Care Sector SPDR ETF (XLV), Industrial Sector SPDR ETF (XLI), Materials Sector SPDR ETF (XLB), Technology Sector SPDR ETF (XLK), Communication Services Sector SPDR ETF (XLC), Utilities Sector SPDR ETF (XLU), Real Estate Sector SPDR ETF (XLRE).
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Monthly Market Update: Market Leadership Rotates as Investors Reassess the AI Trade
Market Leadership Rotates as Investors Reassess the AI Trade
For your convenience, we’ve also provided a PDF copy of the Monthly Market Update: Market Leadership Rotates as Investors Reassess the AI Trade.
Monthly Market Summary
Market Breadth Improves Even as Large Cap Tech Stocks Trade Lower
October was a better month for most stocks than the S&P 500’s small decline suggests. The index set a new all-time high early in the month, then traded lower as the largest technology companies came under pressure. The pressure carried into the final day of the month, when a weak outlook from Intel weighed on semiconductor and other AI-related stocks. However, the decline was relatively concentrated, with most of the market trading higher.
The equal-weighted S&P 500, which gives every company the same weight, outperformed the traditional index by nearly +6%, the widest margin in a single month since 2009. The performance gap comes from the way the traditional index gives its largest companies the most weight, so a pullback in a handful of mega-cap technology stocks can outweigh gains across hundreds of other companies.
The shift centered on artificial intelligence. Earlier this year, investors began asking whether the heavy spending on AI would pay off. October’s earnings reports sharpened that question. Demand for AI infrastructure remains strong, with cloud revenue at the largest technology companies growing rapidly. At the same time, investors drew a clearer line between companies that can pay for their capex with the cash flow their businesses generate and those that rely more on borrowing and issuing new shares.
Alphabet’s shares fell sharply after its quarterly spending exceeded the cash its business brought in. In contrast, Microsoft’s shares held steady after the company reported strong cloud growth and generated more than enough cash to cover its spending. Even after October’s market decline, semiconductor stocks are still up more than +50% this year, and the S&P 500 has gained more than +10%. Overall, the month looked less like a retreat from stocks and more like rotation, with gains broadening beyond the largest companies.
Bonds Rally as Treasury Yields Fall from Multi-Decade Highs
After a difficult third quarter, bonds rebounded in October and provided balance as technology stocks traded lower. The month didn’t start that way. Treasury yields rose in early October on concerns about inflation and heavy government borrowing, and the 30-year yield reached its highest level in more than two decades. Yields then reversed lower as investors turned to bonds during the stock market rotation. The 10-year Treasury yield ended the month just below 5%, down from about 5.3% in early October.
Because bond prices rise when yields fall, the decline lifted bond returns, with long-term Treasuries gaining more than +5%. Corporate bonds also traded higher, led by investment-grade bonds, which benefited most from falling yields. High-yield corporate bonds produced modest gains as corporate credit spreads widened, particularly among the lowest-rated high-yield borrowers.
The Federal Reserve held interest rates steady at its late-October meeting after raising rates in September, though two policymakers voted for another increase. The split reflects a tension that has run through much of this year. The economy remains on solid footing, growing at a +3.4% annual rate in the third quarter as consumers kept spending and businesses kept investing in AI.
However, inflation is still running above the Fed’s 2% target. Oil prices added to the pressure, rising about +14% in October after attacks on Saudi energy facilities renewed concerns about supply from the Middle East. Against this backdrop, markets expect another rate increase at the December meeting, and the inflation reports between now and then will help shape that decision.
Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Stock performance and fundamental data is based on the following instruments: SPDR S&P 500 ETF (SPY), SPDR Dow Jones ETF (DIA), iShares Russell 2000 ETF (IWM), iShares Russell 1000 Growth ETF (IWF), iShares Russell 1000 Value ETF (IWD), iShares MSCI EAFE ETF (EFA), iShares MSCI Emerging Markets ETF (EEM), Invesco QQQ Trust (QQQ).
Fixed Income performance is based on the following instruments: iShares Core U.S. Aggregate Bond ETF (AGG), iShares Investment Grade Corporate ETF (LQD), iShares National Muni Bond ETF (MUB), iShares High Yield Corporate ETF (HYG).
Fixed Income yields and key rates are based on the following instruments: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Benchmark Bond, 10 Year US Benchmark Bond, 30 Year US Benchmark Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate.
Commodity prices are based on the following instruments: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).
U.S. Style performance is based on the following instruments: iShares Russell 1000 Value ETF (IWD), SPDR S&P 500 ETF Trust (SPY), iShares Russell 1000 Growth ETF (IWF), iShares Russell Mid-Cap Value ETF (IWS), iShares Russell Midcap ETF (IWR), iShares Russell Mid-Cap Growth ETF (IWP), iShares Russell 2000 Value ETF (IWN), iShares Russell 2000 ETF (IWM), iShares Russell 2000 Growth ETF (IWO).
U.S. Sector performance is based on the following instruments: Consumer Discretionary Sector SPDR ETF (XLY), Consumer Staples Sector SPDR ETF (XLP), Energy Sector SPDR ETF (XLE), Financial Sector SPDR ETF (XLF), Health Care Sector SPDR ETF (XLV), Industrial Sector SPDR ETF (XLI), Materials Sector SPDR ETF (XLB), Technology Sector SPDR ETF (XLK), Communication Services Sector SPDR ETF (XLC), Utilities Sector SPDR ETF (XLU), Real Estate Sector SPDR ETF (XLRE).
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Monthly Market Update: Market Leadership Rotates as Investors Reassess the AI Trade
Weekly Market Recap – Beneath the Headlines, Most of the Market Moved Higher
Trump Accounts: A New Way to Save for Children
Subscribe to Our Blog
Chief Investment Officer | Managing Partner