Energy Infrastructure, Inflation Pressures, Fed Policy, Market Volatility, & AI Demand
Weekly Market Recap
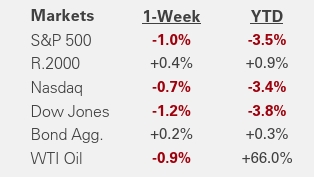 This week mirrored last week: stocks traded higher early, then fell and finished lower in a late-week selloff. The major equities were flat to modestly lower as the Middle East conflict continued, with large caps, small caps, the Nasdaq, and the Dow producing similar returns. Energy was the top-performing sector for a second week, with technology and financial stocks also gaining slightly.
Bonds traded higher as the rise in Treasury yields slowed, and longer-maturity bonds outperformed as yields stabilized. Commodities traded lower: oil ended lower but remained stuck near $100 per barrel, gold fell despite market volatility and inflation concerns, and copper dropped nearly -4%. The VIX Index fell below 25 but remains elevated due to unresolved geopolitical tensions.
Key Takeaways
The Middle East Conflict Escalates Into Energy Infrastructure
Israel struck Iran’s South Pars gas field, the world’s largest natural gas reserve, and Iran responded by targeting energy infrastructure across the Middle East, disrupting oil and gas production. The conflict has moved beyond shipping-lane disruptions to direct damage to production infrastructure, which can take months or years to repair, not weeks. Implication – A ceasefire won’t necessarily restore energy supply quickly. Damaged facilities will have to be repaired and rebuilt, which means energy prices could have a structural floor that keeps oil and gas prices higher even if the conflict ends.
Producer Prices Were Rising Before the Conflict
The Producer Price Index rose 0.7% m/m in February, the hottest monthly PPI reading since July 2025 and the third consecutive month of acceleration. Headline PPI accelerated to 3.4% y/y from 2.9% in January, and core PPI rose to 3.9% from 3.5%. The data preceded the conflict and sharp rise in oil prices, suggesting inflation pressure was building before the oil spike. The composition also mattered: services drove the increase, pointing to broader pricing pressures than just oil. Implication – Services-driven inflation is harder to dismiss as transitory and suggests the Fed faces a potential dual battle: goods inflation from energy and services inflation from structural factors.
Fed Holds Rates Steady & Rate Cut Expectations Pushed Into 2027
The Fed held rates steady at 3.50–3.75% this week and raised its 2026 inflation forecast to 2.7%, up from 2.4% in December. Chair Powell acknowledged that a rate hike was discussed at the meeting, though he added that a hike isn’t the base case. While the Fed still projects one cut this year, futures markets moved past the Fed’s forecast. The market expects no rate cuts this year, with the next cut not forecast until July 2027. Implication – The shift from “when will the Fed cut” to “will the Fed cut at all” is a significant change. Earlier this year, the market expected two rate cuts in 2026, but the narrative is moving toward interest rates remaining higher for longer.
The Stock Market Remains Choppy
The S&P 500 rallied over +1.0% early in the week before giving it back as tensions escalated, oil prices rose, and rate cut expectations were delayed. The S&P 500 is now roughly -5% below its all-time high in late January and down about -3.5% for the year. However, the indicators associated with more serious market stress aren’t yet flashing. The VIX declined during the week and sits near 25, which is elevated but below panic levels. Credit spreads also tightened this week, a countertrend relief rally suggesting the credit market is not pricing imminent stress. Implication – The pattern of rallying on de-escalation hopes and selling on reality has held for multiple weeks; a durable break in either direction would change the picture, but the current setup remains heightened uncertainty rather than crisis.
AI Demand Signals Remain Strong
Nvidia’s developer conference reinforced strong demand for AI, with the company expecting ~$1 trillion in chip orders through 2027, double last October’s figure. Separately, Micron reported quarterly revenue of $23.9 billion, nearly triple last year. Implication – While markets have been volatile, the commentary suggests AI infrastructure spending remains strong. The market will be watching to see if the conflict impacts spending plans, such as tighter financing conditions or smaller budgets tied to economic uncertainty.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Weekly Market Recap | March 20, 2026
Energy Infrastructure, Inflation Pressures, Fed Policy, Market Volatility, & AI Demand
Weekly Market Recap
Bonds traded higher as the rise in Treasury yields slowed, and longer-maturity bonds outperformed as yields stabilized. Commodities traded lower: oil ended lower but remained stuck near $100 per barrel, gold fell despite market volatility and inflation concerns, and copper dropped nearly -4%. The VIX Index fell below 25 but remains elevated due to unresolved geopolitical tensions.
Key Takeaways
The Middle East Conflict Escalates Into Energy Infrastructure
Israel struck Iran’s South Pars gas field, the world’s largest natural gas reserve, and Iran responded by targeting energy infrastructure across the Middle East, disrupting oil and gas production. The conflict has moved beyond shipping-lane disruptions to direct damage to production infrastructure, which can take months or years to repair, not weeks. Implication – A ceasefire won’t necessarily restore energy supply quickly. Damaged facilities will have to be repaired and rebuilt, which means energy prices could have a structural floor that keeps oil and gas prices higher even if the conflict ends.
Producer Prices Were Rising Before the Conflict
The Producer Price Index rose 0.7% m/m in February, the hottest monthly PPI reading since July 2025 and the third consecutive month of acceleration. Headline PPI accelerated to 3.4% y/y from 2.9% in January, and core PPI rose to 3.9% from 3.5%. The data preceded the conflict and sharp rise in oil prices, suggesting inflation pressure was building before the oil spike. The composition also mattered: services drove the increase, pointing to broader pricing pressures than just oil. Implication – Services-driven inflation is harder to dismiss as transitory and suggests the Fed faces a potential dual battle: goods inflation from energy and services inflation from structural factors.
Fed Holds Rates Steady & Rate Cut Expectations Pushed Into 2027
The Fed held rates steady at 3.50–3.75% this week and raised its 2026 inflation forecast to 2.7%, up from 2.4% in December. Chair Powell acknowledged that a rate hike was discussed at the meeting, though he added that a hike isn’t the base case. While the Fed still projects one cut this year, futures markets moved past the Fed’s forecast. The market expects no rate cuts this year, with the next cut not forecast until July 2027. Implication – The shift from “when will the Fed cut” to “will the Fed cut at all” is a significant change. Earlier this year, the market expected two rate cuts in 2026, but the narrative is moving toward interest rates remaining higher for longer.
The Stock Market Remains Choppy
The S&P 500 rallied over +1.0% early in the week before giving it back as tensions escalated, oil prices rose, and rate cut expectations were delayed. The S&P 500 is now roughly -5% below its all-time high in late January and down about -3.5% for the year. However, the indicators associated with more serious market stress aren’t yet flashing. The VIX declined during the week and sits near 25, which is elevated but below panic levels. Credit spreads also tightened this week, a countertrend relief rally suggesting the credit market is not pricing imminent stress. Implication – The pattern of rallying on de-escalation hopes and selling on reality has held for multiple weeks; a durable break in either direction would change the picture, but the current setup remains heightened uncertainty rather than crisis.
AI Demand Signals Remain Strong
Nvidia’s developer conference reinforced strong demand for AI, with the company expecting ~$1 trillion in chip orders through 2027, double last October’s figure. Separately, Micron reported quarterly revenue of $23.9 billion, nearly triple last year. Implication – While markets have been volatile, the commentary suggests AI infrastructure spending remains strong. The market will be watching to see if the conflict impacts spending plans, such as tighter financing conditions or smaller budgets tied to economic uncertainty.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Happy Birthday to the Bull Market
Quarterly Webinar: Q4 2026 Market and Economic Themes
Medicare Open Enrollment 2026: What to Know
Subscribe to Our Blog
Chief Investment Officer | Managing Partner