Beneath the Headlines, Most of the Market Moved Higher
I couldn’t help it… It’s Halloween 🎃
A sharp selloff in a handful of large technology stocks grabbed attention this week, while bonds rallied and most sectors gained ground.
The Week in Brief
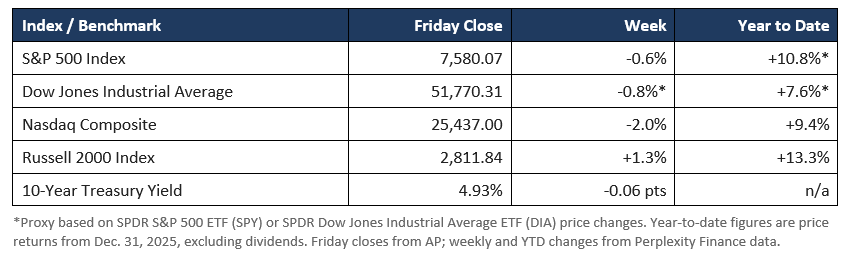
- Large technology companies fell after several reported heavy spending on artificial intelligence (AI) without the cash flow investors hoped to see. The Nasdaq Composite fell 2.0% for the week.
- Most of the market held up well. Nine of the 11 major S&P 500 sectors rose, and smaller companies (the Russell 2000) gained 1.3%.
- Bonds did their job. The 10-year Treasury yield fell to 4.93% as investors looked for safety, which lifted bond prices.
- The Federal Reserve held interest rates steady, while the economy grew at a solid 3.4% pace last quarter.
Market Scorecard
Stocks
It was a tale of two markets. On one side, a few of the largest technology companies, which make up a big share of the major indexes, had a rough week. Alphabet (Google’s parent) had its largest one-day drop on record on Thursday, and on Friday Intel fell almost 29% after a disappointing outlook while Amazon raised fresh questions about AI spending. The common thread: investors are asking when the enormous sums being spent on AI will pay off.
On the other side, most stocks quietly moved higher. Health care, materials, utilities, and consumer companies all gained ground for the week, and smaller companies outperformed. The S&P 500 finished the week down 0.6% and the Dow fell 0.8%, but those headline numbers hide how broad the gains were underneath. It is a good reminder of why we diversify. When one part of the market stumbles, other parts can help steady the ship.
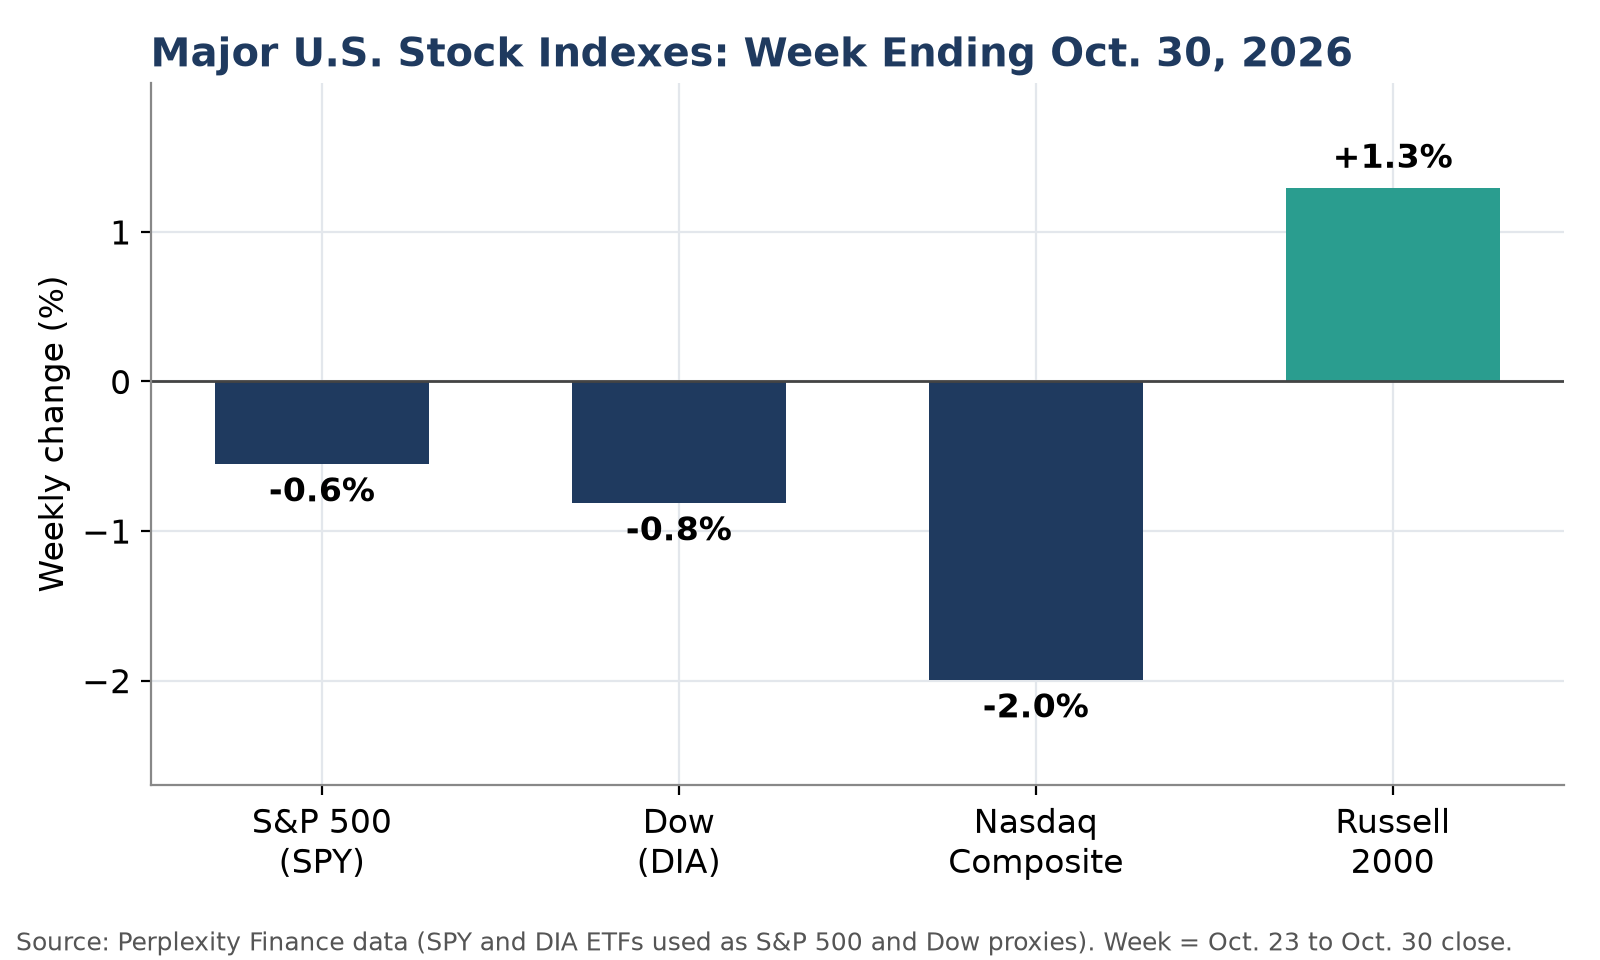
Chart 1. The Nasdaq Composite fell the most this week, while smaller companies in the Russell 2000 Index posted a gain.
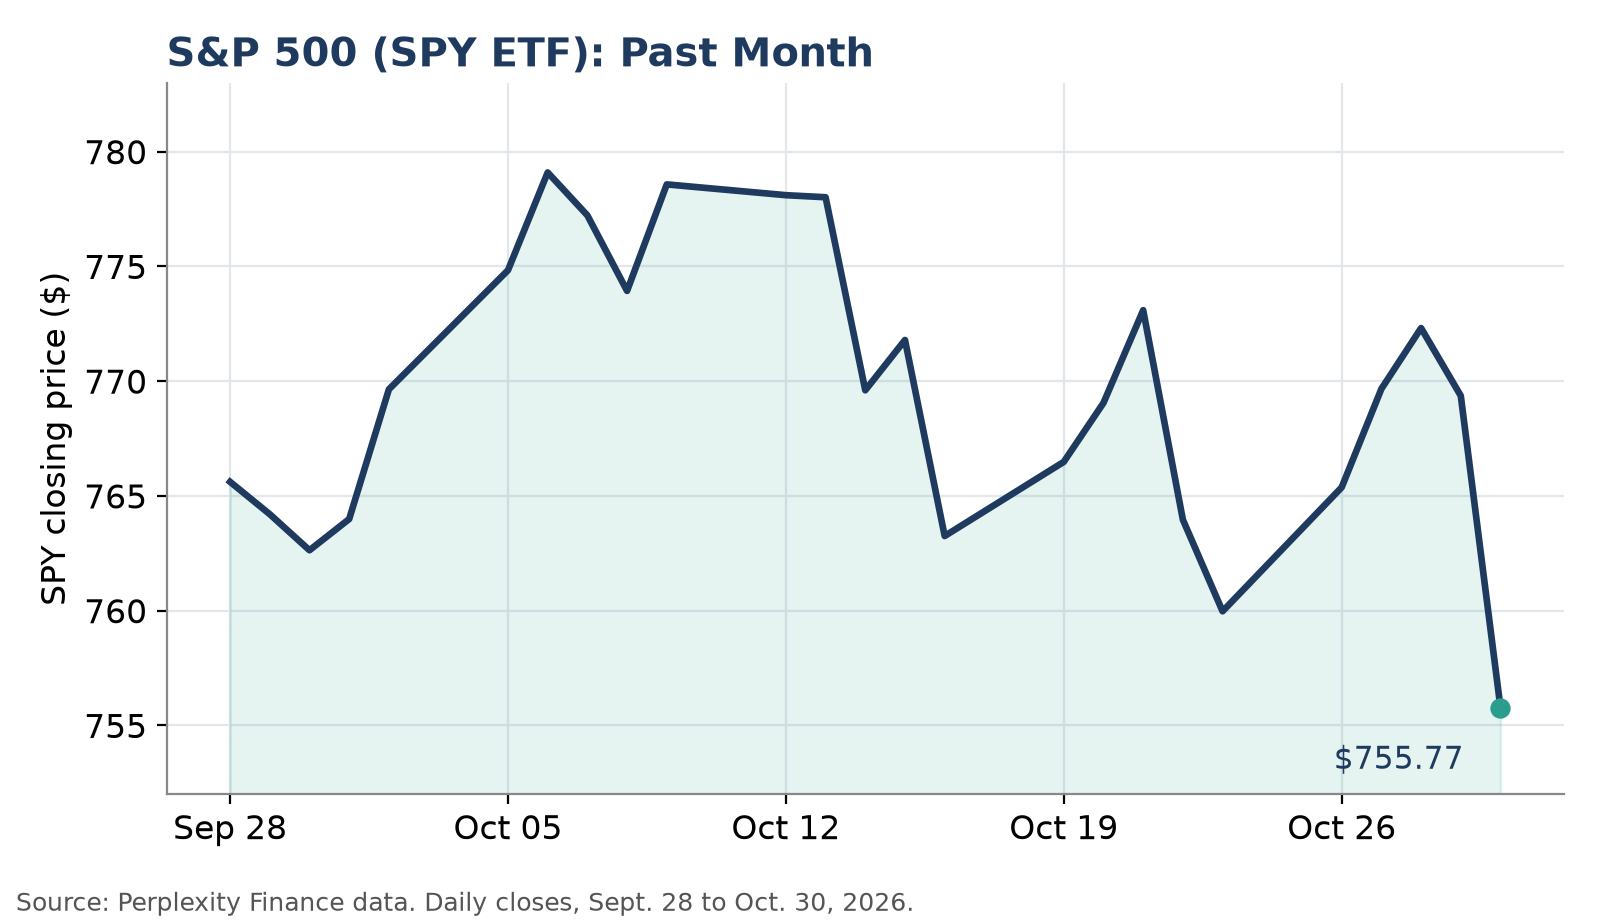
Chart 2. The S&P 500 (shown through the SPY ETF) moved in a fairly narrow range for most of October before Friday’s decline took it to its lowest close of the past month.
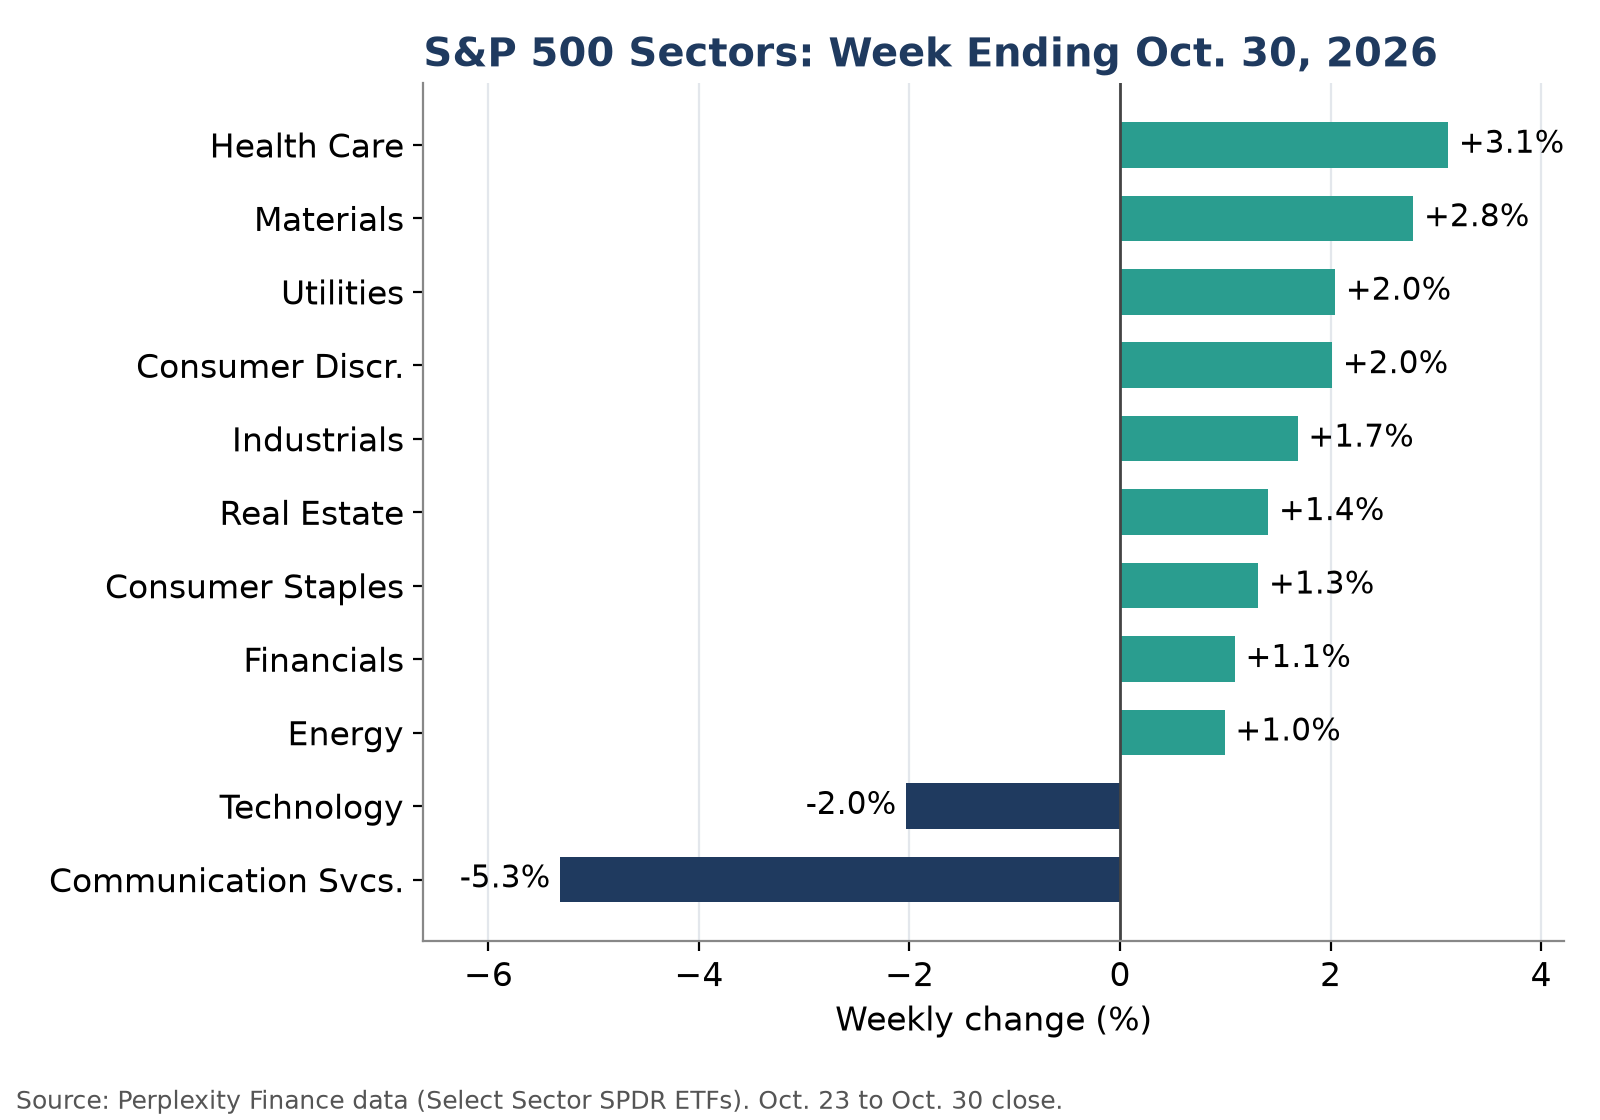
Chart 3. Nine of the 11 S&P 500 sectors rose for the week; only technology and communication services declined.
Bonds & Interest Rates
Bonds had a strong week. The 10-year Treasury yield, a key benchmark for mortgage and borrowing rates, fell to 4.93%, down from more than 5.3% earlier in October. When yields fall, the prices of existing bonds rise, so high-quality bond holdings gained value this week, including Treasury, corporate, and municipal bonds.
This is exactly the role bonds are meant to play in a diversified portfolio. They provide income and can help cushion the impact when stocks are volatile. With the 10-year yield still near 5%, high-quality bonds also continue to offer meaningful income.
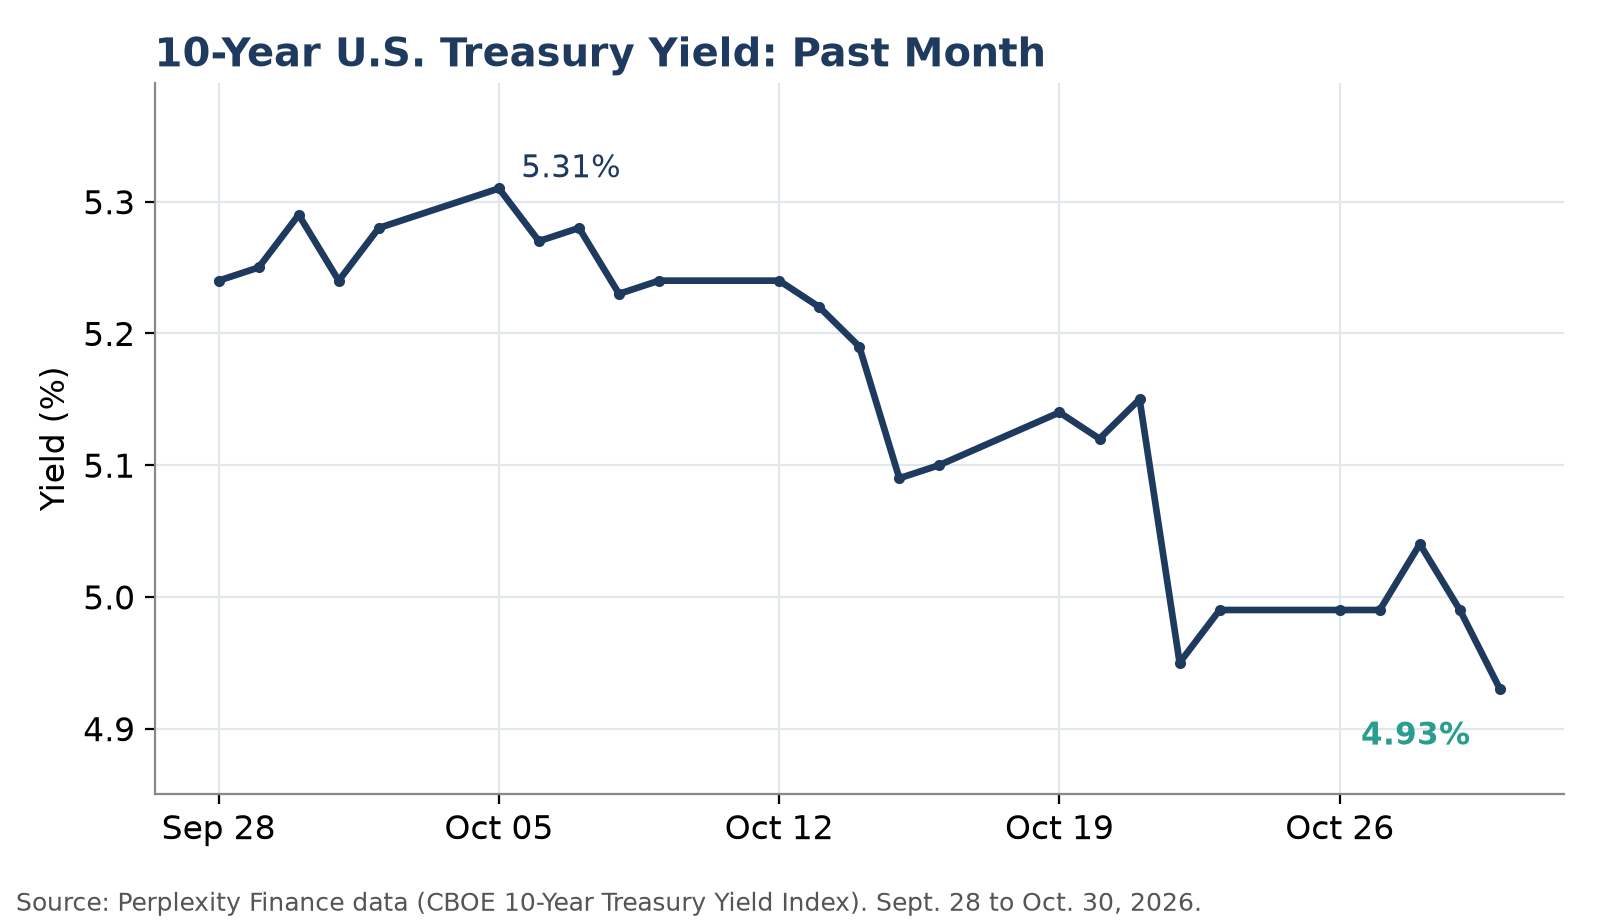
Chart 4. The 10-year Treasury yield fell from 5.31% in early October to 4.93% on Friday, which lifted bond prices.
The Economy & the Fed
The economy continues to show resilience. Gross domestic product (GDP), the broadest measure of economic activity, grew at a 3.4% annual rate in the third quarter, faster than expected. Consumer confidence also improved this week.
Inflation, however, remains above the Federal Reserve’s goal. The Fed’s preferred inflation measure rose 3.1% over the past year, excluding food and energy, and higher oil prices (around $104 per barrel) are adding pressure. The Fed held interest rates steady on Wednesday, but two officials voted for an increase, and markets are pricing a meaningful chance of a rate hike in December.
What We’re Watching Next Week
- U.S. midterm elections on Tuesday, November 3. Elections can create short-term market noise, though over longer periods markets have tended to respond more to the economy and corporate earnings than to election outcomes.
- The October jobs report on Friday, November 6, an important read on the strength of the labor market.
- More company earnings, including Apple, Palantir, AMD, and Qualcomm.
- Central bank decisions abroad, including the Bank of England.
Our Perspective
Weeks like this one can feel unsettling, especially when headlines focus on big drops in well-known companies. But look a little closer and the picture is more balanced: most sectors rose, small companies gained, and bonds provided a cushion. That is diversification working as designed.
We continue to focus on what we can control: owning a diversified mix of investments, keeping portfolios aligned with each client’s goals and risk tolerance, and rebalancing when markets move. Short-term swings are a normal part of investing, and reacting to them rarely helps long-term results.
If you have questions about your portfolio or how recent market events affect your plan, please reach out to your Financial Synergies Wealth Advisors advisor. We are always happy to talk.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies Wealth Advisors:
Sources
AP: How major U.S. stock indexes fared (Oct. 30, 2026): https://apnews.com/article/a01d3551e794fed1a0c317c20bc3f0a2
AP: Sell-off for tech stocks worsens (Oct. 30, 2026): https://www.adn.com/business-economy/2026/10/30/sell-off-for-tech-stocks-worsens-and-drowns-out-strength-elsewhere-on-wall-street
Reuters via News & Observer: Treasuries in October: https://www.newsobserver.com/news/business/article317843519.html
Prior-week S&P 500 close (Reuters summary): https://truthnetworkdaily.com/articles/wall-street-friday-close-sp500-nasdaq-weekly-loss-dow-third-weekly-gain/
CNBC: Stock market live updates (Oct. 29, 2026): https://www.cnbc.com/2026/10/29/stock-market-today-live-updates.html
U.S. Bureau of Economic Analysis: GDP, Q3 2026 advance estimate: https://www.bea.gov/index.php/news/2026/gdp-advance-estimate-3rd-quarter-2026
Joint Economic Committee: Q3 GDP and September inflation: https://www.jec.senate.gov/public/index.cfm/republicans/2026/10/q3-gdp-increased-and-better-than-expected-september-inflation-up-disposable-income-down
Yahoo Finance: Fed meeting live updates (Oct. 28, 2026): https://finance.yahoo.com/economy/policy/live/fed-meeting-live-updates-federal-reserve-october-meeting-kevin-warsh-161129201.html
TheStreet Pro: Consumer confidence rebounds: https://pro.thestreet.com/market-commentary/consumer-confidence-rebounds-to-highest-since-june
Wall St Week Ahead: December Fed hike odds: https://tech-insider.org/wall-st-week-ahead-midterms-jobs-fed-hike-odds-ai-market-2026/
investingLive: Week ahead calendar: https://investinglive.com/news/week-ahead-elections-rate-decisions-and-jobs-take-center-stage/
CMC Markets: The week ahead: https://www.cmcmarkets.com/en-gb/news-and-analysis/the-week-ahead-ism-pmi-reports-us-jobs-report-apple-earnings
U.S. Treasury: Daily Treasury par yield curve rates: https://home.treasury.gov/resource-center/data-chart-center/interest-rates/daily-treasury-rates.csv/2026/all?type=daily_treasury_yield_curve
Perplexity Finance: index, ETF, yield, and sector data: https://www.perplexity.ai/finance
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Weekly Market Recap – Beneath the Headlines, Most of the Market Moved Higher
Beneath the Headlines, Most of the Market Moved Higher
I couldn’t help it… It’s Halloween 🎃
A sharp selloff in a handful of large technology stocks grabbed attention this week, while bonds rallied and most sectors gained ground.
The Week in Brief
Market Scorecard
Stocks
It was a tale of two markets. On one side, a few of the largest technology companies, which make up a big share of the major indexes, had a rough week. Alphabet (Google’s parent) had its largest one-day drop on record on Thursday, and on Friday Intel fell almost 29% after a disappointing outlook while Amazon raised fresh questions about AI spending. The common thread: investors are asking when the enormous sums being spent on AI will pay off.
On the other side, most stocks quietly moved higher. Health care, materials, utilities, and consumer companies all gained ground for the week, and smaller companies outperformed. The S&P 500 finished the week down 0.6% and the Dow fell 0.8%, but those headline numbers hide how broad the gains were underneath. It is a good reminder of why we diversify. When one part of the market stumbles, other parts can help steady the ship.
Chart 1. The Nasdaq Composite fell the most this week, while smaller companies in the Russell 2000 Index posted a gain.
Chart 2. The S&P 500 (shown through the SPY ETF) moved in a fairly narrow range for most of October before Friday’s decline took it to its lowest close of the past month.
Chart 3. Nine of the 11 S&P 500 sectors rose for the week; only technology and communication services declined.
Bonds & Interest Rates
Bonds had a strong week. The 10-year Treasury yield, a key benchmark for mortgage and borrowing rates, fell to 4.93%, down from more than 5.3% earlier in October. When yields fall, the prices of existing bonds rise, so high-quality bond holdings gained value this week, including Treasury, corporate, and municipal bonds.
This is exactly the role bonds are meant to play in a diversified portfolio. They provide income and can help cushion the impact when stocks are volatile. With the 10-year yield still near 5%, high-quality bonds also continue to offer meaningful income.
Chart 4. The 10-year Treasury yield fell from 5.31% in early October to 4.93% on Friday, which lifted bond prices.
The Economy & the Fed
The economy continues to show resilience. Gross domestic product (GDP), the broadest measure of economic activity, grew at a 3.4% annual rate in the third quarter, faster than expected. Consumer confidence also improved this week.
Inflation, however, remains above the Federal Reserve’s goal. The Fed’s preferred inflation measure rose 3.1% over the past year, excluding food and energy, and higher oil prices (around $104 per barrel) are adding pressure. The Fed held interest rates steady on Wednesday, but two officials voted for an increase, and markets are pricing a meaningful chance of a rate hike in December.
What We’re Watching Next Week
Our Perspective
Weeks like this one can feel unsettling, especially when headlines focus on big drops in well-known companies. But look a little closer and the picture is more balanced: most sectors rose, small companies gained, and bonds provided a cushion. That is diversification working as designed.
We continue to focus on what we can control: owning a diversified mix of investments, keeping portfolios aligned with each client’s goals and risk tolerance, and rebalancing when markets move. Short-term swings are a normal part of investing, and reacting to them rarely helps long-term results.
If you have questions about your portfolio or how recent market events affect your plan, please reach out to your Financial Synergies Wealth Advisors advisor. We are always happy to talk.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies Wealth Advisors:
Sources
AP: How major U.S. stock indexes fared (Oct. 30, 2026): https://apnews.com/article/a01d3551e794fed1a0c317c20bc3f0a2
AP: Sell-off for tech stocks worsens (Oct. 30, 2026): https://www.adn.com/business-economy/2026/10/30/sell-off-for-tech-stocks-worsens-and-drowns-out-strength-elsewhere-on-wall-street
Reuters via News & Observer: Treasuries in October: https://www.newsobserver.com/news/business/article317843519.html
Prior-week S&P 500 close (Reuters summary): https://truthnetworkdaily.com/articles/wall-street-friday-close-sp500-nasdaq-weekly-loss-dow-third-weekly-gain/
CNBC: Stock market live updates (Oct. 29, 2026): https://www.cnbc.com/2026/10/29/stock-market-today-live-updates.html
U.S. Bureau of Economic Analysis: GDP, Q3 2026 advance estimate: https://www.bea.gov/index.php/news/2026/gdp-advance-estimate-3rd-quarter-2026
Joint Economic Committee: Q3 GDP and September inflation: https://www.jec.senate.gov/public/index.cfm/republicans/2026/10/q3-gdp-increased-and-better-than-expected-september-inflation-up-disposable-income-down
Yahoo Finance: Fed meeting live updates (Oct. 28, 2026): https://finance.yahoo.com/economy/policy/live/fed-meeting-live-updates-federal-reserve-october-meeting-kevin-warsh-161129201.html
TheStreet Pro: Consumer confidence rebounds: https://pro.thestreet.com/market-commentary/consumer-confidence-rebounds-to-highest-since-june
Wall St Week Ahead: December Fed hike odds: https://tech-insider.org/wall-st-week-ahead-midterms-jobs-fed-hike-odds-ai-market-2026/
investingLive: Week ahead calendar: https://investinglive.com/news/week-ahead-elections-rate-decisions-and-jobs-take-center-stage/
CMC Markets: The week ahead: https://www.cmcmarkets.com/en-gb/news-and-analysis/the-week-ahead-ism-pmi-reports-us-jobs-report-apple-earnings
U.S. Treasury: Daily Treasury par yield curve rates: https://home.treasury.gov/resource-center/data-chart-center/interest-rates/daily-treasury-rates.csv/2026/all?type=daily_treasury_yield_curve
Perplexity Finance: index, ETF, yield, and sector data: https://www.perplexity.ai/finance
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Weekly Market Recap – Beneath the Headlines, Most of the Market Moved Higher
Trump Accounts: A New Way to Save for Children
Step Inside Our Office to Meet the Financial Synergies Team
Subscribe to Our Blog
Chief Investment Officer | Managing Partner