Soft Jobs Growth, Easing Inflation, Solid Consumer Spending, & Uncertain Fed Policy
Weekly Market Recap
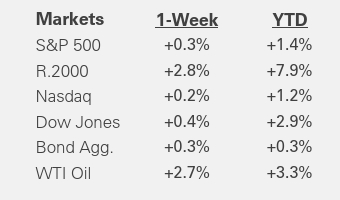 Markets were mixed this week, with last week’s rotation carrying over. The S&P 500 and Nasdaq produced modest gains, while small caps, value, and equal-weight benchmarks outperformed, highlighting the continued change in market leadership. Treasury yields fluctuated throughout the week, responding to a combination of falling unemployment, easing inflation, and solid consumer spending. Shorter-maturity Treasury yields rose as expectations for a near-term rate cut diminished, while longer-maturity yields declined. Longer-maturity Treasury and corporate bonds outperformed, while corporate high-yield was flat. Commodities rallied, led by a sharp rise in oil and gains in gold and copper, and bitcoin rose to the highest level since mid-November.
Key Takeaways
Job Growth Slows, but Wage Growth Remains Strong
December jobs data showed that labor market conditions continue to cool. U.S. companies added 50,000 jobs last month, slightly below expectations, with unemployment falling from 4.6% to 4.4%. Excluding the pandemic, 2025 was the slowest year of job growth since 2010. Despite softer job growth, wage gains remained solid at 0.3% month-over-month and 3.8% year-over-year, keeping inflation concerns in focus. Why it matters: The combination of slowing job gains and steady wage growth leaves the outlook for rate cuts uncertain. Labor conditions have cooled but remain solid, while wage growth remains elevated compared to before the pandemic.
Inflation and Consumer Spending Provide Mixed Signals
Later in the week, inflation and consumer spending data provided mixed signals. Core CPI rose +0.2% month-over-month in December, below expectations and in line with September 2025, the last release before the government shutdown. Retail sales rose +0.6% in November, above forecast and the highest since August 2025. Why it matters: Inflation continues to moderate, while consumer spending remains resilient. These conflicting signals have kept markets in a holding pattern and reinforced the view that neither growth nor inflation is providing a clear direction for Fed policy.
Interest Rate Cut Expectations Pushed Further Out
The near-term policy outlook has become clearer, but the outlook for later this year remains uncertain. The Fed’s next meeting is the last week of January, and markets place a nearly 100% probability that rates will remain unchanged. No rate cuts are expected at the March or April meetings either, with the next rate cut anticipated in June. The market is pricing in a similar rate cut timeline to last year: a pause in the first half of the year, with potential cuts later in the year. Why it matters: The week ended with unresolved Fed policy expectations, keeping markets in a holding pattern and driving a rotation across asset classes.
Market Leadership Continues to Shift and Asset Class Pricing Shows Lack of Consensus
Market leadership continued to rotate this week. The S&P 500 posted a modest gain, but there was a clear rotation beneath the surface, with small-cap stocks outperforming for a second consecutive week. Commodities and cryptocurrencies posted strong gains with sometimes conflicting signals, like gold, oil, and bitcoin trading higher together. The continued equity market rotation and lack of a unified risk-on or risk-off pattern across asset classes underscored the week’s theme of fragmentation and cross-asset inconsistency. Why it matters: The mixed results across equities, commodities, and crypto reflect a lack of consensus around major themes like Fed policy and economic growth.
Policy and Geopolitics Create Headline Noise With a Limited Market Impact
Government policy and geopolitical headlines contributed to the unsettled market tone this week. The White House announced an investigation of Fed Chair Powell, raising concerns about the Fed’s credibility and independence. There were proposals to buy mortgage-backed securities in an effort to lower mortgage rates and ease housing pressures, along with a proposal to cap credit card fees. Meanwhile, renewed tensions with Iran added to commodity volatility, particularly in oil, but did not drive a broader flight to safety. Why it matters: The market is digesting a steady stream of policy and regulatory headlines, but they haven’t sparked a clear reaction. Instead, they’re viewed as background noise or filed away as longer-term considerations with no immediate market impact.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Weekly Market Recap | Jan. 16, 2026
Soft Jobs Growth, Easing Inflation, Solid Consumer Spending, & Uncertain Fed Policy
Weekly Market Recap
Key Takeaways
Job Growth Slows, but Wage Growth Remains Strong
December jobs data showed that labor market conditions continue to cool. U.S. companies added 50,000 jobs last month, slightly below expectations, with unemployment falling from 4.6% to 4.4%. Excluding the pandemic, 2025 was the slowest year of job growth since 2010. Despite softer job growth, wage gains remained solid at 0.3% month-over-month and 3.8% year-over-year, keeping inflation concerns in focus. Why it matters: The combination of slowing job gains and steady wage growth leaves the outlook for rate cuts uncertain. Labor conditions have cooled but remain solid, while wage growth remains elevated compared to before the pandemic.
Inflation and Consumer Spending Provide Mixed Signals
Later in the week, inflation and consumer spending data provided mixed signals. Core CPI rose +0.2% month-over-month in December, below expectations and in line with September 2025, the last release before the government shutdown. Retail sales rose +0.6% in November, above forecast and the highest since August 2025. Why it matters: Inflation continues to moderate, while consumer spending remains resilient. These conflicting signals have kept markets in a holding pattern and reinforced the view that neither growth nor inflation is providing a clear direction for Fed policy.
Interest Rate Cut Expectations Pushed Further Out
The near-term policy outlook has become clearer, but the outlook for later this year remains uncertain. The Fed’s next meeting is the last week of January, and markets place a nearly 100% probability that rates will remain unchanged. No rate cuts are expected at the March or April meetings either, with the next rate cut anticipated in June. The market is pricing in a similar rate cut timeline to last year: a pause in the first half of the year, with potential cuts later in the year. Why it matters: The week ended with unresolved Fed policy expectations, keeping markets in a holding pattern and driving a rotation across asset classes.
Market Leadership Continues to Shift and Asset Class Pricing Shows Lack of Consensus
Market leadership continued to rotate this week. The S&P 500 posted a modest gain, but there was a clear rotation beneath the surface, with small-cap stocks outperforming for a second consecutive week. Commodities and cryptocurrencies posted strong gains with sometimes conflicting signals, like gold, oil, and bitcoin trading higher together. The continued equity market rotation and lack of a unified risk-on or risk-off pattern across asset classes underscored the week’s theme of fragmentation and cross-asset inconsistency. Why it matters: The mixed results across equities, commodities, and crypto reflect a lack of consensus around major themes like Fed policy and economic growth.
Policy and Geopolitics Create Headline Noise With a Limited Market Impact
Government policy and geopolitical headlines contributed to the unsettled market tone this week. The White House announced an investigation of Fed Chair Powell, raising concerns about the Fed’s credibility and independence. There were proposals to buy mortgage-backed securities in an effort to lower mortgage rates and ease housing pressures, along with a proposal to cap credit card fees. Meanwhile, renewed tensions with Iran added to commodity volatility, particularly in oil, but did not drive a broader flight to safety. Why it matters: The market is digesting a steady stream of policy and regulatory headlines, but they haven’t sparked a clear reaction. Instead, they’re viewed as background noise or filed away as longer-term considerations with no immediate market impact.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Happy Birthday to the Bull Market 🎉
Quarterly Webinar: Q4 2026 Market and Economic Themes
Medicare Open Enrollment 2026: What to Know
Subscribe to Our Blog
Chief Investment Officer | Managing Partner