Alan Greenspan once said “since I’ve become a central banker, I have learned to mumble with great incoherence.” Greenspan, who passed away recently at the age of 100, served as the Chair of the Federal Reserve from 1987 to 2006 and became one of the most influential economic figures of the 20th century.1
As we reflect on his legacy just days after Kevin Warsh chaired his first Fed meeting, the parallels between the two leaders highlight several changes in how the Fed might operate in the coming years.
Connecting the Fed’s past with its future is helpful to understand how investors should view monetary policy going forward. Greenspan leaves a complex legacy bookended by a long period of stability after the inflation of the 1970s and early 1980s on the one hand, and the housing bubble and global financial crisis on the other. Throughout this timeline, it’s undeniable that he helped to define the role that the Fed still plays today.
Perhaps it’s not a coincidence that Warsh’s vision for the Fed echoes parts of Greenspan’s era, which favored less explicit communication, fewer policy hints or “forward guidance,” a smaller balance sheet, and a narrower focus on its core mandates. At the same time, it’s important to remember that the economy and markets have grown under different leaders at the Fed. This is because the Fed does not control many of the underlying drivers of the economy, such as technological innovation and demographic trends.
The economy has grown across many Fed chairs
It’s important to remember that the Fed has not always operated the way it does today. For much of Greenspan’s tenure, the central bank did not even announce its rate decisions publicly. Instead, the Fed effectively operated in secrecy, and markets were left to infer what had happened by watching short-term rates in money markets. When it did issue communications, the language was difficult to understand, something that economists refer to as “Fedspeak.”
It was not until 1994 that Greenspan introduced the practice of issuing a statement when rates changed, and even then, the statement was extremely brief with little explanation.2 As this practice started to take hold, the Fed started including language that partly explained its decision-making process based on the economic environment.
This continued to evolve over the next three decades. The Fed’s modern use of press conferences, dot plots, and forward guidance were developed under Ben Bernanke, Janet Yellen, and Jerome Powell. Many of these policies were driven by economic crises, including in 2008 and 2020, during which the Fed believed that communication was an important tool for restoring confidence in the financial system.
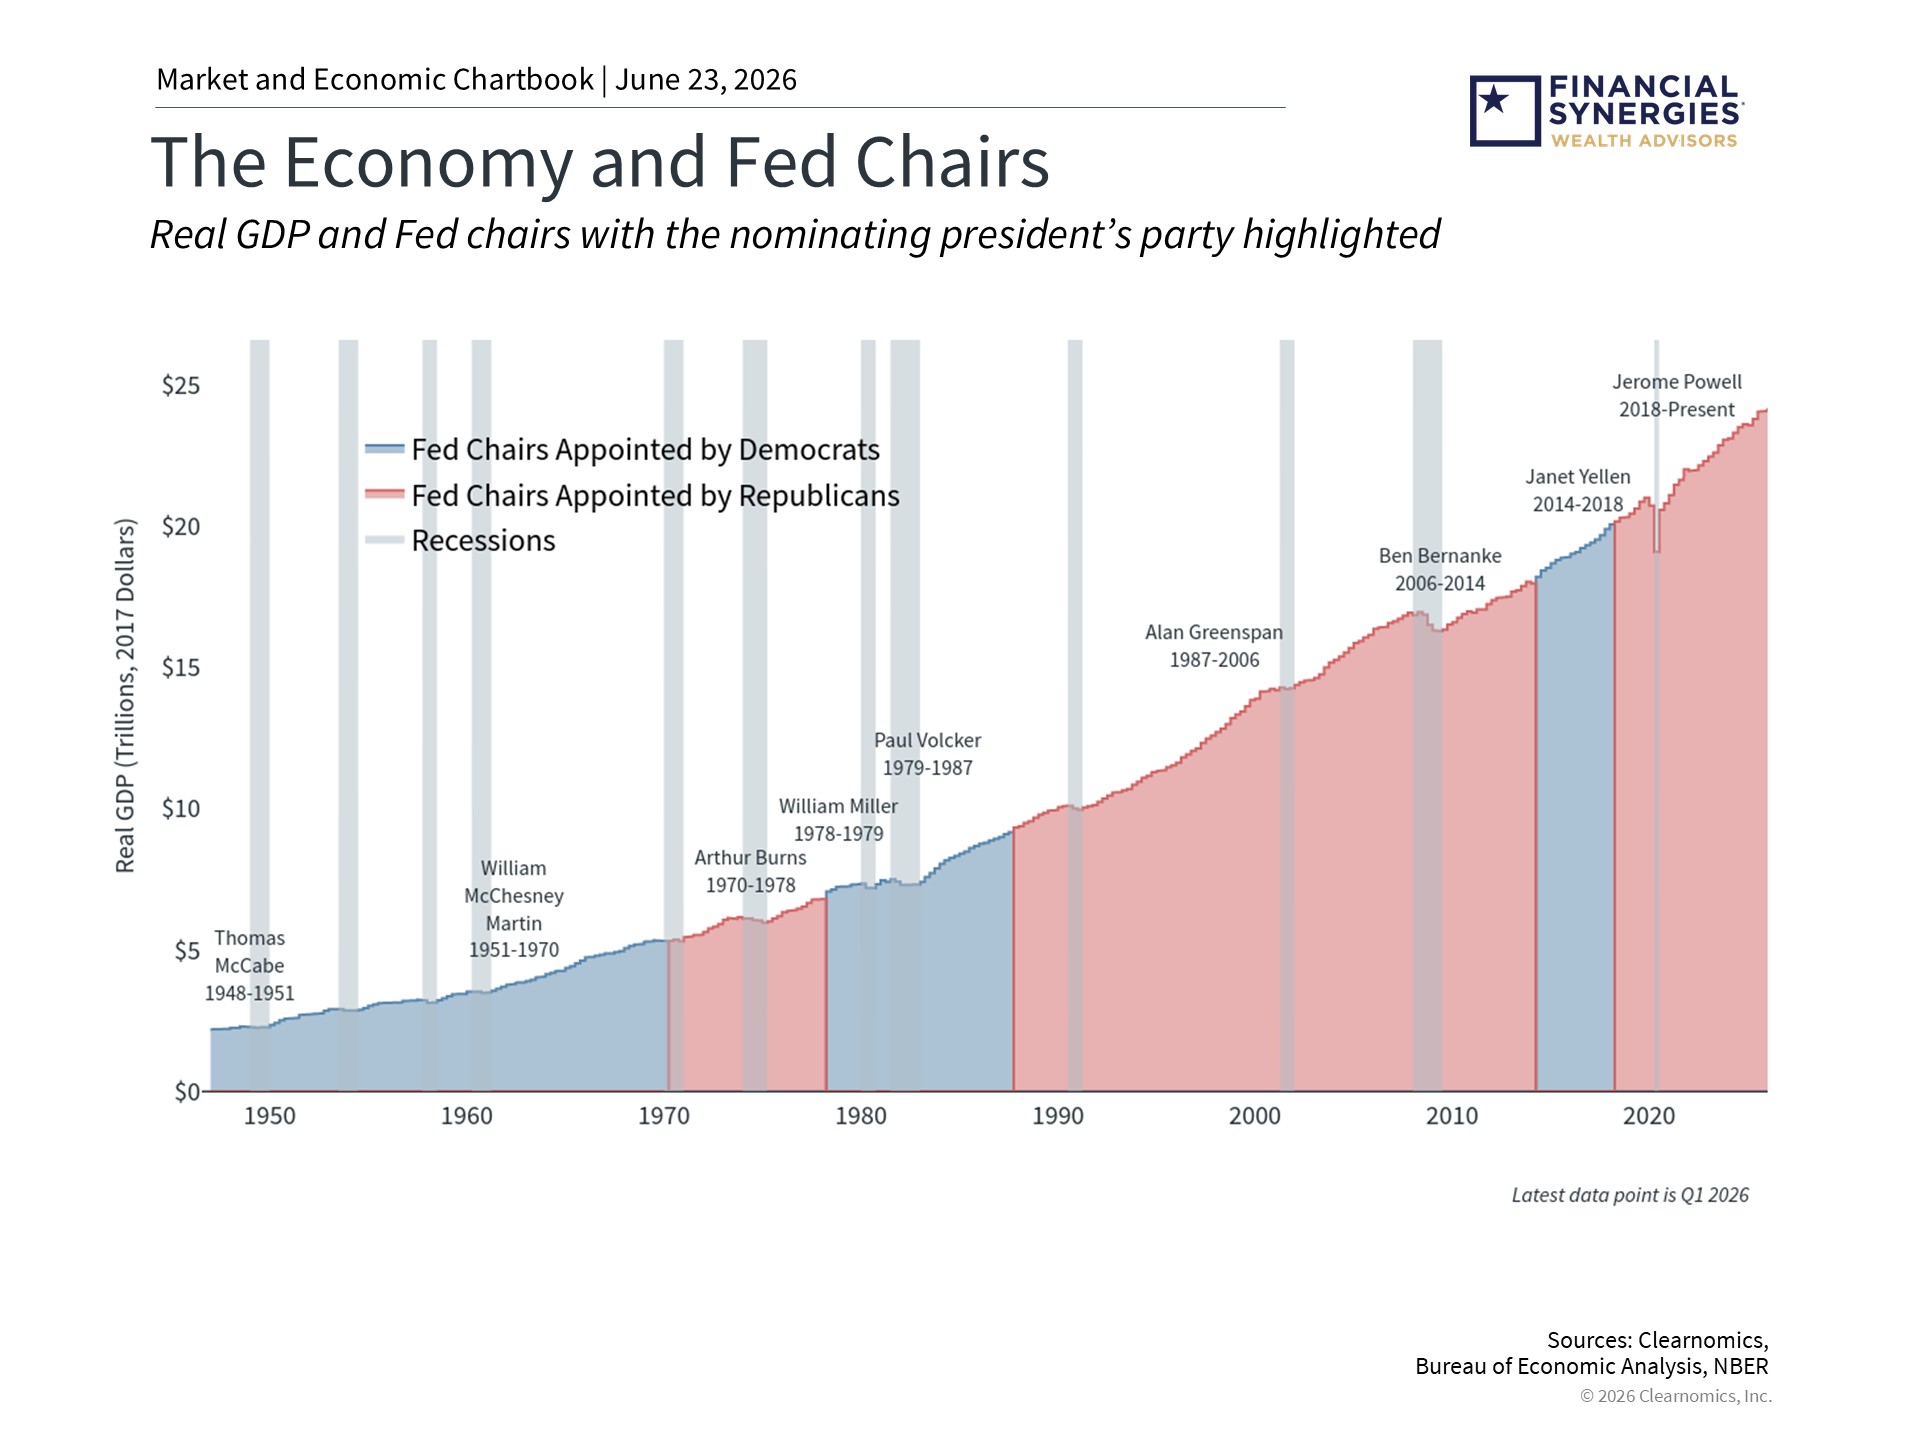
Despite the many differing views on how the Fed ought to operate, the accompanying chart above shows that the U.S. economy has grown across the tenures of many different Fed chairs, nominated by presidents of both parties. These Fed leaders each navigated unique economic challenges and set up the playbook for their successors. The economy continued to expand over long periods despite different approaches to monetary policy and different relationships with the White House.
Warsh’s approach marks a shift in communication
While the purpose of these communication changes was also to enhance transparency around how the Fed operates, Warsh and others have argued that the pendulum has swung too far in that direction. So, at his first FOMC meeting in June, Warsh made several changes. The Fed statement was significantly shortened, removing much of the language that has become boilerplate.3 Any “forward guidance,” meaning the practice of signaling what the Fed might do at future meetings, was removed. Warsh also declined to submit his own forecasts to the FOMC’s Summary of Economic Projections, a sign that he does not view these numbers as helpful.
Perhaps most importantly, Warsh announced five working groups to study different aspects of Fed operations and policymaking. These include communications, the data the Fed uses to assess the economy, its inflation framework, the impact of AI and technology, and the balance sheet. These are in line with Warsh’s previously published views on how the Fed should operate.
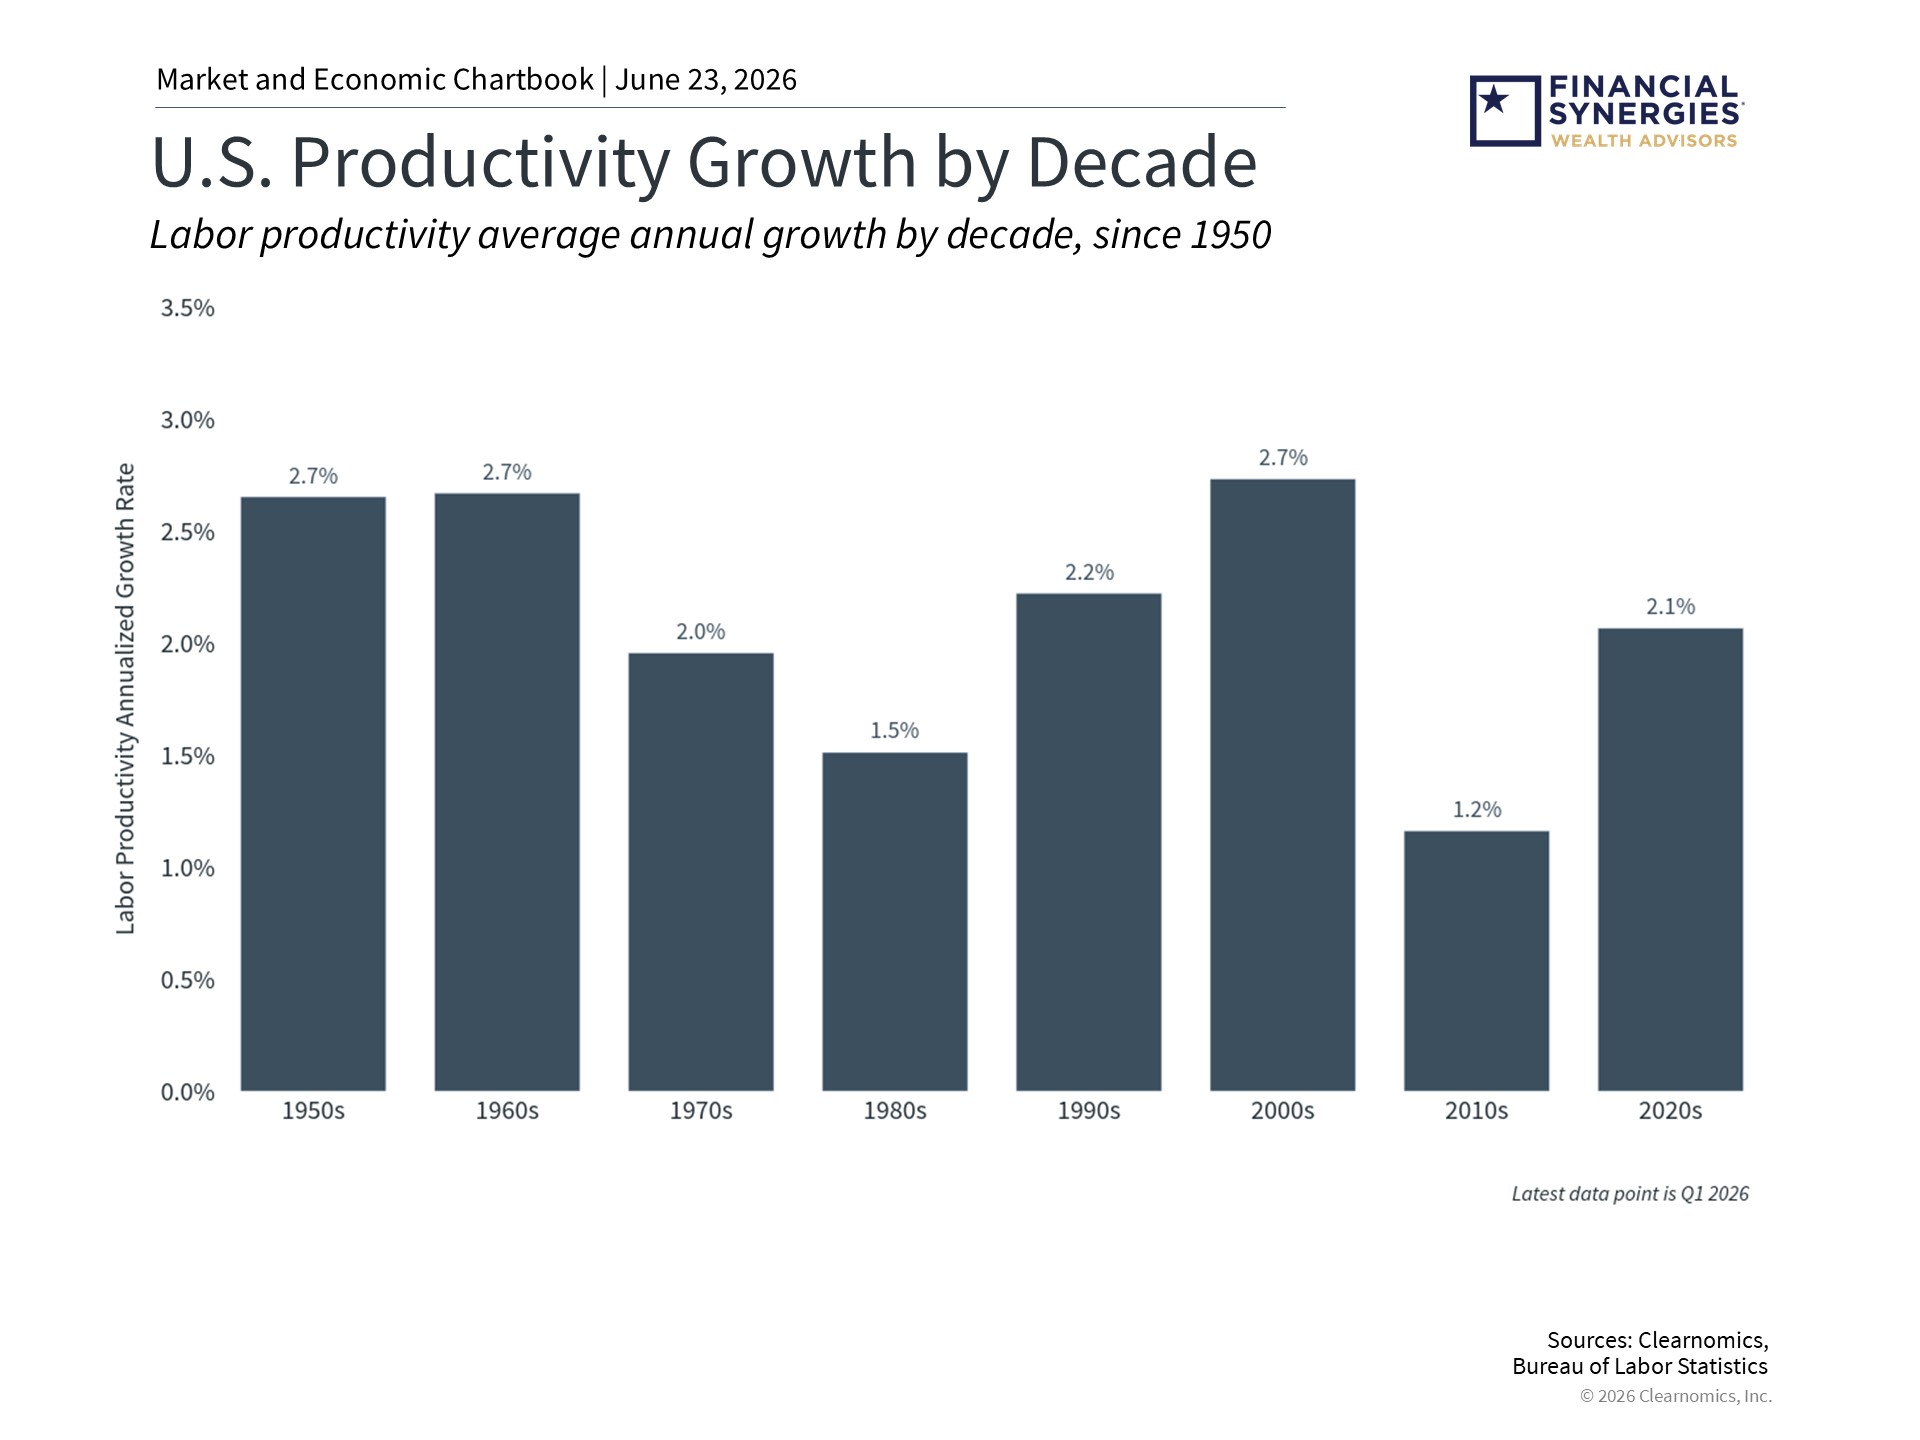
For long-term investors, perhaps the most interesting area is around productivity growth driven by AI. As the accompanying chart shows, productivity growth has been uneven across decades, with a notable acceleration during the technology-driven expansion of the 1990s. Productivity is very difficult to measure accurately in real-time, and even small changes can result in big differences to overall economic growth since they compound over time.
This matters because, in simple terms, productivity allows businesses to produce more with less labor. While much of the AI discussion is rightfully around jobs and disruption, in the long run, productivity is what allows wages and standards of living to increase. Technology can also help to keep inflation under control if it truly reduces the cost of producing goods and services.
Of course, this has significant implications for monetary policy. In the near term, the Fed has been managing a challenging period of inflation, and the ongoing war in Iran continues to create uncertainty around energy prices. The latest Fed rate projections show that the committee is divided, with roughly half expecting rates to remain at current levels by year-end and the other half expecting them to move higher.
The Fed’s balance sheet remains a focus
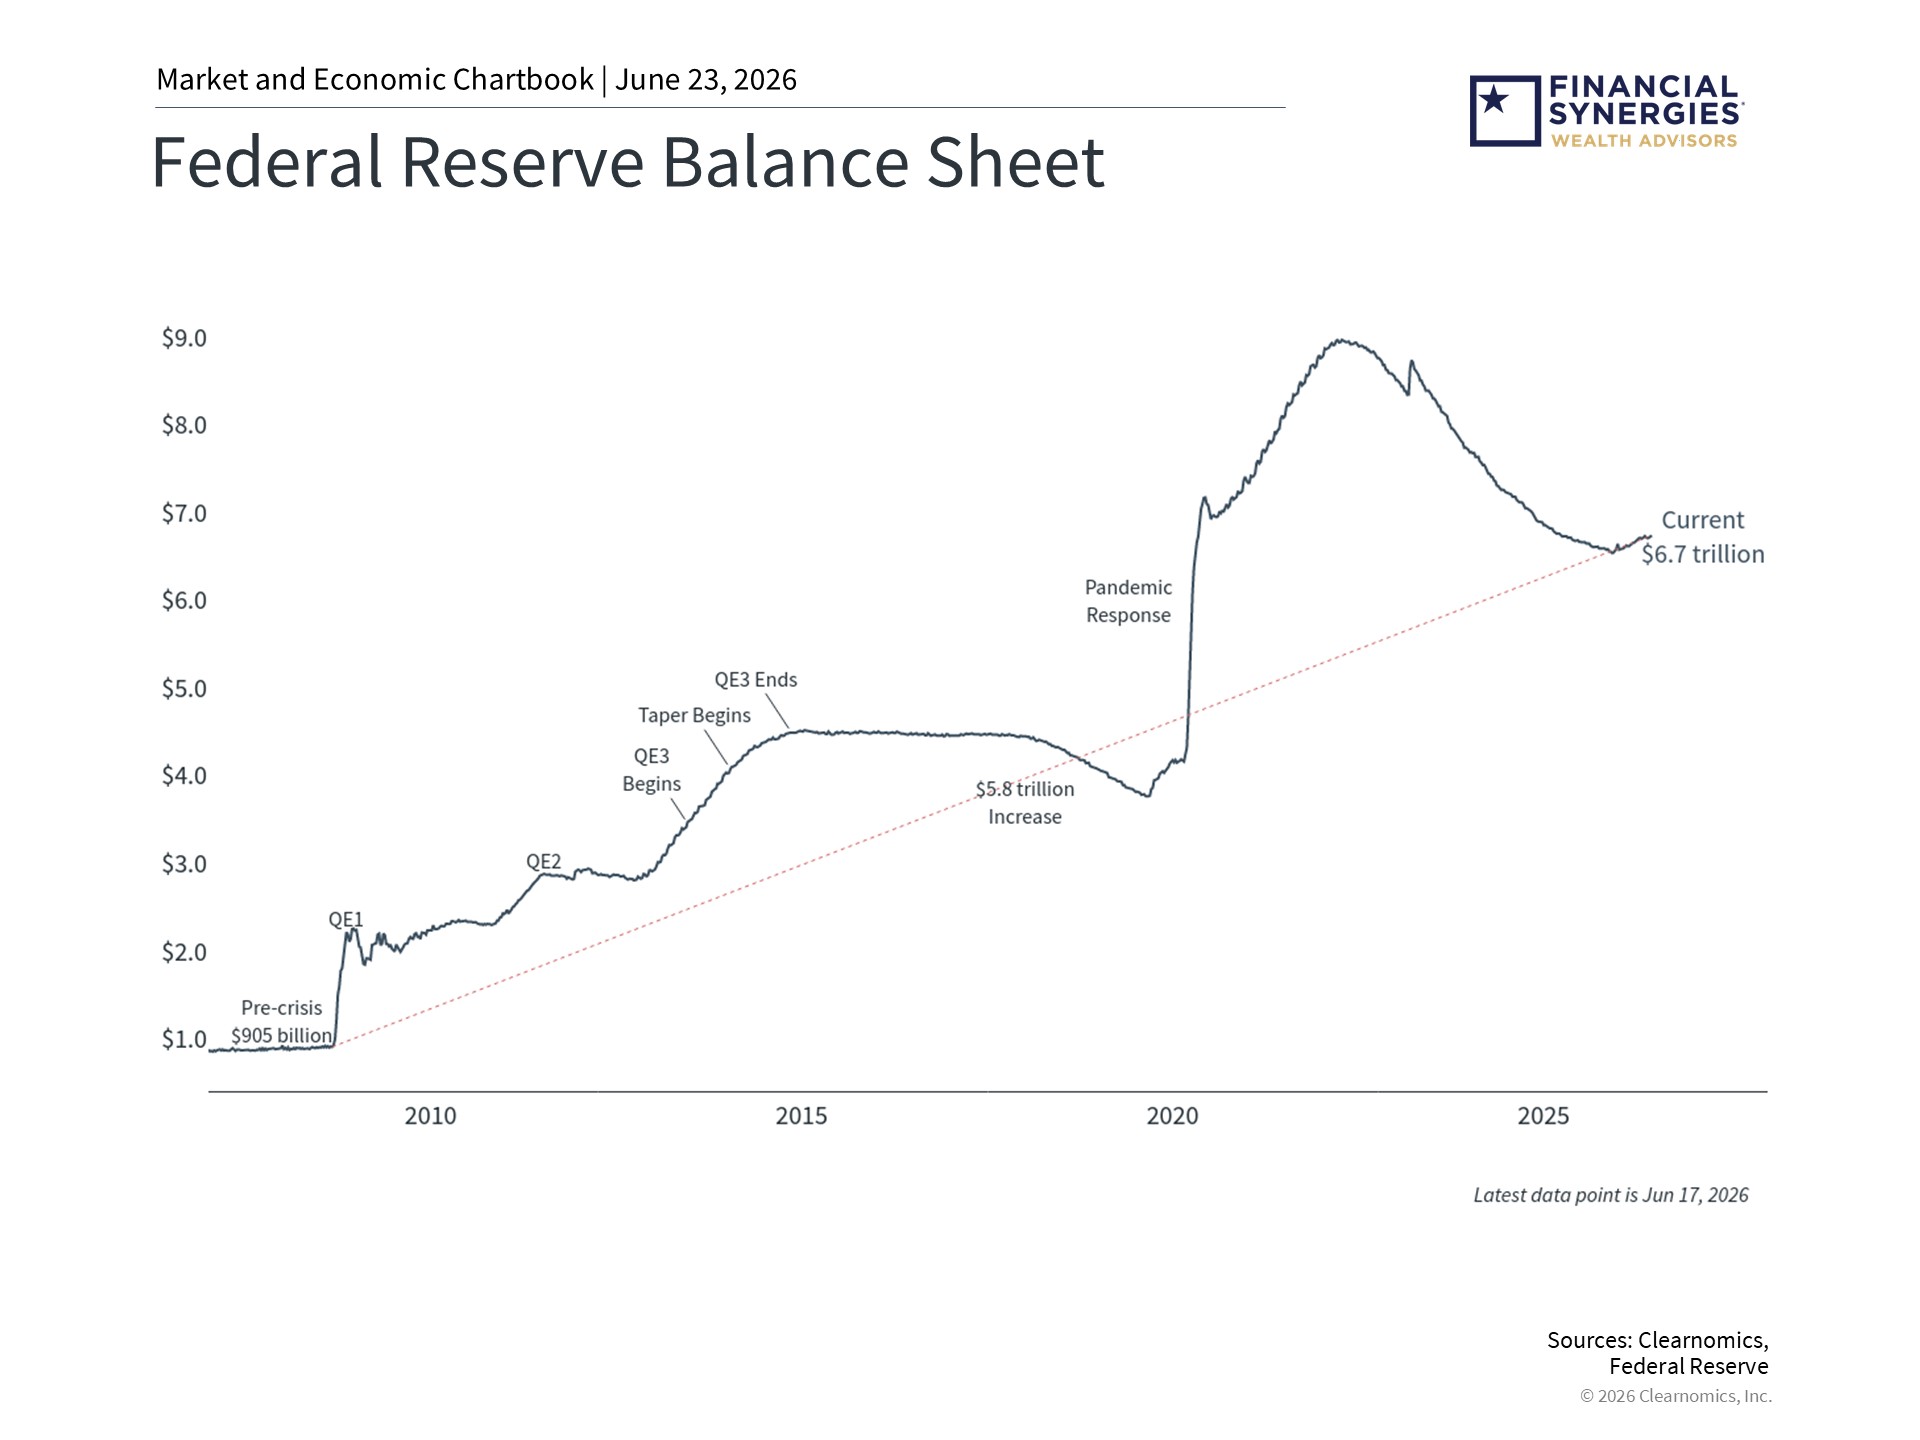
Interest rates are not the Fed’s only policy tool. As the accompanying chart shows, the Fed’s balance sheet stood at less than $1 trillion before the 2008 financial crisis, then expanded dramatically through several rounds of asset purchases. In times of crisis, the Fed has directly purchased bonds on the open market, primarily Treasurys and mortgage-backed securities. This provides liquidity to the financial system, effectively lowering interest rates, which is also why the Fed is sometimes known as the “lender of last resort.” Today, the balance sheet stands at $6.7 trillion, down from its peak of nearly $9 trillion in 2022.4
Warsh was a Fed governor during the financial crisis and supported these balance sheet expansions as emergency measures. However, he has also argued that the Fed should have been more deliberate about reversing this trend once conditions improved. Reducing the balance sheet, often called “quantitative tightening,” involves allowing securities to mature without reinvestment or, in some cases, actively selling assets.
How the Fed will change its communications, policymaking process, and balance sheet are not yet fully clear, but it’s possible that policy changes could lead to tighter financial conditions.5 For long-term investors, this could affect bond prices, mortgage rates, corporate borrowing costs, and more. The fact that the Fed may provide less guidance might create less “Fedspeak”, but could also create more uncertainty as to how the Fed might react to new developments.
The broader lesson is that the Fed’s approach to monetary policy is not static. It has evolved in response to economic conditions, new research, political considerations, and the judgment of individual chairs. For long-term investors, it’s important to remember that the Fed is only one part of the overall picture. The underlying trends driving the economy, many of which are positive today, are ultimately what allow portfolios to support financial plans.
References
1. https://www.federalreserve.gov/newsevents/pressreleases/other20260622a.htm
2. https://www.federalreserve.gov/fomc/19940204default.htm
3. https://www.federalreserve.gov/newsevents/pressreleases/monetary20260617a.htm
4. https://www.federalreserve.gov/monetarypolicy/bst_recenttrends.htm
5. https://www.federalreserve.gov/mediacenter/files/FOMCpresconf20260617.pdf
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Two Fed Eras: Greenspan’s Legacy and the Future Under Warsh
Alan Greenspan once said “since I’ve become a central banker, I have learned to mumble with great incoherence.” Greenspan, who passed away recently at the age of 100, served as the Chair of the Federal Reserve from 1987 to 2006 and became one of the most influential economic figures of the 20th century.1
As we reflect on his legacy just days after Kevin Warsh chaired his first Fed meeting, the parallels between the two leaders highlight several changes in how the Fed might operate in the coming years.
Connecting the Fed’s past with its future is helpful to understand how investors should view monetary policy going forward. Greenspan leaves a complex legacy bookended by a long period of stability after the inflation of the 1970s and early 1980s on the one hand, and the housing bubble and global financial crisis on the other. Throughout this timeline, it’s undeniable that he helped to define the role that the Fed still plays today.
Perhaps it’s not a coincidence that Warsh’s vision for the Fed echoes parts of Greenspan’s era, which favored less explicit communication, fewer policy hints or “forward guidance,” a smaller balance sheet, and a narrower focus on its core mandates. At the same time, it’s important to remember that the economy and markets have grown under different leaders at the Fed. This is because the Fed does not control many of the underlying drivers of the economy, such as technological innovation and demographic trends.
The economy has grown across many Fed chairs
It’s important to remember that the Fed has not always operated the way it does today. For much of Greenspan’s tenure, the central bank did not even announce its rate decisions publicly. Instead, the Fed effectively operated in secrecy, and markets were left to infer what had happened by watching short-term rates in money markets. When it did issue communications, the language was difficult to understand, something that economists refer to as “Fedspeak.”
It was not until 1994 that Greenspan introduced the practice of issuing a statement when rates changed, and even then, the statement was extremely brief with little explanation.2 As this practice started to take hold, the Fed started including language that partly explained its decision-making process based on the economic environment.
This continued to evolve over the next three decades. The Fed’s modern use of press conferences, dot plots, and forward guidance were developed under Ben Bernanke, Janet Yellen, and Jerome Powell. Many of these policies were driven by economic crises, including in 2008 and 2020, during which the Fed believed that communication was an important tool for restoring confidence in the financial system.
Despite the many differing views on how the Fed ought to operate, the accompanying chart above shows that the U.S. economy has grown across the tenures of many different Fed chairs, nominated by presidents of both parties. These Fed leaders each navigated unique economic challenges and set up the playbook for their successors. The economy continued to expand over long periods despite different approaches to monetary policy and different relationships with the White House.
Warsh’s approach marks a shift in communication
While the purpose of these communication changes was also to enhance transparency around how the Fed operates, Warsh and others have argued that the pendulum has swung too far in that direction. So, at his first FOMC meeting in June, Warsh made several changes. The Fed statement was significantly shortened, removing much of the language that has become boilerplate.3 Any “forward guidance,” meaning the practice of signaling what the Fed might do at future meetings, was removed. Warsh also declined to submit his own forecasts to the FOMC’s Summary of Economic Projections, a sign that he does not view these numbers as helpful.
Perhaps most importantly, Warsh announced five working groups to study different aspects of Fed operations and policymaking. These include communications, the data the Fed uses to assess the economy, its inflation framework, the impact of AI and technology, and the balance sheet. These are in line with Warsh’s previously published views on how the Fed should operate.
For long-term investors, perhaps the most interesting area is around productivity growth driven by AI. As the accompanying chart shows, productivity growth has been uneven across decades, with a notable acceleration during the technology-driven expansion of the 1990s. Productivity is very difficult to measure accurately in real-time, and even small changes can result in big differences to overall economic growth since they compound over time.
This matters because, in simple terms, productivity allows businesses to produce more with less labor. While much of the AI discussion is rightfully around jobs and disruption, in the long run, productivity is what allows wages and standards of living to increase. Technology can also help to keep inflation under control if it truly reduces the cost of producing goods and services.
Of course, this has significant implications for monetary policy. In the near term, the Fed has been managing a challenging period of inflation, and the ongoing war in Iran continues to create uncertainty around energy prices. The latest Fed rate projections show that the committee is divided, with roughly half expecting rates to remain at current levels by year-end and the other half expecting them to move higher.
The Fed’s balance sheet remains a focus
Interest rates are not the Fed’s only policy tool. As the accompanying chart shows, the Fed’s balance sheet stood at less than $1 trillion before the 2008 financial crisis, then expanded dramatically through several rounds of asset purchases. In times of crisis, the Fed has directly purchased bonds on the open market, primarily Treasurys and mortgage-backed securities. This provides liquidity to the financial system, effectively lowering interest rates, which is also why the Fed is sometimes known as the “lender of last resort.” Today, the balance sheet stands at $6.7 trillion, down from its peak of nearly $9 trillion in 2022.4
Warsh was a Fed governor during the financial crisis and supported these balance sheet expansions as emergency measures. However, he has also argued that the Fed should have been more deliberate about reversing this trend once conditions improved. Reducing the balance sheet, often called “quantitative tightening,” involves allowing securities to mature without reinvestment or, in some cases, actively selling assets.
How the Fed will change its communications, policymaking process, and balance sheet are not yet fully clear, but it’s possible that policy changes could lead to tighter financial conditions.5 For long-term investors, this could affect bond prices, mortgage rates, corporate borrowing costs, and more. The fact that the Fed may provide less guidance might create less “Fedspeak”, but could also create more uncertainty as to how the Fed might react to new developments.
The broader lesson is that the Fed’s approach to monetary policy is not static. It has evolved in response to economic conditions, new research, political considerations, and the judgment of individual chairs. For long-term investors, it’s important to remember that the Fed is only one part of the overall picture. The underlying trends driving the economy, many of which are positive today, are ultimately what allow portfolios to support financial plans.
References
1. https://www.federalreserve.gov/newsevents/pressreleases/other20260622a.htm
2. https://www.federalreserve.gov/fomc/19940204default.htm
3. https://www.federalreserve.gov/newsevents/pressreleases/monetary20260617a.htm
4. https://www.federalreserve.gov/monetarypolicy/bst_recenttrends.htm
5. https://www.federalreserve.gov/mediacenter/files/FOMCpresconf20260617.pdf
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Retirement Income Risks: Planning for a Longer Life
What 7% Mortgages Mean for Housing and the Economy
Financial Synergies Named One of the Fastest Growing Private Companies in Houston
Subscribe to Our Blog
Chief Investment Officer | Managing Partner