Skip to content

Key Highlights of Trump Accounts
- Trump Accounts offer a new way to build generational wealth, including a $1,000 government contribution for eligible children.
- Starting early can make a lasting difference. Compound growth can help even modest investments build wealth over time.
- Choosing the right savings strategy matters. Trump Accounts, 529 plans, custodial Roth IRAs, and UGMA/UTMA accounts offer different benefits.
- Tax-efficient planning can maximize family wealth. Strategies such as 529 superfunding and strategic gifting may help optimize long-term savings.
- A holistic financial plan is essential. Combining savings vehicles can help families balance education funding, retirement savings, and generational wealth transfer.
A famous quote by Warren Buffett is that “someone’s sitting in the shade today because someone planted a tree a long time ago.” For many parents and guardians, the goal of saving, investing, and planning is to ensure the financial security of their family.
Alongside the day-to-day costs associated with raising children, parents must prepare for large expenses such as childcare, healthcare, and education, as well as ensuring the children are protected in case of an unforeseen event. With proper planning, parents can not only manage the costs of raising and protecting children, but also set them up for future financial success by utilizing different savings opportunities.
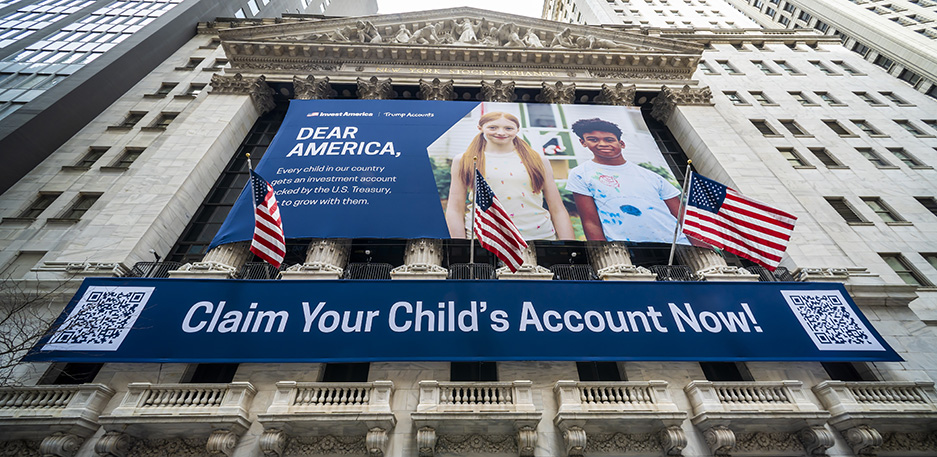
The number of ways to save for children has expanded with the creation of 530A accounts by last year’s One Big Beautiful Bill Act, which are commonly referred to as “Trump Accounts.” These savings vehicles provide families with more ways to build wealth across generations, but require consideration for how they are prioritized and interact as part of a holistic financial plan.
Trump Accounts Are the Newest Planning Tool for Children
The goal of these accounts is to give children a head start toward retirement savings in a tax-efficient manner, along with a government-funded contribution. They are effectively an individual retirement account (IRA) geared toward children. According to the Treasury Department, six million children are already signed up for Trump Accounts, with 1.4 million eligible for the $1,000 pilot program contribution.1 As with any new investment vehicle, it’s important to first understand the rules before considering how it can be used to support a child’s financial future.
Some key criteria for evaluating 530A accounts are:
- If a child qualifies, the initial seed-grant of $1,000 provides motivation to start saving early. Currently, children qualify if they are born between January 1, 2025 and December 31, 2028, who are U.S. citizens and have a valid Social Security Number.
- There are no earned income requirements to make contributions for a child. This creates an alternative for long-term savings that aren’t earmarked for education purposes.
- Investment options are simplified for parents and currently include a set of low-cost, U.S. equity index funds. New legislation would be required to change or expand these investment options in the future.
- Funds are unavailable for withdrawals until the child turns 18 so they’re not available to pay for K-12 education purposes.
- Withdrawals after 18 are subject to general IRA rules with 10% penalties for early withdrawals that don’t meet a qualifying reason.
- Authorized contributions from individuals and employers are allowed up to an aggregate $5,000 per year, with employers able to contribute up to $2,500 per year without that amount counting as taxable income for the employee.
It’s helpful to think of 530A accounts as vehicles that complement, rather than substitute, other savings options. After all, the most effective financial strategy is rarely built around a single investment account.
Key Investment Tools When Planning for Children
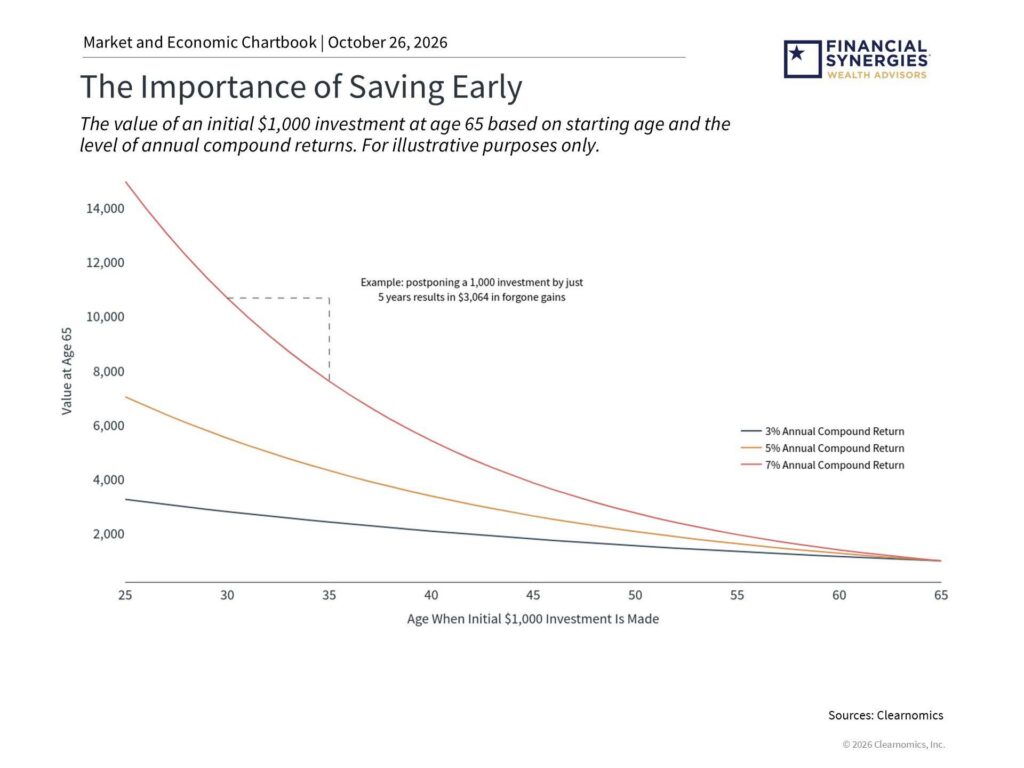
There are many child savings accounts that have become a key component of financial plans. According to data from Congress, the number of children with savings accounts rose from 1.2 million in 2021 to 5.8 million in 2023.2 The chart above shows the impact of saving even just a few years earlier.3
There are multiple ways to save for your children’s future, depending on individual circumstances, goals, and liquidity needs. Some of the most popular savings accounts are 529 accounts, custodial Roth IRAs, Uniform Gifts to Minors Act (UGMA) or Uniform Transfers to Minor Act (UTMA) accounts. All of these have different rules for contributions, withdrawals, and taxation considerations. Some important features of these accounts include the following.
529 Plans
Parents or grandparents typically open these accounts to save for future education expenses. Contributions are after-tax, and withdrawals are federally tax-free when used for qualified education expenses. There are no limits to contributions, but they are subject to annual gifting limits.
Custodial Roth IRA
These accounts are held in the minor’s name and geared toward retirement savings. Contributions are after-tax, and withdrawals are tax-free if conditions are met. One key difference, particularly with Trump Accounts, is that earned income is required to make contributions and the annual limit is $7,500 in 2026.
UGMA/UTMA Accounts
These accounts are also owned by the minor but managed by an adult custodian until the child reaches legal age. Its primary purpose is gifting and inheritance. No earned income is required, and contributions are after-tax and are subject to annual gifting limits.
Considerations for Maximizing Savings for Children
There are various strategies that families can use to maximize savings while being mindful of taxes and contribution thresholds. One approach involves making use of a provision in the tax code that allows donors to front-load multiple years of annual gift tax exclusions into a single contribution to a 529 education savings account. This is commonly referred to as “superfunding.”
For example, individuals are allowed to contribute a lump sum to a child’s 529 account of up to $95,000 per beneficiary in a single year without triggering a gift tax. This is because the contribution is treated as if it were spread evenly over five years, meaning no additional gifts can be made to that beneficiary from the same donor during that period without potential gift tax implications. An important note to remember is that parent-owned 529s are not calculated as student assets for financial aid eligibility.
Another strategy is to use UTMAs to transfer highly appreciated securities. Depending on the parents’ income level, strategically gifting these securities and selling them as long-term gains in an UTMA may avoid capital gains taxes. However, a consideration is that these accounts count towards a student’s assets which are weighed more heavily in the calculation for federal student aid eligibility.
One pitfall to avoid is failing to account for “kiddie tax” which is applicable to children’s unearned income, exempt to a certain threshold. An investment below the threshold is taxed at the child’s marginal rate while the above-threshold amount is taxed at the parent’s marginal rate. This would apply to any earnings from an UTMA or distributions from the Trump Accounts.
The Importance of Compound Growth and Market Returns
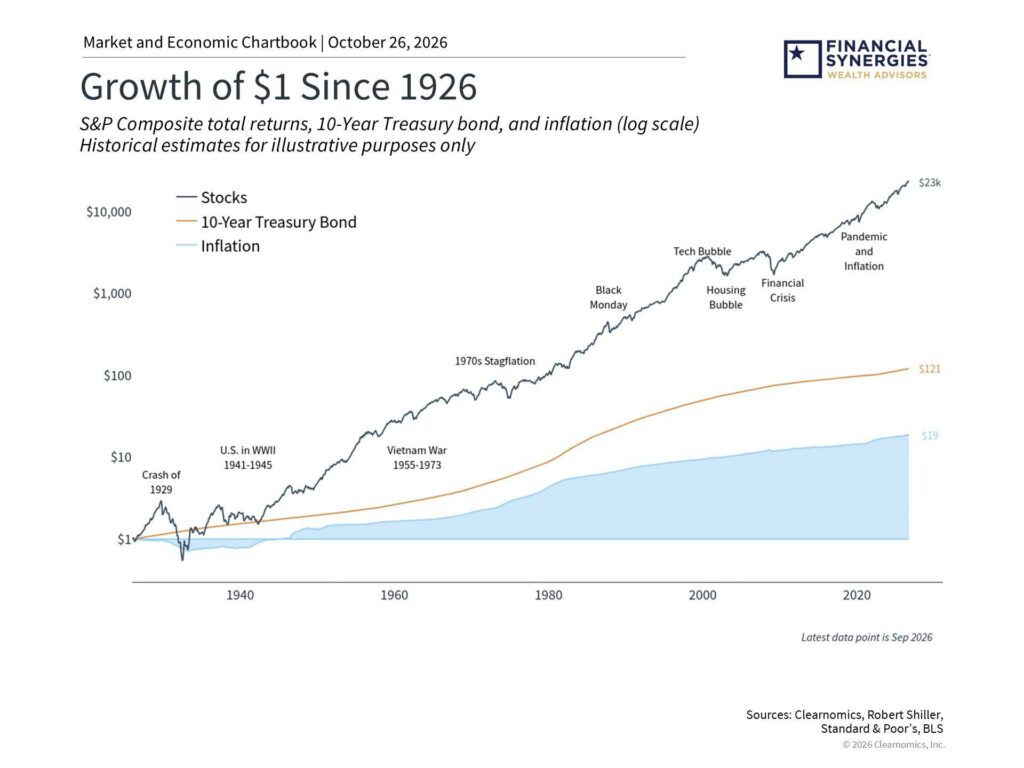
Historically, even a relatively small amount invested at birth can benefit from compound interest over a long time horizon. This is why one of the key principles of investing is to start as soon as possible to give your money time to grow. The accompanying chart shows the history of compound growth of $1 when invested in stocks and bonds over a long-term period.
Teaching children about the importance of saving money and investing early can help them become more financially responsible when they get older. Helping them further with these savings and investment accounts early, as part of a holistic financial plan, allows them to benefit from compound growth later in life.
Bottom line? By planning ahead, parents can build a strong financial foundation for their children’s futures by utilizing savings strategies and appropriate vehicles.
References for Trump Accounts
- https://home.treasury.gov/news/press-releases/sb0552
- https://www.congress.gov/crs-product/R48554
- Clearnomics research based on historical market returns.
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries. The modern design of the S&P 500 stock index was first launched in 1957. Performance prior to 1957 incorporates the performance of the predecessor index, the S&P 90.
Frequently Asked Questions
What are Trump Accounts (530A accounts), and how do they work?
Trump Accounts are tax-advantaged investment accounts designed to help children build long-term retirement savings. Eligible children may receive a $1,000 government contribution, with additional contributions permitted from individuals and employers.
How do Trump Accounts compare to 529 college savings plans?
Trump Accounts focus on long-term retirement savings, while 529 plans offer tax advantages for qualified education expenses. Both can play complementary roles in a family’s financial planning strategy.
What are the best ways to save and invest for a child’s future?
Popular options include 529 college savings plans, Trump Accounts, custodial Roth IRAs, and UGMA/UTMA accounts. The right combination depends on your family’s financial goals, tax considerations, and investment timeline.
How can high-net-worth families maximize tax-efficient wealth transfers to children?
Strategies such as 529 plan superfunding, custodial investment accounts, and early investing can help families transfer wealth efficiently while taking advantage of potential tax benefits and long-term compound growth.
A Truly Unique Wealth Management Experience
Let’s create a financial plan and investment strategy that allows you to live the life of your dreams. Schedule your free consultation today to explore tailored financial strategies designed to secure your future!
Concerns or questions about your tax situation or financial plan? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management, financial planning, and retirement planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.