Monthly Market Update: Market Leadership Broadens as Rotation Continues
👉 For your convenience, we’ve also provided a PDF copy of the Monthly Market Update: Market Leadership Broadens as Rotation Continues.
Monthly Market Summary
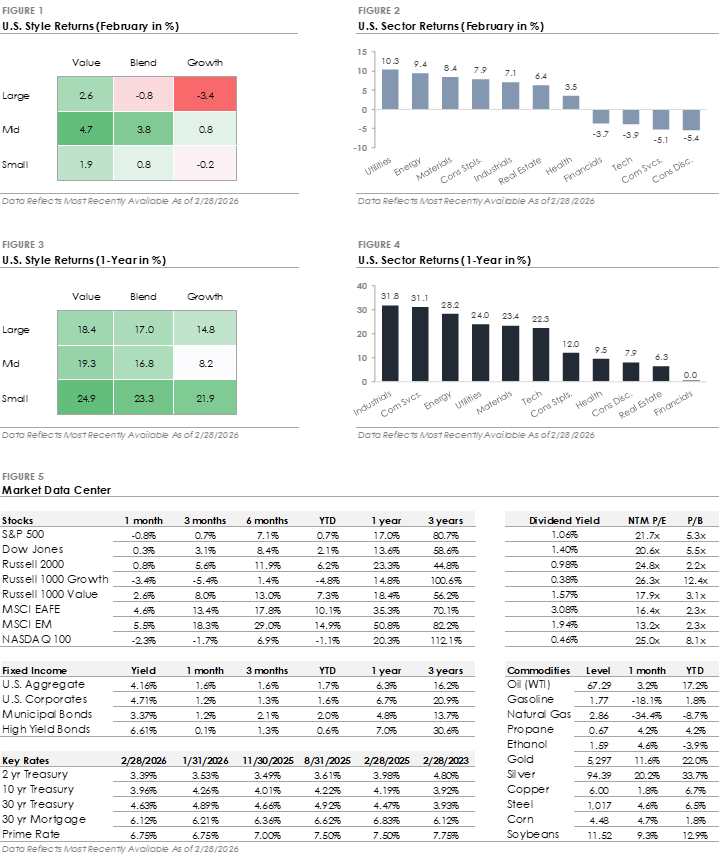
- The S&P 500 Index declined -0.8% in February, but the headline masked broad underlying strength. The equal-weighted S&P 500 gained +3.5%, Large Cap Value rose +2.6%, and the Russell 2000 added +0.8%, as the rotation toward smaller and more value-oriented companies continued. In contrast, Large Cap Growth declined -3.4% and the Nasdaq fell -2.3% as technology stocks came under pressure.
- Utilities led all S&P 500 sectors with a +10.3% return, followed by Energy (+9.4%), Materials (+8.4%), Consumer Staples (+7.9%), and Industrials (+7.1%). Seven sectors outperformed the index, while the remaining four underperformed.
- Bonds traded higher as Treasury yields declined, with the U.S. Bond Aggregate returning +1.6%. Corporate bonds traded higher, with investment-grade outperforming high-yield, but underperformed as credit spreads widened.
- International stocks outperformed the S&P 500 for a third consecutive month, with Developed Markets gaining +4.6% and Emerging Markets returning +5.5%.
Market Leadership Continues to Broaden Amid Questions About AI’s Impact
The rotation away from mega-cap tech stocks that started in January extended into February. While the S&P 500 traded lower, the average stock, as measured by the equal-weighted index, gained over +3%. The rotation was broad-based: small caps outperformed large caps, value beat growth, seven of eleven sectors beat the S&P 500, and international stocks outpaced U.S. stocks.
“Market leadership is broadening after a long period in which a small group of mega-cap tech stocks drove most of the market’s gains, and diversified portfolios are benefiting from the rotation.”
The technology sector’s weakness was tied to concerns that artificial intelligence will impact, and potentially disrupt, current business models. A wave of AI product launches caused investors to rethink not only the potential winners, but also which industries could face disruption, such as software, consulting, real estate services, freight brokers, and other industries where AI capabilities are advancing rapidly.
The selling and volatility were most pronounced early in the month but later stabilized as the narrative shifted toward a more balanced view of AI as a tool that enhances existing businesses rather than replaces them. The disruption fears eased into month-end, but investors are likely to remain focused on AI’s impact on industries beyond technology.
Bonds & Gold Trade Higher as Investors Seek Stability
February was a strong month for bonds, as the 10-year Treasury yield fell nearly -0.30% to end the month below 4.00%, the lowest since October. The decline in Treasury yields drove the bond market rally, with longer-maturity and higher-quality bonds outperforming as investors sought stability amid tech sector volatility, trade policy uncertainty tied to the Supreme Court’s tariff ruling, and rising geopolitical tensions with Iran. Long-duration Treasuries gained +4.1%, and mortgage-backed securities returned +1.6%, both outperforming the broad U.S. Bond Aggregate Index.
The bond rally is notable because it occurred even as expectations for interest rate cuts were pushed further out. The Federal Reserve held interest rates steady at its January meeting after cutting in December, and the market doesn’t expect the next rate cut until June, at the earliest. The distinction is important: falling Treasury yields reflected investor demand for lower volatility assets amid the tech sector sell-off and geopolitical tensions, not a signal that economic conditions are deteriorating. Gold gained more than +10% in February, reflecting the same demand for portfolio protection.
Minutes from the Fed’s January meeting signaled a continued focus on controlling inflation, and the economic data supports the Fed’s patience. The labor market added +130,000 jobs in January, the unemployment rate declined to 4.3%, and an index of manufacturing activity crossed back into expansion for the first time in nearly a year. Inflation continues to ease, with core CPI rising at a +2.5% annual rate, the slowest since early 2021. The combination of steady growth and cooling inflation gives the Fed room to remain on hold. While the market still expects the Fed to cut twice this year, the start date keeps drifting later.
Where Markets Stand Today
February was a busy month filled with AI headlines, shifting market leadership, and policy uncertainty. But beneath the surface, the economic backdrop remains stable, and the Federal Reserve remains patient. As leadership broadens beyond a narrow group of mega-cap stocks, diversified portfolios are beginning to benefit from a healthier market structure.
Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Stock performance and fundamental data is based on the following instruments: SPDR S&P 500 ETF (SPY), SPDR Dow Jones ETF (DIA), iShares Russell 2000 ETF (IWM), iShares Russell 1000 Growth ETF (IWF), iShares Russell 1000 Value ETF (IWD), iShares MSCI EAFE ETF (EFA), iShares MSCI Emerging Markets ETF (EEM), Invesco QQQ Trust (QQQ).
Fixed Income performance is based on the following instruments: iShares Core U.S. Aggregate Bond ETF (AGG), iShares Investment Grade Corporate ETF (LQD), iShares National Muni Bond ETF (MUB), iShares High Yield Corporate ETF (HYG).
Fixed Income yields and key rates are based on the following instruments: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Benchmark Bond, 10 Year US Benchmark Bond, 30 Year US Benchmark Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate.
Commodity prices are based on the following instruments: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).
U.S. Style performance is based on the following instruments: iShares Russell 1000 Value ETF (IWD), SPDR S&P 500 ETF Trust (SPY), iShares Russell 1000 Growth ETF (IWF), iShares Russell Mid-Cap Value ETF (IWS), iShares Russell Midcap ETF (IWR), iShares Russell Mid-Cap Growth ETF (IWP), iShares Russell 2000 Value ETF (IWN), iShares Russell 2000 ETF (IWM), iShares Russell 2000 Growth ETF (IWO).
U.S. Sector performance is based on the following instruments: Consumer Discretionary Sector SPDR ETF (XLY), Consumer Staples Sector SPDR ETF (XLP), Energy Sector SPDR ETF (XLE), Financial Sector SPDR ETF (XLF), Health Care Sector SPDR ETF (XLV), Industrial Sector SPDR ETF (XLI), Materials Sector SPDR ETF (XLB), Technology Sector SPDR ETF (XLK), Communication Services Sector SPDR ETF (XLC), Utilities Sector SPDR ETF (XLU), Real Estate Sector SPDR ETF (XLRE).
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Monthly Market Update: Market Leadership Broadens as Rotation Continues
Monthly Market Update: Market Leadership Broadens as Rotation Continues
👉 For your convenience, we’ve also provided a PDF copy of the Monthly Market Update: Market Leadership Broadens as Rotation Continues.
Monthly Market Summary
Market Leadership Continues to Broaden Amid Questions About AI’s Impact
The rotation away from mega-cap tech stocks that started in January extended into February. While the S&P 500 traded lower, the average stock, as measured by the equal-weighted index, gained over +3%. The rotation was broad-based: small caps outperformed large caps, value beat growth, seven of eleven sectors beat the S&P 500, and international stocks outpaced U.S. stocks.
The technology sector’s weakness was tied to concerns that artificial intelligence will impact, and potentially disrupt, current business models. A wave of AI product launches caused investors to rethink not only the potential winners, but also which industries could face disruption, such as software, consulting, real estate services, freight brokers, and other industries where AI capabilities are advancing rapidly.
The selling and volatility were most pronounced early in the month but later stabilized as the narrative shifted toward a more balanced view of AI as a tool that enhances existing businesses rather than replaces them. The disruption fears eased into month-end, but investors are likely to remain focused on AI’s impact on industries beyond technology.
Bonds & Gold Trade Higher as Investors Seek Stability
February was a strong month for bonds, as the 10-year Treasury yield fell nearly -0.30% to end the month below 4.00%, the lowest since October. The decline in Treasury yields drove the bond market rally, with longer-maturity and higher-quality bonds outperforming as investors sought stability amid tech sector volatility, trade policy uncertainty tied to the Supreme Court’s tariff ruling, and rising geopolitical tensions with Iran. Long-duration Treasuries gained +4.1%, and mortgage-backed securities returned +1.6%, both outperforming the broad U.S. Bond Aggregate Index.
The bond rally is notable because it occurred even as expectations for interest rate cuts were pushed further out. The Federal Reserve held interest rates steady at its January meeting after cutting in December, and the market doesn’t expect the next rate cut until June, at the earliest. The distinction is important: falling Treasury yields reflected investor demand for lower volatility assets amid the tech sector sell-off and geopolitical tensions, not a signal that economic conditions are deteriorating. Gold gained more than +10% in February, reflecting the same demand for portfolio protection.
Minutes from the Fed’s January meeting signaled a continued focus on controlling inflation, and the economic data supports the Fed’s patience. The labor market added +130,000 jobs in January, the unemployment rate declined to 4.3%, and an index of manufacturing activity crossed back into expansion for the first time in nearly a year. Inflation continues to ease, with core CPI rising at a +2.5% annual rate, the slowest since early 2021. The combination of steady growth and cooling inflation gives the Fed room to remain on hold. While the market still expects the Fed to cut twice this year, the start date keeps drifting later.
Where Markets Stand Today
February was a busy month filled with AI headlines, shifting market leadership, and policy uncertainty. But beneath the surface, the economic backdrop remains stable, and the Federal Reserve remains patient. As leadership broadens beyond a narrow group of mega-cap stocks, diversified portfolios are beginning to benefit from a healthier market structure.
Disclosures
The information and opinions provided herein are provided as general market commentary only and are subject to change at any time without notice. This commentary may contain forward-looking statements that are subject to various risks and uncertainties. None of the events or outcomes mentioned here may come to pass, and actual results may differ materially from those expressed or implied in these statements. No mention of a particular security, index, or other instrument in this report constitutes a recommendation to buy, sell, or hold that or any other security, nor does it constitute an opinion on the suitability of any security or index. The report is strictly an informational publication and has been prepared without regard to the particular investments and circumstances of the recipient.
Past performance does not guarantee or indicate future results. Any index performance mentioned is for illustrative purposes only and does not reflect any management fees, transaction costs, or expenses. Indexes are unmanaged, and one cannot invest directly in an index. Index performance does not represent the actual performance that would be achieved by investing in a fund.
Stock performance and fundamental data is based on the following instruments: SPDR S&P 500 ETF (SPY), SPDR Dow Jones ETF (DIA), iShares Russell 2000 ETF (IWM), iShares Russell 1000 Growth ETF (IWF), iShares Russell 1000 Value ETF (IWD), iShares MSCI EAFE ETF (EFA), iShares MSCI Emerging Markets ETF (EEM), Invesco QQQ Trust (QQQ).
Fixed Income performance is based on the following instruments: iShares Core U.S. Aggregate Bond ETF (AGG), iShares Investment Grade Corporate ETF (LQD), iShares National Muni Bond ETF (MUB), iShares High Yield Corporate ETF (HYG).
Fixed Income yields and key rates are based on the following instruments: Bloomberg US Aggregate, ICE BofA US Corporate, ICE BofA US Municipal Securities, ICE BofA US High Yield, 2 Year US Benchmark Bond, 10 Year US Benchmark Bond, 30 Year US Benchmark Bond, 30 Year US Fixed Mortgage Rate, US Prime Rate.
Commodity prices are based on the following instruments: Crude Oil WTI (NYM $/bbl), Gasoline Regular U.S. Gulf Coast ($/gal), Natural Gas (NYM $/mmbtu), Propane (NYM $/gal), Ethanol (CRB $/gallon), Gold (NYM $/ozt), Silver (NYM $/ozt), Copper NYMEX ($/lb), U.S. Midwest Domestic Hot-Rolled Coil Steel (NYM $/st), Corn (CBT $/bu), Soybeans (Chicago $/bu).
U.S. Style performance is based on the following instruments: iShares Russell 1000 Value ETF (IWD), SPDR S&P 500 ETF Trust (SPY), iShares Russell 1000 Growth ETF (IWF), iShares Russell Mid-Cap Value ETF (IWS), iShares Russell Midcap ETF (IWR), iShares Russell Mid-Cap Growth ETF (IWP), iShares Russell 2000 Value ETF (IWN), iShares Russell 2000 ETF (IWM), iShares Russell 2000 Growth ETF (IWO).
U.S. Sector performance is based on the following instruments: Consumer Discretionary Sector SPDR ETF (XLY), Consumer Staples Sector SPDR ETF (XLP), Energy Sector SPDR ETF (XLE), Financial Sector SPDR ETF (XLF), Health Care Sector SPDR ETF (XLV), Industrial Sector SPDR ETF (XLI), Materials Sector SPDR ETF (XLB), Technology Sector SPDR ETF (XLK), Communication Services Sector SPDR ETF (XLC), Utilities Sector SPDR ETF (XLU), Real Estate Sector SPDR ETF (XLRE).
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Happy Birthday to the Bull Market
Quarterly Webinar: Q4 2026 Market and Economic Themes
Medicare Open Enrollment 2026: What to Know
Subscribe to Our Blog
Chief Investment Officer | Managing Partner