The stock market has experienced historically strong returns over the past quarter, so the latest episode of volatility may raise questions among investors. The Nasdaq experienced its largest single-day fall in a year, with the index declining 4.2% on Friday, June 5.
Counterintuitively, the drop followed a strong jobs report, which is good news for the broader economy, and it raises the possibility of a Federal Reserve rate hike by the end of the year.1 At the same time, a brief re-escalation of the conflict in the Middle East added to investor concerns that have been in the background. While it’s normal for the stock market to experience swings, this recent volatility has some clear causes that history can help us understand.
Just as architects design buildings to withstand not just sunny days but all types of conditions, investors should remember that periods of strong returns are not a reason to forget about risk management and portfolio balance. While it’s important to appreciate when the market performs well, it’s during the good times that investors are best positioned to prepare their portfolios for whatever lies ahead.
After all, even with the latest one-day pullback, major market indices have still experienced healthy gains this year. History also suggests that we do not need to overreact to the prospect of Fed rate hikes. There can certainly be short-term volatility as markets anticipate tighter financial conditions, but the stock market has performed well across many different Fed rate hike cycles. Understanding why markets react to interest rates, and keeping these moves in perspective, can help investors stay focused on their long-term goals.
The market has experienced renewed volatility
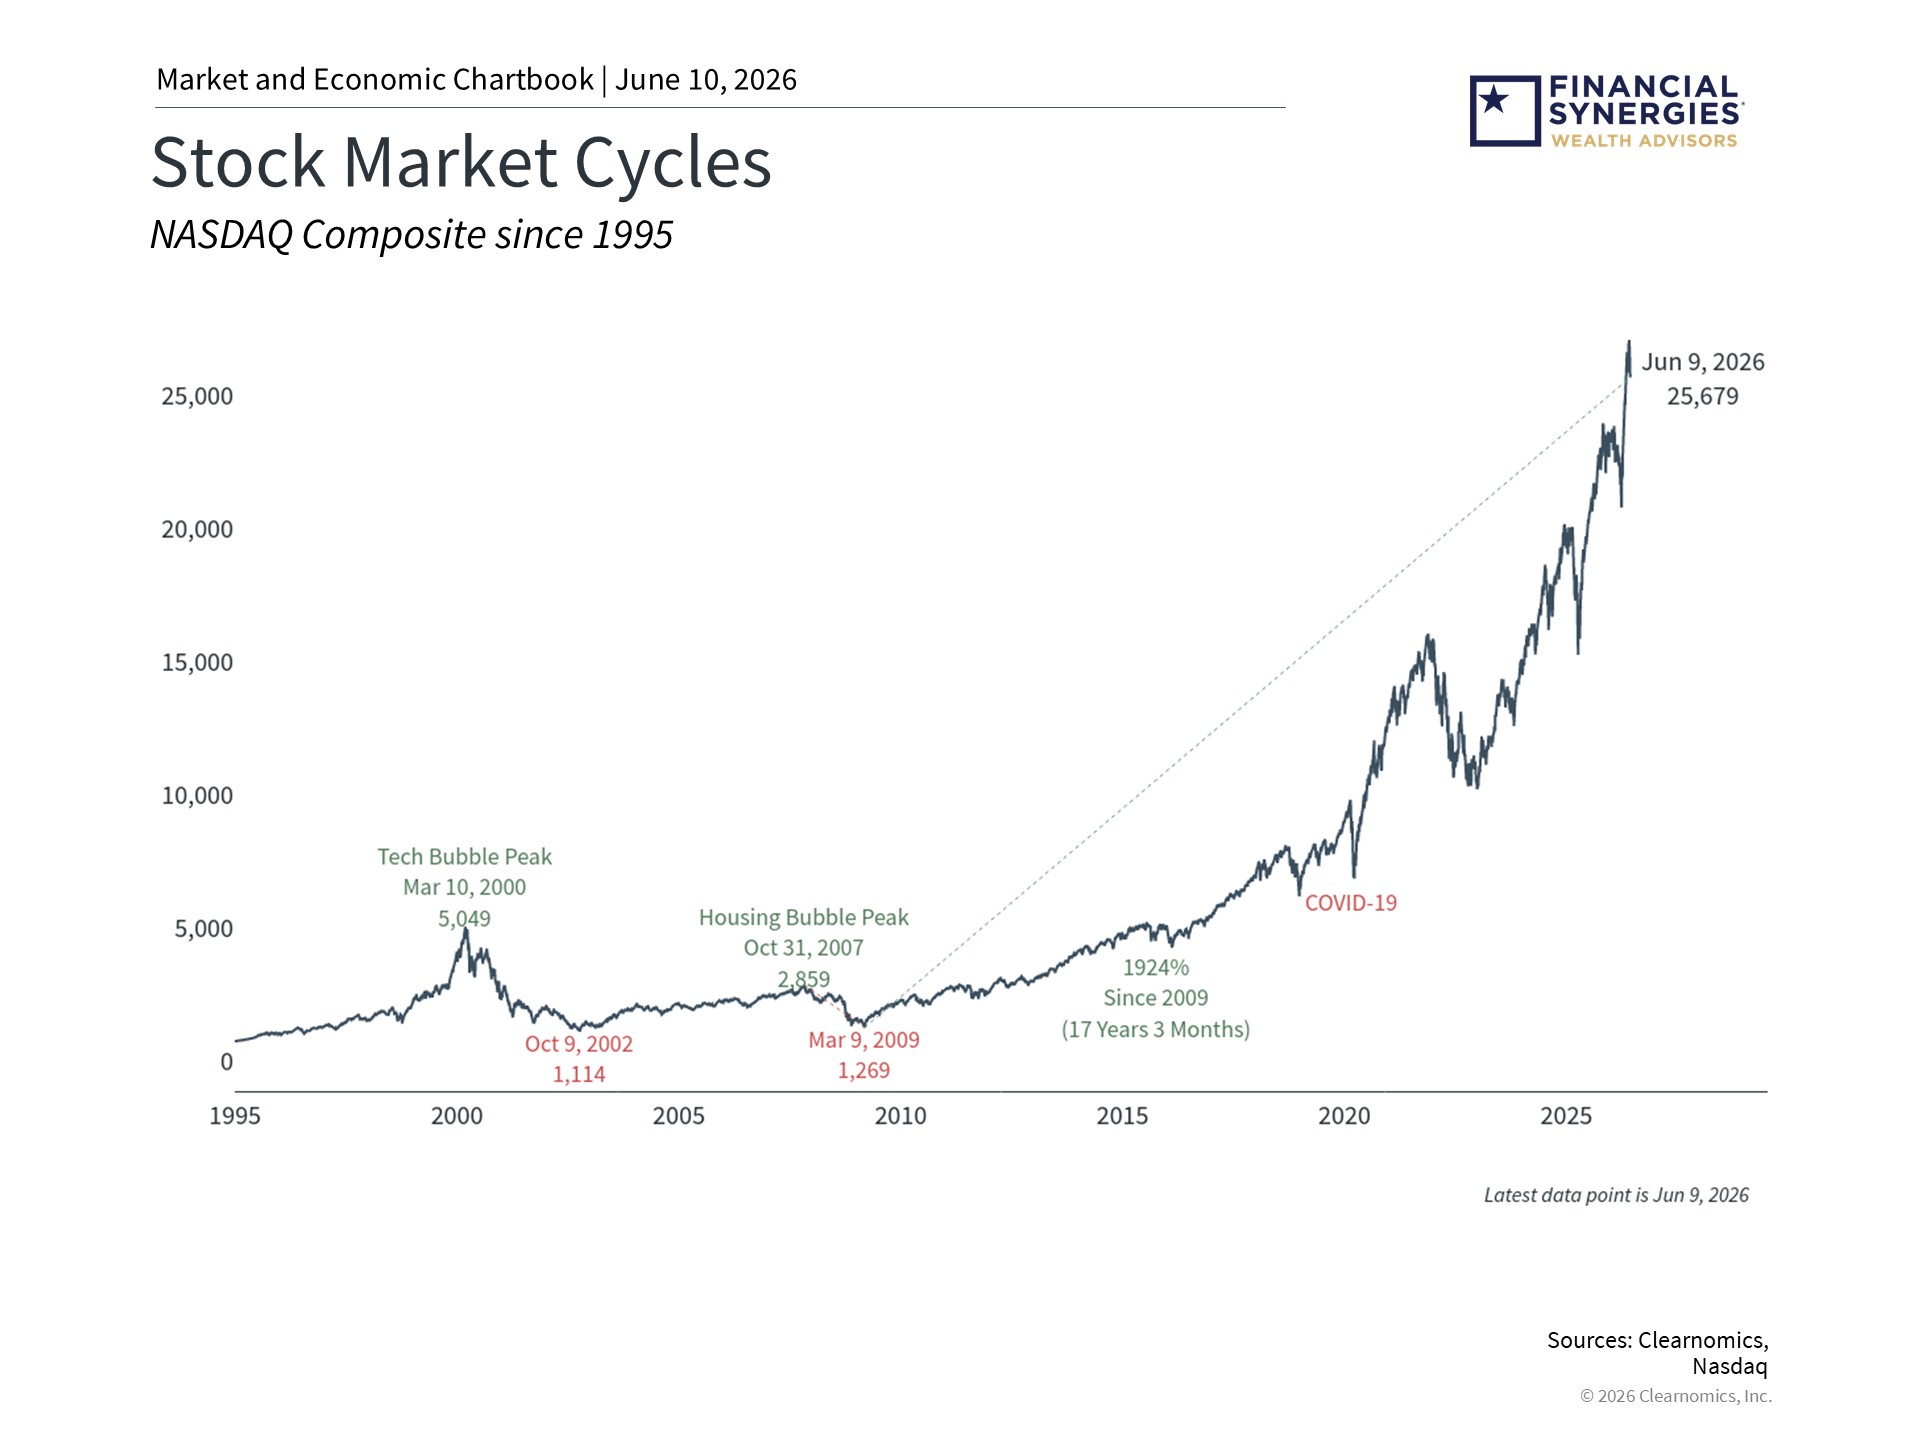
Major indices, including the S&P 500, Dow Jones Industrial Average, and the Nasdaq, have accelerated in recent months. Part of this strength can be described as a “relief rally.” Specifically, the conflict in the Middle East has had less of an economic impact than many originally feared, despite higher oil prices. Corporate earnings have also been strong and there is growing enthusiasm for a wave of upcoming initial public offerings.
Perhaps most interesting is the fact that the bond market has faced a more challenging environment as interest rates have remained high. Rates have risen along the entire yield curve this year, with the 10-year Treasury yield, for instance, around 4.5%.2 The bond market is sometimes described as the “smart money,” meaning that bond investors tend to more closely analyze the underlying trends in inflation, growth, and Fed policy compared to the stock market.
Whether this is the case or not, the bond market has been signaling that interest rates may stay higher than some had hoped, even as the stock market has rallied. It’s not too surprising, then, that the stock market recently reacted to these same developments. This is particularly true for technology and AI-related stocks, which are highly sensitive to interest rates.
Technology stocks can be sensitive to interest rates

A clear example of this sensitivity is the Magnificent 7, a group of large technology companies. From their peak at the end of 2021 to their bottom in late 2022, when inflation was heating up and interest rates jumped, this group lost about half of its value.3 This affected the value of the Nasdaq as well as broad sectors such as Information Technology and Communication Services. However, these groups then began to recover as rates stabilized and the Fed slowed its pace of hikes, eventually going on to rally to new highs.
Why are technology stocks sensitive to interest rates? Investors buy these stocks largely because they expect high growth that extends far into the future, in contrast to more established businesses with steady cash flows. Since interest rates affect how future profits are valued today, even small shifts, especially ones that change direction, can lead to large swings. Thus, interest rates are like a long lever, where even small moves at one end can make a large difference at the other.
This dynamic is important because technology-related stocks now constitute a larger proportion of the overall stock market. The Magnificent 7, for instance, now makes up about one-third of the S&P 500.4 Thus, many investors may hold a larger proportion of these companies than in the past. The chart above shows that even with the latest pullback, these sectors have performed well this year. Still, investors may experience periods of volatility they may not have in the past, which is why monitoring asset allocations and maintaining portfolio balance matters just as much when markets are rising as when they are falling.
Markets have performed well across Fed rate hike cycles
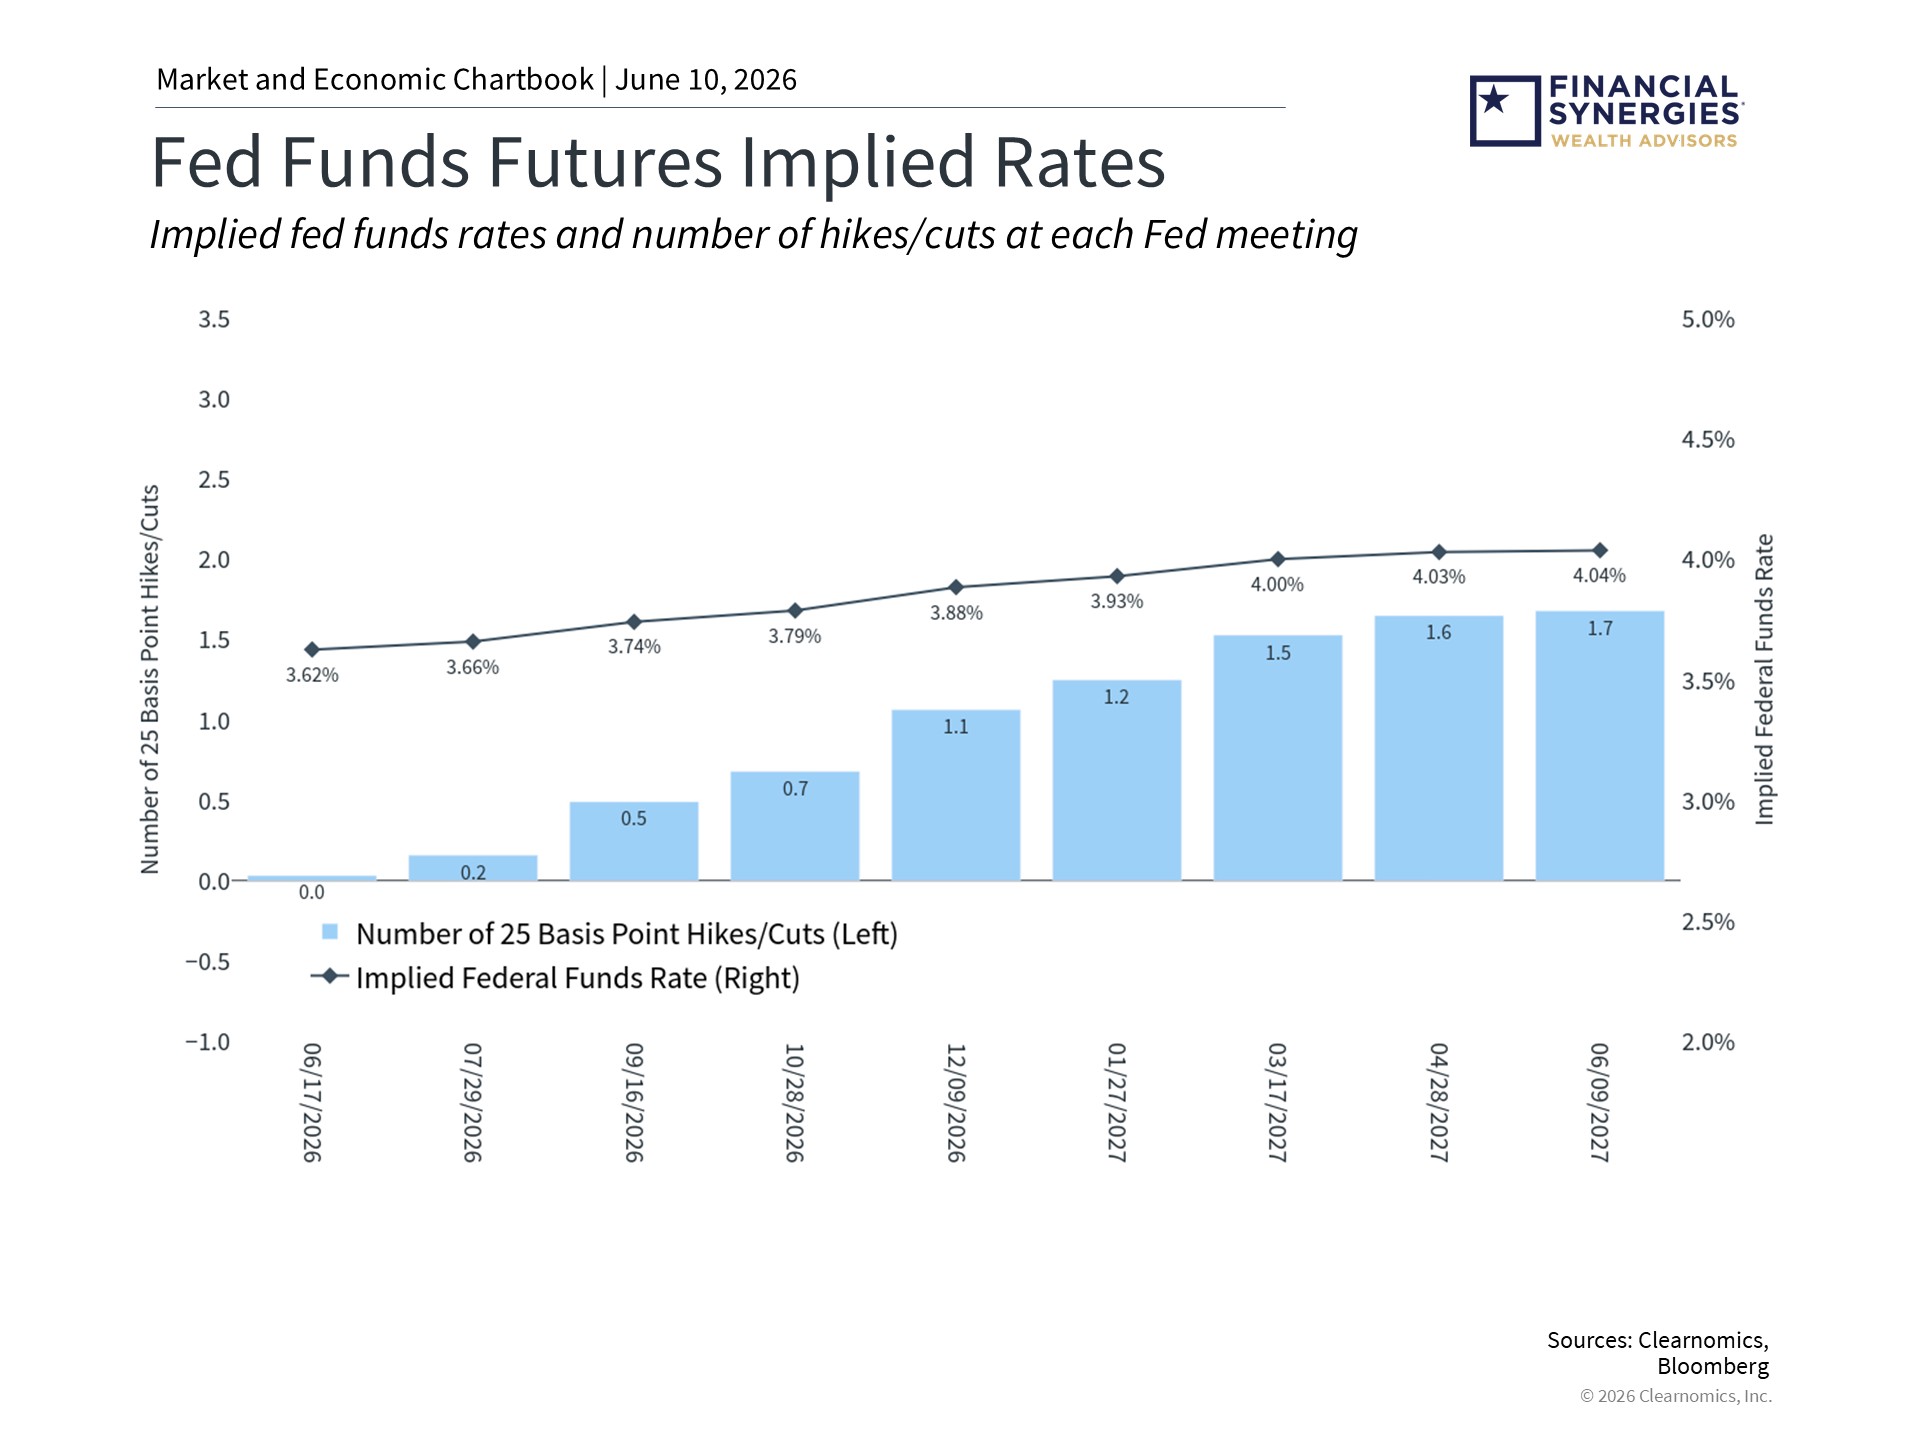
It’s important to remember that expectations for Fed policy can change quickly depending on the underlying economic conditions. Earlier this year, the consensus view was that the Fed would continue cutting rates. Those expectations shifted quickly as energy prices rose and the job market strengthened in recent months, as shown in the chart above. This is a reminder that the Fed is often reacting to economic events rather than sitting in the driver’s seat.
There is also some uncertainty around how Kevin Warsh, as the new Fed chair, will respond to inflation. In the past, he has been viewed as an inflation hawk, meaning he would lean toward raising rates to help stabilize prices for consumers and businesses. This would put him at odds with the White House’s desire for rate cuts. He has also publicly stated that the Fed ought to reduce its balance sheet, which in effect tightens financial conditions.5
However, all of this remains speculation until the Fed actually makes its decisions based on the actual economic environment. It’s also not yet certain whether this would be the beginning of a rate hike cycle, or simply a short period of tighter rates.
That said, even if current market expectations do prove to be correct, the Fed is not anticipated to raise rates until the end of the year, and only by 25 basis points, as seen in the chart above. This is a modest move by historical standards, especially compared to the rate hike cycle from 2022 to 2023, when the Fed raised rates from the zero-lower-bound to 5.25% over 11 hikes.6
More importantly, the market has performed well across many different rate environments, including periods when rates are rising. This is especially true when the Fed is tightening conditions because the economy is strong, since healthy growth tends to support corporate earnings. In other words, it’s not unusual in rising markets for the Fed to also be raising rates.
Recent volatility reflects the possibility of Fed rate hikes and renewed geopolitical tensions, but neither is a reason to fundamentally change long-term plans. While parts of the stock market may experience short-term volatility, history shows that markets can perform well across many different rate cycles.
References
1. https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
2. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics
3. The Magnificent 7 includes Apple, Microsoft, Nvidia, Amazon, Alphabet, Meta, and Tesla. The peak from 2021 to 2022 occurred on November 19, 2021, and the trough occurred on December 27, 2022.
4. Clearnomics research based on Standard & Poor’s data
5. https://www.wsj.com/opinion/the-high-cost-of-the-feds-mission-creep-role-responsibility-monetary-policy-economy-20a352f8
6. https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm#32979
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Making Sense of Recent Market Volatility
The stock market has experienced historically strong returns over the past quarter, so the latest episode of volatility may raise questions among investors. The Nasdaq experienced its largest single-day fall in a year, with the index declining 4.2% on Friday, June 5.
Counterintuitively, the drop followed a strong jobs report, which is good news for the broader economy, and it raises the possibility of a Federal Reserve rate hike by the end of the year.1 At the same time, a brief re-escalation of the conflict in the Middle East added to investor concerns that have been in the background. While it’s normal for the stock market to experience swings, this recent volatility has some clear causes that history can help us understand.
Just as architects design buildings to withstand not just sunny days but all types of conditions, investors should remember that periods of strong returns are not a reason to forget about risk management and portfolio balance. While it’s important to appreciate when the market performs well, it’s during the good times that investors are best positioned to prepare their portfolios for whatever lies ahead.
After all, even with the latest one-day pullback, major market indices have still experienced healthy gains this year. History also suggests that we do not need to overreact to the prospect of Fed rate hikes. There can certainly be short-term volatility as markets anticipate tighter financial conditions, but the stock market has performed well across many different Fed rate hike cycles. Understanding why markets react to interest rates, and keeping these moves in perspective, can help investors stay focused on their long-term goals.
The market has experienced renewed volatility
Major indices, including the S&P 500, Dow Jones Industrial Average, and the Nasdaq, have accelerated in recent months. Part of this strength can be described as a “relief rally.” Specifically, the conflict in the Middle East has had less of an economic impact than many originally feared, despite higher oil prices. Corporate earnings have also been strong and there is growing enthusiasm for a wave of upcoming initial public offerings.
Perhaps most interesting is the fact that the bond market has faced a more challenging environment as interest rates have remained high. Rates have risen along the entire yield curve this year, with the 10-year Treasury yield, for instance, around 4.5%.2 The bond market is sometimes described as the “smart money,” meaning that bond investors tend to more closely analyze the underlying trends in inflation, growth, and Fed policy compared to the stock market.
Whether this is the case or not, the bond market has been signaling that interest rates may stay higher than some had hoped, even as the stock market has rallied. It’s not too surprising, then, that the stock market recently reacted to these same developments. This is particularly true for technology and AI-related stocks, which are highly sensitive to interest rates.
Technology stocks can be sensitive to interest rates
A clear example of this sensitivity is the Magnificent 7, a group of large technology companies. From their peak at the end of 2021 to their bottom in late 2022, when inflation was heating up and interest rates jumped, this group lost about half of its value.3 This affected the value of the Nasdaq as well as broad sectors such as Information Technology and Communication Services. However, these groups then began to recover as rates stabilized and the Fed slowed its pace of hikes, eventually going on to rally to new highs.
Why are technology stocks sensitive to interest rates? Investors buy these stocks largely because they expect high growth that extends far into the future, in contrast to more established businesses with steady cash flows. Since interest rates affect how future profits are valued today, even small shifts, especially ones that change direction, can lead to large swings. Thus, interest rates are like a long lever, where even small moves at one end can make a large difference at the other.
This dynamic is important because technology-related stocks now constitute a larger proportion of the overall stock market. The Magnificent 7, for instance, now makes up about one-third of the S&P 500.4 Thus, many investors may hold a larger proportion of these companies than in the past. The chart above shows that even with the latest pullback, these sectors have performed well this year. Still, investors may experience periods of volatility they may not have in the past, which is why monitoring asset allocations and maintaining portfolio balance matters just as much when markets are rising as when they are falling.
Markets have performed well across Fed rate hike cycles
It’s important to remember that expectations for Fed policy can change quickly depending on the underlying economic conditions. Earlier this year, the consensus view was that the Fed would continue cutting rates. Those expectations shifted quickly as energy prices rose and the job market strengthened in recent months, as shown in the chart above. This is a reminder that the Fed is often reacting to economic events rather than sitting in the driver’s seat.
There is also some uncertainty around how Kevin Warsh, as the new Fed chair, will respond to inflation. In the past, he has been viewed as an inflation hawk, meaning he would lean toward raising rates to help stabilize prices for consumers and businesses. This would put him at odds with the White House’s desire for rate cuts. He has also publicly stated that the Fed ought to reduce its balance sheet, which in effect tightens financial conditions.5
However, all of this remains speculation until the Fed actually makes its decisions based on the actual economic environment. It’s also not yet certain whether this would be the beginning of a rate hike cycle, or simply a short period of tighter rates.
That said, even if current market expectations do prove to be correct, the Fed is not anticipated to raise rates until the end of the year, and only by 25 basis points, as seen in the chart above. This is a modest move by historical standards, especially compared to the rate hike cycle from 2022 to 2023, when the Fed raised rates from the zero-lower-bound to 5.25% over 11 hikes.6
More importantly, the market has performed well across many different rate environments, including periods when rates are rising. This is especially true when the Fed is tightening conditions because the economy is strong, since healthy growth tends to support corporate earnings. In other words, it’s not unusual in rising markets for the Fed to also be raising rates.
Recent volatility reflects the possibility of Fed rate hikes and renewed geopolitical tensions, but neither is a reason to fundamentally change long-term plans. While parts of the stock market may experience short-term volatility, history shows that markets can perform well across many different rate cycles.
References
1. https://www.cmegroup.com/markets/interest-rates/cme-fedwatch-tool.html
2. https://home.treasury.gov/policy-issues/financing-the-government/interest-rate-statistics
3. The Magnificent 7 includes Apple, Microsoft, Nvidia, Amazon, Alphabet, Meta, and Tesla. The peak from 2021 to 2022 occurred on November 19, 2021, and the trough occurred on December 27, 2022.
4. Clearnomics research based on Standard & Poor’s data
5. https://www.wsj.com/opinion/the-high-cost-of-the-feds-mission-creep-role-responsibility-monetary-policy-economy-20a352f8
6. https://www.federalreserve.gov/monetarypolicy/fomccalendars.htm#32979
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Happy Birthday to the Bull Market
Quarterly Webinar: Q4 2026 Market and Economic Themes
Medicare Open Enrollment 2026: What to Know
Subscribe to Our Blog
Chief Investment Officer | Managing Partner