Skip to content

Key Highlights
- Determining your retirement savings goal is crucial for a secure future, and it involves more than just a simple number.
- Your ideal retirement lifestyle, projected annual expenses, and sources of retirement income are key factors in your calculation.
- Common guidelines like the 4% Rule and the 80% Replacement Rule can provide a starting point for your retirement planning.
- Factoring in the inflation rate and potential healthcare costs is essential to protect your purchasing power over the long term.
- Social Security benefits, pensions, and personal savings all contribute to your overall retirement income, reducing the amount you need to save.
- How much do I need to retire? A financial advisor can help you navigate these complexities and tailor a retirement plan to your specific financial goals.
Understanding Your Retirement Savings Goal

Figuring out how much do I need to retire is one of the most critical questions in financial planning. The answer is deeply personal and depends on when you plan to retire and the lifestyle you envision. Establishing a clear retirement savings goal provides a concrete target to aim for, transforming an abstract concept into an actionable strategy.
Working with a financial advisor can help you quantify this goal. They will help you review your current financial situation, understand your aspirations for a comfortable retirement, and create a roadmap to get there. This initial step is the foundation of a sound retirement planning process, ensuring you are on the right track from the start.
How Much Do I Need to Retire?
A retirement savings goal is the total amount of money you need to accumulate in your retirement account to fund your life after you stop working. This “nest egg” is not an arbitrary figure; it’s a calculated sum designed to cover all your anticipated expenses for the duration of your retirement, ensuring you don’t outlive your savings.
This goal encompasses more than just basic living costs. It should account for essential expenses like housing and food, as well as discretionary spending such as travel and hobbies. Crucially, it must also include provisions for healthcare, which often becomes a significant expense in later years.
Ultimately, your retirement savings goal is a personalized financial target. It reflects your desired lifestyle, anticipated annual income needs, and other financial goals you may have, such as leaving an inheritance. Defining this number is the first step toward building a successful wealth management strategy.
Why Is Setting a Retirement Savings Goal Essential?
Setting a retirement savings goal provides direction and purpose for your financial decisions. Without a clear target, it’s difficult to know if you are saving enough or if your investment strategy is appropriate. A well-defined goal acts as a benchmark against which you can measure your progress and make necessary adjustments over time.
This clarity is fundamental to a successful strategy in retirement planning. It motivates you to stay disciplined with your savings and investments, even when faced with competing financial priorities. Knowing your target number helps you make informed choices about your spending and saving habits.
Furthermore, a specific goal enables a financial advisor to create a more effective and tailored plan for you. They can help you select the right investments and structure your retirement fund to align with your objectives, turning your retirement goals from a dream into a tangible reality.
Key Factors Influencing Your Retirement Savings Goal
Several key factors will shape the amount of money you need for retirement. Your desired lifestyle, life expectancy, and where you plan to live all play significant roles. The cost of living in your chosen location can dramatically alter your required retirement income.
Additionally, economic factors like the inflation rate will impact your purchasing power over time. Understanding how these elements interact is crucial for creating a realistic and robust retirement plan. We will explore how your retirement expenses and income sources fit into this complex equation.
Retirement Lifestyle Preferences
The kind of retirement you envision directly impacts your savings needs. Do you dream of traveling the world, or do you prefer a quiet life close to home? Your lifestyle choices are a primary driver of your financial goals and the size of the nest egg required to support them.
Consider the different tiers of retirement living. A basic retirement covers essentials with little room for extras, while a comfortable retirement allows for occasional travel and hobbies. A luxury retirement might include second homes and premium services, demanding significantly more savings. It’s important to be realistic about your aspirations to ensure your retirement planning is accurate.
To help define your desired lifestyle, think about:
- Travel: How often will you travel, and what will be your destinations?
- Housing: Will you stay in your current home, downsize, or buy a vacation property?
- Hobbies: What activities do you plan to pursue, and what are their associated costs?
- Social Life: How much do you anticipate spending on dining out and entertainment?
Expected Annual Expenses in Retirement
Once you have an idea of your retirement lifestyle, you can estimate your annual expenses. Many people find their spending decreases in some areas, like commuting, but increases in others, such as healthcare costs and leisure. A common approach is to aim for replacing 70-80% of your pre-retirement annual income.
However, this is just a general guideline. A more precise method is to create a detailed budget of your expected retirement expenses. This should include housing, food, transportation, and utilities, as well as costs for travel, hobbies, and entertainment.
Don’t forget to account for the impact of the inflation rate, which will cause prices to rise over time and erode the value of your savings. Building a buffer into your retirement account for these rising costs is a critical part of a solid financial plan.
Inflation and Cost of Living Adjustments
Inflation is a silent risk to your retirement security. Over time, the rising cost of living diminishes the purchasing power of your money. A dollar today will not buy as much in 20 or 30 years, which means your retirement fund must be large enough to withstand this erosion of value.
Even a modest inflation rate can have a significant impact over the course of a long retirement. For example, an annual budget of $80,000 today could require much more in the future just to maintain the same standard of living. This is why it’s crucial to factor inflation into your retirement calculations from the very beginning.
When planning, assume an average inflation rate and adjust your savings goals accordingly. This ensures your nest egg will not only last but also allow you to live comfortably without having to cut back on your lifestyle as you get older. A financial advisor can help model different inflation scenarios for your retirement age.
Healthcare and Long-Term Care Considerations
Healthcare is one of the largest and most unpredictable expenses in retirement. As we age, medical costs tend to increase, and it’s essential that your retirement planning accounts for these potential expenditures. Relying solely on Medicare may not be sufficient, as it doesn’t cover all services.
Many retirees need supplemental insurance to cover gaps in Medicare, such as dental, vision, and hearing. Another major consideration is long-term care, which involves services for individuals who can no longer perform daily activities on their own. The costs for nursing homes or in-home assistance can be substantial and are typically not covered by Medicare.
To prepare for these potential costs, you should:
- Factor projected healthcare costs and insurance premiums into your retirement budget.
- Explore options for long-term care, such as purchasing specific insurance or setting aside dedicated funds.
- Consider how a life insurance policy could provide liquidity for a surviving spouse to cover unexpected expenses.
Common Rules for Estimating Retirement Needs
While a personalized plan is always best, there are several common rules of thumb that can give you a general idea of how much you need to save. These guidelines, such as the 4% Rule and the 80% Replacement Rule, offer a simplified starting point for your retirement planning.
These formulas can help you quickly estimate the size of the nest egg required to generate a sustainable retirement income. However, remember that they are not a substitute for a comprehensive analysis performed with a financial advisor, who can tailor a plan to your unique circumstances.
The 4% Rule Explained
The 4% Rule is a popular guideline for determining a safe withdrawal rate from your retirement account. The rule suggests that you can withdraw 4% of your total savings in your first year of retirement and then adjust that amount for inflation in subsequent years. The goal is to provide a steady stream of retirement income without depleting your principal too quickly.
For example, if you have a $2 million nest egg, the 4% Rule would allow you to withdraw $80,000 in your first year. This rule is based on historical data for stock and bond returns and assumes a diversified portfolio of investments like mutual funds.
While it’s a useful benchmark, the 4% Rule has limitations. It doesn’t account for market volatility, changing personal expenses, or a retirement that lasts longer than 30 years. Your actual rate of return could be higher or lower, so it’s wise to view this rule as a starting point for discussion with your financial advisor.
The 80% Replacement Rule
The 80% Replacement Rule is another common guideline used in retirement planning. It suggests that you will need approximately 80% of your pre-retirement annual income to maintain a similar standard of living after you stop working. For someone earning $150,000 a year, this would mean aiming for a retirement income of $120,000.
The logic behind this rule is that some of your expenses will decrease in retirement. For instance, you will no longer be contributing to retirement accounts, and you may have paid off your mortgage. This reduction in expenses means you can live comfortably on a lower income.
However, the 80% replacement rate is an average and may not be right for everyone. Your personal financial goals and lifestyle choices could require a higher or lower percentage. It’s important to analyze your own spending habits to determine a more accurate income replacement target.
Age-Based Savings Benchmarks
Age-based savings benchmarks offer a way to gauge whether your retirement savings are on track. These guidelines suggest having a certain multiple of your current annual income saved by specific ages. For example, a common recommendation is to have one times your salary saved by age 30, three times by 40, and so on.
These benchmarks provide a simple snapshot of your progress. According to the Federal Reserve’s Survey of Consumer Finances, median retirement savings vary significantly by age group, highlighting that many Americans are behind where experts suggest they should be.
Here are some typical median savings amounts by age, which can serve as a rough comparison point:
| Age Group | Median Retirement Savings |
|---|---|
| 35-44 | $45,000 |
| 45-54 | $115,000 |
| 55-64 | $185,000 |
| 65-74 | $200,000 |
A financial advisor can help you interpret these figures in the context of your own retirement savings account and long-term goals.
Retirement Income Sources
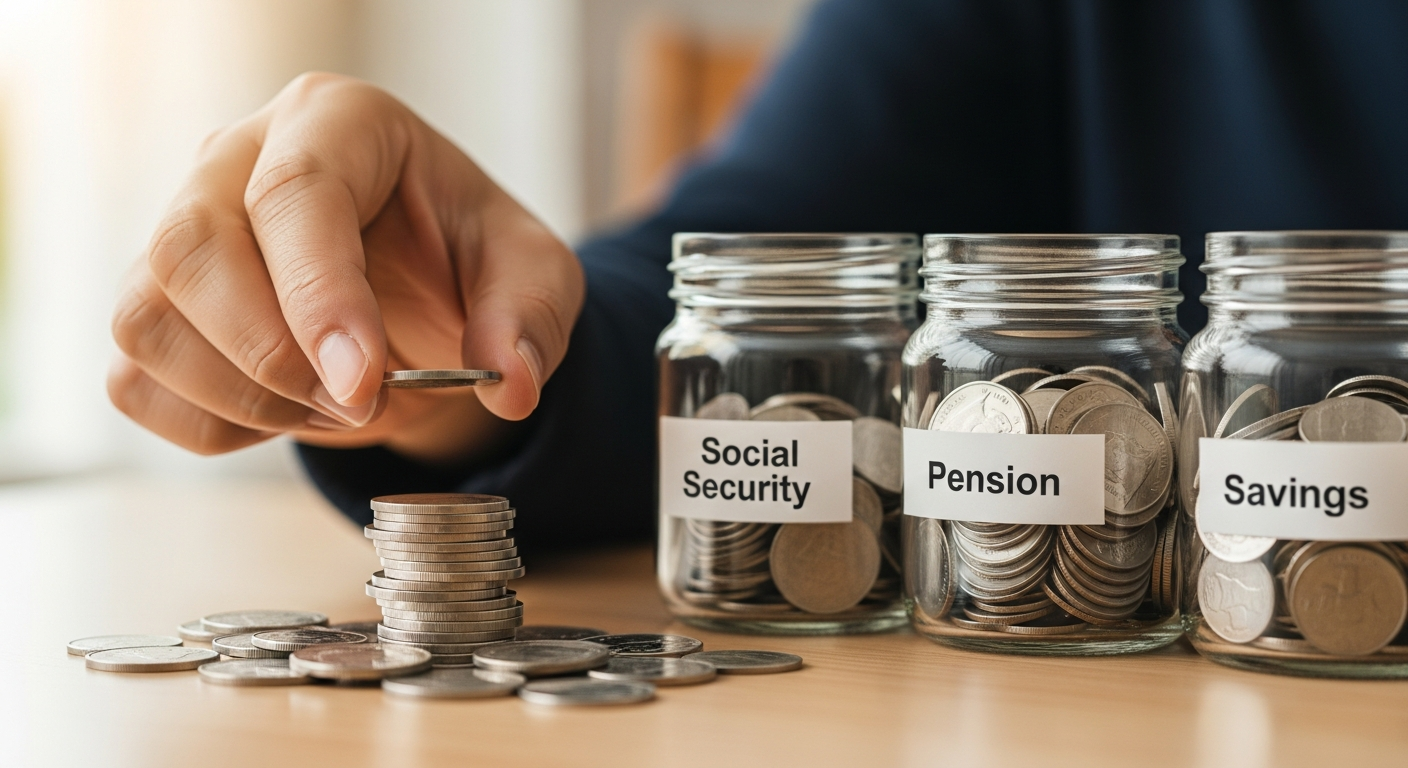
Your retirement nest egg is not the only source of funds you will have in your later years. Most retirees draw from multiple sources of income to cover their expenses. These can include government programs like Social Security, employer-sponsored plans, and your own personal savings and investments.
Understanding how each of these income streams works is a vital part of retirement planning. By combining these sources, you can create a diversified income strategy that provides financial security and reduces the pressure on your investment portfolio. We’ll examine how Social Security, pensions, and personal assets all contribute to your financial well-being.
Social Security Benefits
Social Security benefits are a foundational piece of retirement income for most Americans. The amount you receive from the Social Security Administration depends on your lifetime earnings and the age at which you decide to claim your benefits. While it’s designed to replace a portion of your working income, it is rarely enough to cover all expenses on its own.
You can start claiming Social Security as early as age 62, but your monthly payment will be permanently reduced. Waiting until your full retirement age (which is 66 or 67, depending on your birth year) entitles you to your full benefit. If you delay claiming until age 70, your monthly Social Security income will be even higher.
For high-net-worth individuals, Social Security may represent a smaller percentage of their overall retirement plans, but it still provides a reliable, inflation-adjusted income stream. A financial advisor can help you determine the optimal time to claim benefits as part of your comprehensive wealth management strategy.
Pensions and Employer Retirement Plans
For those fortunate enough to have them, pensions can provide a significant and stable source of retirement income. These plans, which are becoming less common in the private sector, typically offer a fixed monthly payment for life. If you have a pension, it’s important to understand your payout options and how they fit into your overall financial picture.
Employer contributions to retirement plans like 401(k)s are another valuable asset. These plans allow your savings to grow tax-deferred until you reach retirement age. The funds in your retirement account can be a cornerstone of your nest egg, providing the capital needed to generate income throughout your retirement.
Properly managing these employer-sponsored retirement plans is crucial. A financial planner can help you optimize your investment choices within the plan and develop a strategy for withdrawing the funds in a tax-efficient manner once you retire.
Personal Savings and Investments
Beyond employer plans, your personal savings and investments will likely form the largest part of your retirement funding. This includes money held in various savings accounts, such as a Traditional IRA or Roth IRA, as well as your taxable investment portfolio. These assets provide the flexibility and growth potential needed to achieve your financial objectives.
Your investment portfolio, which may include stocks, bonds, mutual funds, and real estate, is the engine that will drive the growth of your nest egg. The strategies you employ should be aligned with your risk tolerance and time horizon, becoming more conservative as you approach retirement.
Proper management of these personal savings is essential. A financial advisor specializing in high-net-worth families can help you structure your portfolio to generate the income you need while preserving capital for the long term. This includes making strategic decisions about asset allocation and withdrawal strategies from accounts like a Roth IRA, which offers tax-free distributions.
Healthcare and Long-Term Care Costs
As you plan for retirement, it’s imperative to give special attention to healthcare and long-term care costs. These expenses can be one of the biggest financial challenges for retirees, often exceeding initial estimates. A 65-year-old couple retiring today could face hundreds of thousands of dollars in healthcare expenses throughout their retirement, even with Medicare coverage. These costs include premiums, deductibles, and out-of-pocket spending for services that Medicare doesn’t cover.
Long-term care represents another significant potential expense. Services like assisted living or nursing home care are not typically covered by Medicare and can quickly deplete a retirement fund if not planned for. Addressing these unexpected expenses through dedicated savings, long-term care insurance, or other strategies is a critical part of comprehensive retirement planning. A financial planner can help you evaluate your options and integrate a healthcare cost strategy into your overall wealth management plan.
Calculating How Much You Need to Retire
Calculating your retirement savings goal can seem daunting, but it’s a manageable process if broken down into steps. You’ll start by gathering your personal and financial information and using a retirement calculator to get a preliminary estimate. This exercise will give you a clearer picture of where you stand and what you need to do to reach your goal.
This guide will walk you through the essential steps, from estimating your future expenses to identifying your income sources. With this information, you can begin to formulate a concrete plan. Remember, this is a starting point, and a financial advisor can help refine the calculations for greater accuracy.
What You’ll Need to Get Started
Before you begin calculating your retirement number, it’s helpful to gather all the necessary personal and financial information. Having this documentation on hand will make the process smoother and your estimates more accurate. You will need details about your current income, savings, investments, and debts.
Here is a list of what you’ll typically need:
- Statements from all your retirement accounts (401(k), IRA, etc.).
- Information on your current annual income and savings rate.
- An estimate of your expected Social Security benefits.
- A list of your current monthly expenses to help project retirement spending.
- Details on any other income sources, such as pensions or rental income.
Step-by-Step Guide to Calculating Your Retirement Savings Goal
Calculating your retirement savings goal is a multi-step process that brings together all the factors we’ve discussed. By following these steps, you can create a clear and actionable estimate of the nest egg you’ll need. This calculation is the cornerstone of your retirement planning efforts.
Each step builds upon the last, moving from your expected expenses to your available income and finally to the savings required to bridge the gap. This structured approach helps demystify the process and provides a logical framework for your financial goals.
Embarking on this calculation is a proactive move toward securing your financial future. As you work through the steps, you’ll gain a deeper understanding of what it will take to achieve the retirement you envision. Let’s begin the process of determining your personal retirement number.
Step 1: Estimate Your Annual Retirement Expenses
The first step in your calculation is to estimate how much you’ll spend each year in retirement. This figure will be the basis for determining the total size of the retirement account you need to build. A good starting point is to look at your current annual income and expenses.
Think about which costs will remain, which will disappear, and which new ones might appear. For example, your mortgage may be paid off, but your travel and healthcare costs might increase. It’s better to be conservative and slightly overestimate your expenses to create a buffer.
Remember to account for the inflation rate, as the cost of living will rise over time. Projecting your expenses in future dollars will give you a more realistic target. This detailed budget is far more accurate than relying on a simple percentage of your pre-retirement income.
Step 2: Identify Your Income Sources
Next, you need to identify all the guaranteed income sources you will have in retirement. These are the funds you can rely on to cover a portion of your expenses, which will reduce the amount you need to withdraw from your investment portfolio. The most common source is Social Security benefits.
You may also have other income streams to consider. These could include payments from a pension plan, rental income from real estate properties, or earnings from a part-time business or consulting work. Every dollar of guaranteed income reduces the pressure on your nest egg.
Make a comprehensive list of these income sources and estimate the total annual amount you expect to receive. Be realistic with your projections. For example, use the official estimates from the Social Security Administration for your benefits. This step is crucial for understanding the full scope of your retirement income.
Step 3: Calculate the Gap Between Expenses and Income
Now it’s time to determine the “income gap.” This is the difference between your estimated annual retirement expenses (from Step 1) and your total annual income from guaranteed sources (from Step 2). This gap represents the amount of money your personal savings and investments will need to generate each year.
For instance, if you estimate you’ll need $120,000 per year in retirement and you expect to receive $40,000 from Social Security and a pension, your income gap is $80,000. This is the annual amount you will need to withdraw from your retirement fund.
Calculating this gap is a critical moment in your retirement planning. It crystallizes the role your nest egg must play. If the gap is larger than you anticipated, you may need to revisit your expense estimates or explore ways to increase your retirement income sources. A financial advisor can help you strategize around this number.
Step 4: Apply Retirement Calculation Rules (4%, 80% Rule)
With your annual income gap calculated, you can now apply one of the common rules of thumb to estimate the total size of the nest egg you’ll need. These rules provide a simple way to translate an annual income need into a total savings target for your retirement account.
The 4% Rule is particularly useful here. By dividing your annual income gap by 4% (or multiplying it by 25), you can get a rough estimate of the total savings required. This calculation assumes your portfolio can sustain a 4% withdrawal rate over the long term.
Here’s how to apply the rules:
- The 4% Rule: If your income gap is $80,000, you would need a nest egg of $2 million ($80,000 ÷ 0.04).
- The 80% Rule: This rule helps in the expense estimation phase. If your pre-retirement income is $200,000, you’d aim for a retirement income of $160,000. Subtracting other income sources from this gives you the gap to apply the 4% rule.
Step 5: Adjust for Inflation and Unexpected Costs
The final step is to refine your retirement savings goal by adjusting for inflation and building in a cushion for unexpected costs. The number you calculated in the previous step is in today’s dollars. You need to project its future value to account for the rising cost of living.
Inflation will steadily decrease your purchasing power, so your target nest egg must be large enough to compensate. Your financial advisor can use sophisticated modeling to show how inflation will impact your goal over time, ensuring your savings target is adequate for your actual retirement date.
Additionally, life is full of surprises. Unexpected expenses, especially major healthcare costs, can derail a retirement plan if not accounted for. Including an extra buffer in your savings goal provides a safety net, giving you peace of mind and the financial resilience to handle whatever comes your way.
A Truly Unique Wealth Management Experience
Let’s create a financial plan and investment strategy that allows you to live the life of your dreams. Schedule your free consultation today to explore tailored financial strategies designed to secure your future!
Frequently Asked Questions
How much does the average person need to retire in the U.S.?
There’s no single answer, as retirement needs vary widely. However, data from the Survey of Consumer Finances shows the median retirement savings for households aged 65-74 is around $200,000. Financial experts often suggest a nest egg of $1 million or more for a comfortable retirement in the United States.
Can social security payments reduce how much I need retire?
Yes, absolutely. Social Security benefits provide a guaranteed stream of retirement income, which directly reduces the amount you need to withdraw from your personal retirement savings each year. Factoring your expected Social Security payments into your plan will lower your overall savings target.
Are retirement calculators useful for figuring out my retirement savings goal?
Retirement calculators are a decent starting point for estimating your savings needs. They can provide a quick overview based on your inputs. However, for a comprehensive and accurate calculation tailored to your specific financial goals, it is best to work with a financial advisor who can conduct a more detailed retirement planning analysis.
What should I consider if I want to retire early?
Early retirement requires more aggressive savings and meticulous planning. You’ll need a larger nest egg to cover a longer retirement period, and you must plan for healthcare costs before you are Medicare-eligible. A financial advisor can help you assess the feasibility and adjust your savings accounts and investment strategies accordingly.
Concerns or questions about your tax situation or financial plan? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate markets and developing custom financial plans. To learn more about our approach to financial planning please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
- How to Create a Financial Plan in 7 Steps
- Financial Planning Basics: Where to Start
- 2026 Important Tax Numbers: A Handy Guide
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.