Skip to content

Key Highlights of How to Start Saving For Retirement
- Retirement planning tips start with clear retirement goals, a realistic timeline, and a view of future retirement income needs.
- Your retirement savings strategy should reflect lifestyle, health care, inflation, and expected retirement age.
- The right retirement account mix may include a 401(k), traditional IRA, or Roth IRA, depending on tax priorities.
- Strong retirement savings depend on disciplined contributions, employer matching, and compound interest.
- High-net-worth investors often need integrated financial planning, asset allocation, and estate planning support.
- Ongoing reviews help keep your retirement plan aligned with market shifts and evolving priorities.
Understanding Retirement Planning Tips for High-Net-Worth Investors
For high-net-worth individuals, retirement planning is not just about saving more. It is about structuring a retirement plan that supports lifestyle goals, tax efficiency, and long-term flexibility. Your financial planning should begin with retirement goals, expected spending, and a realistic retirement date.
Just as important, your asset allocation must reflect both opportunity and risk. Many sophisticated investors benefit from coordinated wealth management that connects investments, cash flow, and legacy priorities. The next sections explain why this process matters and how to begin with confidence.
Why Retirement Planning Tips Are Essential for Financial Security
Retirement planning creates the foundation for financial security once earned income stops. If you want to maintain your standard of living, you need a clear savings plan well before retirement begins. Social Security benefits may help, but they are generally supplemental rather than a full source of retirement income.
A strong approach with retirement planning tips starts with the most important steps: estimate future expenses, choose the right retirement account structure, invest contributions, maximize savings, and review progress over time. Those five moves create a practical framework for building retirement savings with purpose.
You also need to think beyond today’s bills. Housing, health care costs, hobbies, travel, inflation, and life expectancy all shape what retirement will cost. The earlier you start retirement planning, the more time compound interest has to work in your favor.
Unique Needs of Sophisticated Investors
High-net-worth individuals in the United States often face more moving parts than the average investor. Multiple income sources, taxable and tax-advantaged accounts, and larger balance sheets can make retirement decisions more complex. That is why high net worth financial planning requires a broader lens than simply picking a retirement account.
In many cases, the right investment options include a mix of stocks, bonds, mutual funds, and ETFs held across different account types. Your asset allocation should match your time horizon, level of risk, and retirement goals rather than short-term market noise.
At the same time, estate planning and tax coordination matter. A trusted investment advisor or financial advisor can help align your retirement planning with your broader financial future. For high net worth families, this integrated approach often leads to better long-term outcomes.
Key Factors Influencing Your Retirement Savings Strategy
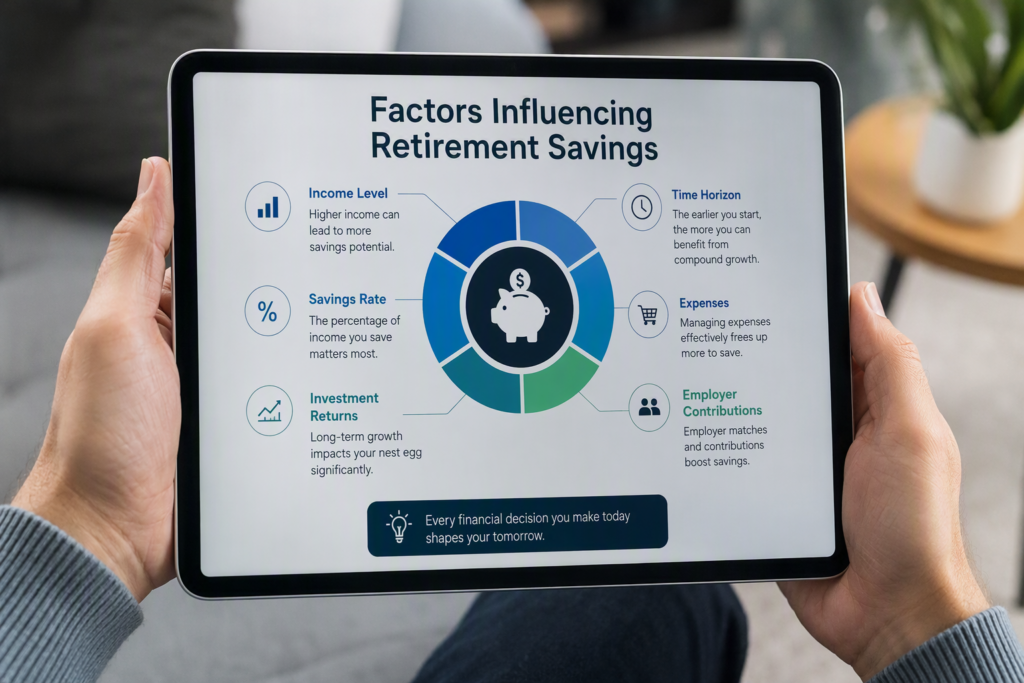
Your retirement savings strategy should reflect more than income alone. A sound savings plan considers retirement age, expected years in retirement, future cost of living, health care needs, and where you plan to live. Each factor changes how much money you may need.
At the same time, risk tolerance shapes how aggressively you invest. Some investors need a growth-focused mix, while others prioritize stability. Before choosing contribution levels, it helps to understand the lifestyle and balance sheet variables that drive the numbers.
Desired Lifestyle Considerations
Age matters because time changes the math. If you start saving in your early years of retirement planning, compounding has more time to build wealth. If retirement is closer, your monthly savings may need to be much higher to reach the same result.
Income matters too, but the better question is how much of your current lifestyle you want to preserve. Many investors estimate retirement needs based on a portion of pre-retirement income, while also adjusting for living expenses that may rise or fall after leaving work.
Then there is timing. Your full retirement age, intended retirement date, housing plans, travel, and health care costs all affect the target. A practical answer to how much you should save each month depends on your income, time horizon, and the standard of living you expect to maintain.
Assessing Current Assets and Future Financial Goals
Before building a strategy, take inventory of your current assets. That means reviewing every retirement account, savings account, taxable investment account, and other resources that may support your financial future. You cannot set meaningful financial goals without knowing your starting point.
If you are just getting started, a simple retirement plan begins with a few basic retirement planning tips:
- List all current assets and account balances.
- Estimate future living expenses and retirement needs.
- Identify which retirement account options are available to you.
- Set an automatic monthly contribution target.
From there, future planning becomes more precise. You can compare what you have today with what you may need later, then adjust savings and investments accordingly. For sophisticated investors, this step is essential to disciplined wealth management and long-range financial planning.
What You Need to Get Started with Retirement Saving Tips
Getting started with retirement planning tips begins with organization. You need current account statements, a clear list of assets and liabilities, and a basic estimate of future expenses. Good financial planning starts with facts, not assumptions.
You also need guidance you can trust. For many investors, especially those with complex finances, a financial advisor can help turn scattered information into a structured retirement account strategy. The next two sections cover both the documents and advisory support that matter most.
Gathering Financial Documents
Start by collecting the core financial documents that define your retirement plan. These records show where your money is today and help you measure what is missing. Without updated account statements, it is difficult to make informed decisions about contributions, investments, or tax advantages.
Focus on gathering the following documents:
- Retirement account statements, including 401(k), IRA, and Roth IRA balances.
- Savings account and brokerage account statements.
- Records that show income, current spending, and recurring living expenses.
- Any documents tied to pension plan or other retirement benefits.
Once these materials are in one place, the first planning steps become clearer. You can estimate retirement expenses, identify gaps, and choose which accounts to prioritize. This simple exercise often gives investors the first real picture of whether they are on track.
Selecting Trusted Financial Advisors
When thinking about retirement planning tips, not every investor needs the same level of support. Still, if your finances involve multiple retirement account types, significant assets, or tax-sensitive decisions, expert guidance can add clarity. A qualified financial advisor can help structure retirement planning around your goals rather than generic rules.
A strong investment advisor should understand how different account types work, including 401(k)s, traditional IRAs, and Roth IRAs. They should also help you evaluate investment options, contribution choices, and the effect of current tax laws on future withdrawals.
For high net worth individuals, this advice is often part of a broader wealth management relationship. Financial Synergies Wealth Advisors approaches this work with a planning-first mindset, helping clients connect investments, taxes, and long-term family priorities in one coordinated strategy.
Step-by-Step Guide to Retirement Planning Tips
Saving for retirement is easier when you follow a clear sequence. Here we outline specific retirement planning tips. Start with your retirement goals, then set a timeline, calculate a monthly target, choose the right retirement account mix, and invest with discipline. Over time, compound interest can do meaningful work for you.
If you feel behind, structure matters even more. A practical savings plan can help you close the gap without overcomplicating decisions. The next five steps provide a simple framework you can tailor to your income, assets, and long-term objectives.
Step 1: Define Your Retirement Timeline
Begin with timing. Your retirement timeline influences nearly every major decision, from contribution levels to investment mix. If you expect to retire early, you will likely need a larger pool of assets than someone targeting a later retirement date.
Next, define your retirement goals in practical terms. Think about where you will live, how you will spend your time, and what standard of living you want to maintain. Travel, charitable giving, and changing housing needs all affect the numbers.
This is where financial planning becomes specific. Once you establish your time horizon and target retirement date, you can estimate future costs with more accuracy. That gives you a stronger basis for deciding how much to save, where to invest, and how much risk to accept.
Step 2: Calculate Monthly Savings
Now turn your goals into numbers. Your monthly savings target should begin with income, but it should not end there. You also need to account for cost of living, expected retirement expenses, inflation, and how many years remain before retirement.
Some investors benchmark against salary multiples or a target percentage of pre-retirement income needed each year in retirement. Those guides can be useful starting points, especially when you are building a first savings plan. Still, your actual target should reflect your lifestyle and expected spending.
If your monthly savings number feels high, do not assume the plan has failed. You may be able to improve results by increasing contributions gradually, capturing employer matching, or reviewing your account mix. Consistency often matters more than perfection in building retirement savings.
Step 3: Choose Tax-Advantaged Retirement Accounts
Selecting tax-advantaged retirement accounts is crucial for optimizing your retirement savings. Options such as 401(k)s, IRAs, and Roth IRAs all offer unique tax benefits that can enhance your overall financial plan. By allocating a portion of your income to these vehicles, you can effectively lower your taxable income, leverage compound interest, and create a diversified investment portfolio tailored to your risk tolerance and retirement goals. Consulting with a financial advisor experienced in high net worth financial planning can provide personalized guidance, helping you navigate complex tax laws and maximize your long-term wealth management strategy. A well-structured retirement account not only positions you for financial security but also alleviates potential healthcare costs and living expenses as you approach retirement age.
Step 4: Diversify Investments
Funding an account is only the first half of the job. To grow retirement funds, you need an investment portfolio built around your asset allocation, time horizon, and risk tolerance. The goal is to balance growth potential with a level of risk you can realistically hold through market cycles.
Common investment portfolio options include the following:
- Stocks for long-term growth potential
- Bonds for income and stability
- Mutual funds and ETFs for diversification
- Target-date funds for a simplified investment mix
Diversification helps reduce concentration risk, though it does not ensure a profit or prevent loss. For many investors, especially those new to retirement planning, a disciplined blend of assets is more effective than chasing short-term trends. The right mix should support your retirement goals, not distract from them.
Step 5: Review and Adjust Contributions
A retirement plan should not remain static. As income changes, markets move, and your time horizon shortens, your contributions and investment mix may need adjustment. Regular reviews help keep your savings plan aligned with your actual goals.
If you feel behind, one of the best ways to improve progress is to increase retirement account contributions steadily rather than waiting for the perfect time. Automatic increases, annual reviews, and employer matching can make a meaningful difference over time.
Portfolio rebalancing matters too. Market gains can shift your asset allocation away from its intended target, increasing risk without you noticing. A financial advisor can help you review contributions, rebalance holdings, and keep your strategy focused on long-term outcomes rather than short-term volatility.
GUIDE: Investments Review
At Financial Synergies Wealth Advisors, we help high net worth individuals and high net worth families align portfolio strategy with behavior, liquidity, and long-term purpose. If you want a clearer view of how your current allocation fits your objectives, download our Investments Review guide.
Maximizing Retirement Savings for High-Net-Worth Individuals
For high-net-worth individuals, maximizing a retirement savings plan often means going beyond basic contribution habits. You need to understand contribution limits, catch-up opportunities, and how different accounts fit into a broader tax and investment strategy.
That is where advanced strategies can help. For investors with substantial assets, small adjustments in account funding, investment structure, and giving plans may improve long-term results. The next sections focus on practical ways to strengthen an already solid foundation.
Contribution Limits and Catch-Up Provisions
One of the simplest ways to boost retirement savings is to use the full room available in each retirement account. Annual contribution limits exist for a reason. If you are not maximizing them, you may be leaving tax benefits and long-term growth on the table.
This becomes even more important later in your career. If you are age 50 or older, catch-up contributions can help close savings gaps and strengthen retirement readiness. They are especially useful for investors who built significant income later in life.
Prioritize these moves for your retirement savings if you can:
- Contribute enough to capture the full employer match in a 401(k)
- Review annual contribution limits for each eligible account
- Use catch-up contributions when age permits
For high net worth families, disciplined use of these rules can be a meaningful part of high net worth financial planning.
Advanced Investment Strategies
Advanced investment strategies should still begin with the basics: a sound asset allocation, a suitable level of risk, and a diversified investment portfolio. Greater complexity does not always produce better outcomes. What matters is whether each decision supports your financial future.
For sophisticated investors, asset location, tax benefits, and withdrawal planning can add value when coordinated carefully. A mix of retirement accounts and taxable assets may provide more flexibility as tax laws and income needs change over time.
Charitable giving may also play a role in retirement planning for affluent households. When integrated with broader financial planning and estate planning goals, it can support both personal priorities and long-term wealth management objectives. The key is alignment, not activity for its own sake.
Useful Retirement Planning Tips for Tools, Calculators

Good retirement planning tips can help you move from rough estimates to measurable targets. In retirement planning, calculators and worksheets are useful for estimating retirement needs, future income, and expected expenses. They also make assumptions easier to test.
Still, numbers are most helpful when you can track them over time. Financial dashboards and regular reviews allow you to compare projections with actual progress. The next sections explain how these tools can support better decisions without adding unnecessary complexity.
Estimating Retirement Needs
If you are wondering whether useful tools exist for retirement planning tips, the answer is yes. Online calculators can help estimate retirement needs by comparing projected savings, retirement income, and future retirement expenses. They are especially helpful when you want a first-pass view of whether your current path is realistic.
Several useful tools can support your future retirement planning, including the following:
- Retirement income calculators to compare projected assets with expected income needs
- Retirement expenses worksheets to build a realistic spending estimate
- IRA contribution calculators to review annual saving limits
These tools do not replace advice, but they can sharpen your planning. They are most valuable when paired with accurate assumptions about cost of living, health care costs, and retirement date. Used well, they can turn broad goals into actionable next steps.
Tracking Progress
A personalized dashboard gives you a clearer view of your retirement plan in one place. Instead of checking accounts separately, you can monitor balances, contributions, and projected outcomes together. That makes tracking progress simpler and more objective.
Dashboards are especially useful for comparing your savings plan with real-world changes. If living expenses increase, contributions fall, or market performance shifts your portfolio, you can see the effect faster. That visibility helps you make better decisions before small issues become large ones.
For high net worth individuals and high net worth families, this kind of reporting supports disciplined wealth management. It also improves communication with your financial advisor, since both strategy and execution can be reviewed using the same data and planning assumptions.
GUIDE: Investments Review
At Financial Synergies Wealth Advisors, we help high net worth individuals and high net worth families align portfolio strategy with behavior, liquidity, and long-term purpose. If you want a clearer view of how your current allocation fits your objectives, download our Investments Review guide.
Frequently Asked Questions
What are common mistakes in retirement planning?
Common mistakes include underestimating retirement goals, ignoring tax laws, relying too heavily on Social Security, and failing to review retirement savings regularly. You can avoid them by estimating expenses carefully, maximizing contributions, and working with a financial advisor when your finances become more complex.
How much should I save for retirement based on my income?
Your monthly retirement savings target depends on income, cost of living, expected retirement lifestyle, and time horizon. A useful approach is to estimate future expenses first, then work backward to a monthly savings plan. The earlier you start, the less pressure each monthly contribution must carry.
What are best ways to boost retirement savings?
If you feel behind, increase each retirement account contribution gradually, capture any employer match, and use catch-up contributions if your age allows. Automating your savings plan can help. Even later in the process, consistent saving and compound interest can still improve retirement readiness meaningfully.
What are investment options for long-term growth?
For long-term growth, consider a diversified investment portfolio that may include stocks, bonds, mutual funds, and ETFs. Your asset allocation should match your risk tolerance and time horizon. For some investors, target-date funds offer a simple way to maintain a balanced mix over time.
A Truly Unique Wealth Management Experience
Let’s create a financial plan and investment strategy that allows you to live the life of your dreams. Schedule your free consultation today to explore tailored financial strategies designed to secure your future!
Concerns or questions about your tax situation or financial plan? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate markets and developing custom financial plans. To learn more about our approach to financial planning please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.