Skip to content

Key Highlights
- Dynamic portfolio rebalancing keeps your investment portfolio aligned with the target asset allocation as market conditions change.
- Unlike static methods, a dynamic portfolio rebalancing strategy responds to drift, volatility, and risk management needs in real time.
- For high-net-worth investors, dynamic portfolio rebalancing is mainly a discipline of controlling risk, not chasing returns.
- Threshold-based methods can reduce unnecessary trading and transaction costs compared with rigid calendar schedules.
- Tax-aware implementation matters because capital gains can affect after-tax compounding and long-term outcomes.
- Smart, dynamic portfolio rebalancing also considers liquidity, private investments, and evolving financial goals.
Understanding Dynamic Portfolio Rebalancing for High-Net-Worth Investors
Dynamic portfolio rebalancing is the process of adjusting your investment portfolio when asset allocation drifts meaningfully from target weights. For high-net-worth investors, that drift often comes from market volatility, uneven asset class performance, and the added complexity of private holdings or taxable accounts.
In contrast, static rebalancing follows a fixed schedule whether or not change is needed. A dynamic portfolio rebalancing strategy responds to actual market conditions and portfolio movement. That difference matters when you want tighter control over risk, better alignment with your objectives, and more thoughtful implementation across wealth management and retirement planning decisions.
Defining Portfolio Rebalancing: Dynamic Versus Static
Dynamic portfolio rebalancing means bringing your investment portfolio back toward its intended mix after one asset class outperforms or lags. If equities rise faster than fixed income, your allocation can shift away from the level originally designed for your risk tolerance, investment goals, and expected return profiles.
With static rebalancing, trades happen on a calendar schedule. That approach is simple, but it can lead to small, frequent transactions even when portfolio drift is minor. Research discussed in the compiled information suggests this offers little advantage because the true need to rebalance depends on how far weights have moved from target.
Dynamic portfolio balancing works differently. It reacts when allocation bands are breached or when current conditions justify action. In practice, that means selling overweight exposures and adding to underweight positions only when needed. For a financial advisor serving high net worth families, this creates a more disciplined link between asset allocation, risk management, and financial planning.
Key Principles Behind Dynamic Rebalancing
At its core, a dynamic portfolio rebalancing strategy is a risk management process. The goal is not constant trading. The goal is to keep your portfolio characteristics close to a carefully chosen target that reflects your investment objectives, liabilities, spending needs, and tolerance for loss.
Several principles support that process:
- Rebalance based on meaningful drift, not habit alone.
- Review whether your investment policy still matches your current circumstances.
- Use lower-cost funding sources first, such as new cash, dividends, or distributions.
Just as important, dynamic portfolio rebalancing should reflect changing market conditions without becoming market timing. The compiled information favors threshold-based models because they allow enough flexibility for compounding while limiting unintended risk. For high net worth financial planning, that balance is especially effective because portfolios often involve taxable assets, fixed income, and less liquid holdings that require careful implementation.
Why High-Net-Worth Individuals Need Dynamic Portfolio Rebalancing
High-net-worth investors often hold more than a simple stock-and-bond mix. Their portfolios may include private investments, concentrated equity positions, charitable goals, and taxable accounts. That complexity means volatility can alter return profiles and portfolio risk faster than many investors expect.
At the same time, risk tolerance can change as wealth compounds. Someone whose assets grow well beyond spending needs may be able to accept more equity exposure and update target allocations rather than automatically rebalance back to an older mix. This is why a financial planner should revisit assumptions before placing trades.
For high net worth individuals and high net worth families, the advantage of a dynamic portfolio rebalancing strategy is flexibility with discipline. It helps maintain alignment with financial goals while considering taxes, liquidity, and changing circumstances. In retirement planning and wealth management, that can lead to better decisions than following a rigid schedule that ignores what has actually changed.
Core Components of Successful Dynamic Portfolio Rebalancing
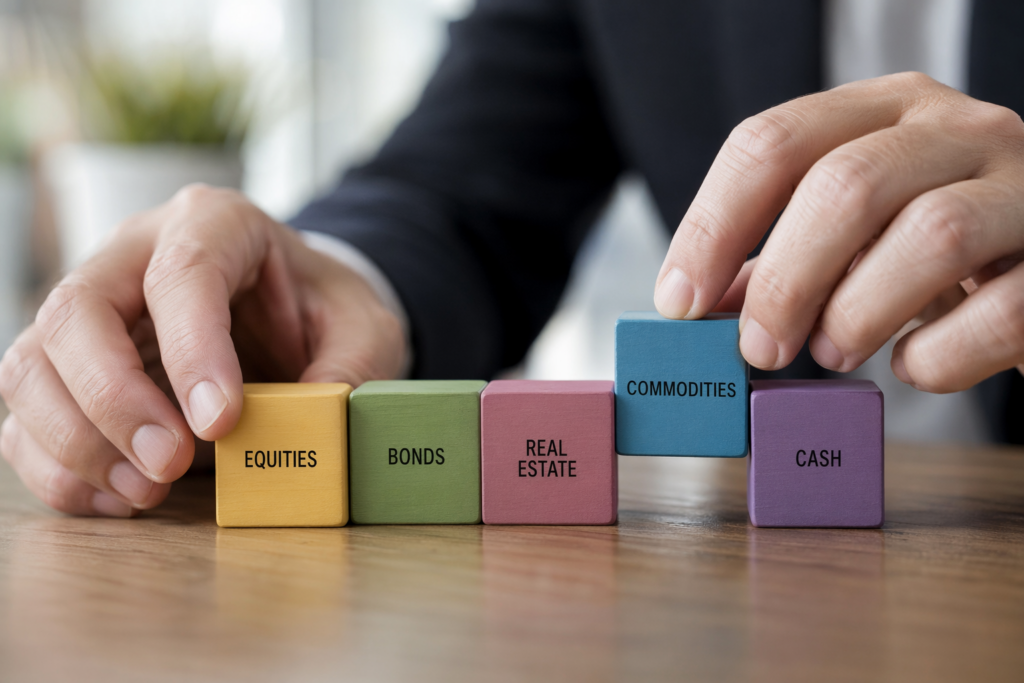
A successful dynamic portfolio rebalancing strategy starts with a clear asset allocation framework. Your investment portfolio should reflect return needs, risk capacity, liabilities, and long-term investment objectives. Without that foundation, rebalancing becomes mechanical instead of purposeful.
From there, the process depends on three components: flexible allocation rules, diversification, and explicit target ranges. These elements help a financial advisor decide when to act, where to source cash, and how to preserve alignment as market conditions shift. The following sections explain how each part supports stronger risk management and more durable portfolio oversight.
Asset Allocation Fundamentals and Flexibility
Asset allocation is the anchor for every rebalancing decision. It balances your desire for return with your willingness and ability to accept risk. In practice, that means matching the mix of equity, fixed income, cash, and other exposures to your investment goals and future obligations.
Flexibility matters because circumstances do not stay still. Wealth may rise faster than expected. Spending needs may remain modest. In those cases, a higher equity target could be appropriate, and the better choice may be to revise the policy rather than force the portfolio back to an outdated allocation.
A sound framework should include:
- Target weights for each major asset class
- Clear rebalancing bands around those targets
- Regular review of whether the policy still fits your objectives
So how often should you rebalance dynamically? Not by the calendar alone. Rebalancing should occur when drift becomes material or when your financial planning assumptions change enough to require a new alignment.
The Role of Diversification in Risk Management
Diversification is central to risk management because most investors have a lower risk tolerance than a fully equity-based strategy demands. A diversified portfolio spreads exposure across more than one asset class, often blending equities with fixed income and, in some cases, real estate or private market holdings.
As those components perform differently, portfolio weights drift. Left alone, the portfolio can gradually take on a very different risk profile from the one originally intended. Rebalancing restores that balance by trimming what has grown too large and adding to what has become too small.
This is also how dynamic portfolio rebalancing with defensive or safe-haven assets works in practice. When risk assets surge, their weights can dominate the portfolio. Rebalancing moves capital back toward stabilizing exposures such as fixed income, helping preserve diversification. For high net worth financial planning, that measured discipline can support steadier outcomes through changing markets.
Identifying and Setting Target Allocations
Target allocations should begin with your actual investment objectives, not generic model portfolios. A thoughtful process considers your liabilities, expected spending, philanthropic priorities, retirement planning horizon, and tolerance for drawdowns. That is why target-setting is both an art and a science.
Once targets are set, they need practical ranges. The compiled information points to two common structures: absolute bands at the major asset allocation level and relative bands at the sub-asset class level. That allows tighter control over core equity and fixed income exposure while giving smaller sleeves more room to compound.
This distinction helps explain the main types of portfolio rebalancing strategies. Calendar-based methods are more static. Threshold-based methods are considered dynamic because they respond to market conditions and portfolio drift. For a financial planner working with high net worth individuals, well-defined target allocations create the discipline needed to make that approach effective.
Leading Strategies for Dynamic Portfolio Rebalancing
There is no single model that fits every investor. Still, the strongest dynamic rebalancing strategy usually combines policy discipline with flexibility around market conditions, taxes, and liquidity. The main objective remains consistent: improve risk management by keeping exposure close to intended levels.
In practice, investors and advisors tend to rely on threshold-driven models, calendar-based reviews with opportunistic execution, and more advanced analytics that monitor volatility and correlation. Each has a role, but their effectiveness depends on how well they support the portfolio’s real purpose rather than trading for its own sake.
Threshold-Driven Rebalancing Models
Threshold-driven models trigger trades only when allocation moves outside preset bands. This makes them one of the clearest dynamic approaches because action is tied to actual drift, not the calendar. In periods of market volatility, that can reduce unnecessary turnover while still maintaining strong risk management.
The compiled information expresses a preference for this method. It suggests that bands should be wide enough to limit excessive trading, yet narrow enough to avoid a materially different risk profile. It also distinguishes between major asset allocation bands and sub-asset class ranges.
| Model Element | Example from the compiled information |
|---|---|
| Major asset class band | Rebalance when total equity moves 5% above or below target |
| Sub-asset class band | Use a relative band of +/-25% around target weights |
| Balanced Growth example | A 62.5% equity target would trigger at 57.5% or 67.5% |
| Sub-allocation example | A 10% target could trade within a 7.5% to 12.5% range |
For many high net worth families, this threshold-driven structure creates a practical balance between control, flexibility, and cost awareness.
Calendar-Based and Opportunistic Rebalancing
Calendar-based rebalancing resets allocations on a set schedule, such as quarterly or annually. The benefit is simplicity. The drawback is that it can produce trades regardless of whether the portfolio truly needs adjustment, which may increase transaction costs without improving results.
That is why opportunistic rebalancing can be more compelling. This approach reviews the portfolio regularly but acts only when drift, market moves, or liquidity events make trading worthwhile. In other words, you monitor on a schedule but execute with judgment.
Liquidity is a major factor here. Investors with private market exposures cannot easily trade those holdings, so public market equivalents may need to do more of the work. For retirement planning and wealth management, a financial advisor often combines calendar-based oversight with opportunistic action. That lets you stay attentive without turning the process into constant activity that creates avoidable cost or tax drag.
The Increasing Role of Advanced Analytics
Advanced analytics can improve dynamic portfolio rebalancing by using more recent market behavior to estimate volatility and correlation more accurately than long-term static averages. The compiled information shows that shorter-term measures often better reflect current market conditions, which can support more stable allocation decisions.
Reinforcement learning is one way investors and traders may build on that idea. In practical terms, it can be used to test how different allocation changes respond to changing inputs and to refine rebalancing choices over time. Its value is not in replacing judgment, but in helping identify patterns that static policies may miss.
Useful applications may include:
- Adjusting allocation weights as volatility changes
- Evaluating correlation shifts between major asset classes
- Supporting more responsive risk targeting over time
For sophisticated investors, these tools are promising. Still, the central principle remains unchanged: advanced analytics should strengthen discipline, not encourage overtrading or speculative behavior.
GUIDE: Investments Review
At Financial Synergies Wealth Advisors, we help high net worth individuals and high net worth families align portfolio strategy with behavior, liquidity, and long-term purpose. If you want a clearer view of how your current allocation fits your objectives, download our Investments Review guide.
Tax-Efficient Portfolio Rebalancing Strategies
For taxable investors, rebalancing cannot be separated from taxes. Selling appreciated positions may improve alignment, but it can also trigger capital gains and reduce after-tax compounding. That is why tax-efficient execution is a core part of a sound rebalancing framework.
A thoughtful process looks first for lower-cost ways to restore balance, then evaluates whether realizing gains is still justified by risk management needs. Tax loss harvesting, charitable transfers, and account-level asset location can all help. The next sections show how these methods support better financial planning for high net worth individuals.
Harvesting Tax Losses While Rebalancing
When rebalancing requires sales in taxable accounts, tax loss harvesting can offset part or all of the capital gains created by those trades. This is one of the most practical tax-efficient tools available because it reduces current tax cost without changing the broader purpose of the portfolio.
The compiled information also highlights other lower-cost sources of rebalancing before taxable sales become necessary. Investors who are still adding assets or receiving internal cash flows may be able to restore alignment without realizing gains at all.
Common tax-aware techniques include:
- Using new money to fund underweight asset classes
- Reinvesting dividends, interest, or private fund distributions strategically
- Selling taxable positions with losses to offset realized capital gains
These steps can preserve return profiles while keeping the portfolio connected to your investment goals. For a financial planner advising high net worth families, tax loss harvesting is most effective when integrated into a broader wealth management strategy rather than treated as a year-end exercise.
Balancing Capital Gains with Charitable Giving
Charitable giving can be an efficient way to manage capital gains during rebalancing. If philanthropy is already part of your financial goals, gifting appreciated shares may be more tax-smart than donating cash. That allows you to reduce embedded gain exposure while supporting causes that matter to you.
This approach works best when charitable planning is connected to your investment objectives from the start. Rather than treating giving as separate from portfolio management, it becomes one tool for improving overall efficiency and reshaping allocations.
For high net worth individuals, that coordination can be powerful. Appreciated securities can help trim overweight positions without the same immediate tax burden as selling first. A financial advisor who understands both financial planning and wealth management can align rebalancing decisions with charitable intent, creating a cleaner path toward long-term portfolio discipline and meaningful personal impact.
Smart Implementation for Taxable Accounts
Smart implementation in taxable accounts starts by looking across the full household balance sheet. If you hold both taxable and tax-advantaged accounts, you may be able to make allocation changes in retirement accounts first, reducing the need to realize gains in taxable holdings.
That cross-account view is especially useful when one asset class, such as large-cap U.S. stocks, becomes overweight. Selling those positions inside a tax-advantaged account may avoid current tax consequences, while taxable accounts can be preserved for holdings where selling would be more costly. This can also help manage transaction costs and keep overall risk management intact.
The main advantage for taxable investors is flexibility. Dynamic rebalancing gives you more ways to respond to drift without blindly triggering taxes. For high net worth financial planning, that means better alignment between asset location, portfolio structure, and after-tax outcomes. It is a disciplined method, not a shortcut, and that distinction matters.
Performance Enhancement: How Dynamic Rebalancing Elevates Returns
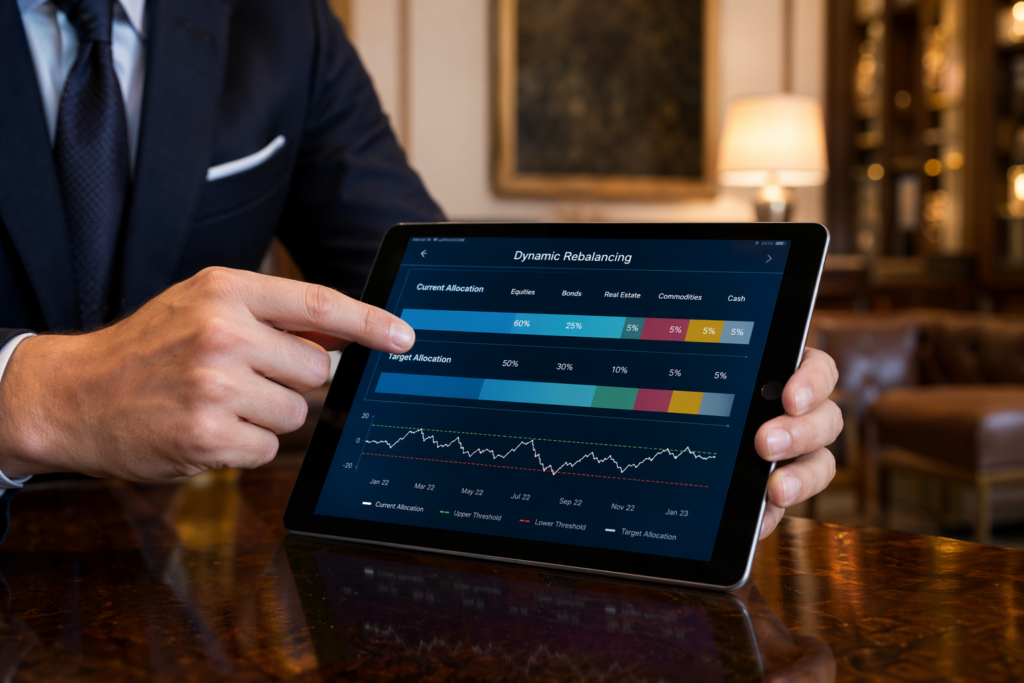
Dynamic portfolio rebalancing can support investment returns not by forecasting markets, but by improving portfolio discipline. It keeps exposures closer to plan, controls unintended drift, and creates opportunities to buy underweighted assets after market trends shift. That combination can enhance long-term performance.
The compiled information also notes that rebalancing tends to add the most value in volatile environments. When markets swing sharply, a disciplined dynamic rebalancing strategy may reduce drawdowns, preserve flexibility, and position the portfolio to respond more effectively after dislocations.
Mitigating Volatility and Capitalizing on Market Trends
One of the clearest benefits of a dynamic portfolio rebalancing strategy is its ability to limit downside risk when volatility rises. As stronger-performing assets grow beyond target weights, the portfolio may become more exposed than intended. Rebalancing helps prevent that gradual shift from becoming a larger problem.
It also works in a contrarian way. You trim positions that have appreciated and add to areas that have lagged. In periods of unstable market trends, that discipline can be valuable because it prevents your portfolio from leaning too heavily into what has already run up.
The compiled information gives a useful example: after a downturn, a previously rebalanced portfolio may hold relatively more fixed income, allowing it to buy equities at lower prices. That is how dynamic rebalancing with safe-haven assets can work. Defensive positioning is not permanent. It creates flexibility so you can restore target exposures when opportunities improve.
Real-Life Examples and Case Studies
The compiled information offers a practical case study. An investor with a $10 million investment portfolio held $6 million in equity and $4 million in fixed income, even though the desired asset allocation was 50/50. Rebalancing required selling $1 million of equity and accepting a tax cost, but it brought the portfolio back closer to its intended risk level.
In a later drawdown scenario, where equities fell 30% and fixed income rose 5%, the rebalanced portfolio declined less than the original overweight equity mix. It also ended with more flexibility to buy equities after prices dropped.
Key takeaways include:
- Dynamic portfolio balancing can reduce losses during stress periods
- A known tax cost may be smaller than the cost of excess risk
- Improved returns often come from better risk control, not more aggressive trading
For taxable investors, that trade-off is central. A skilled financial advisor weighs taxes against the larger impact of portfolio drift.
Safe-Haven Assets and Defensive Positioning
Safe-haven assets play a stabilizing role when equity exposure grows too large or market volatility increases. In the compiled information, fixed income serves that function. When risk assets rally, rebalancing directs part of the portfolio back toward defensive positioning, helping preserve the intended mix.
This matters because rebalancing is fundamentally about risk management. Taxes are real, but so are drawdowns. Letting a portfolio drift too far in pursuit of tax deferral can expose you to losses that outweigh the benefit of waiting to sell.
For high net worth families, defensive positioning should be strategic rather than emotional. Safe-haven assets are not there to eliminate risk altogether. They help maintain balance so the portfolio can weather stress and still act decisively afterward. In wealth management and retirement planning, that ability to stay invested with discipline is often what supports better long-term outcomes.
GUIDE: Investments Review
At Financial Synergies Wealth Advisors, we help high net worth individuals and high net worth families align portfolio strategy with behavior, liquidity, and long-term purpose. If you want a clearer view of how your current allocation fits your objectives, download our Investments Review guide.
Frequently Asked Questions
How frequently should dynamic rebalancing occur for optimal results?
Dynamic portfolio rebalancing should occur when portfolio weights drift materially from target or when your circumstances change, not simply on a fixed schedule. For optimal results, monitor regularly, then act based on market conditions, risk tolerance, tax impact, liquidity, and transaction costs rather than habit alone.
What are the primary risks associated with dynamic portfolio rebalancing?
The main risks of dynamic rebalancing include unnecessary trading, higher transaction costs, tax realization, and poor execution if market trends are misread. Still, the larger danger is often failing to control asset allocation drift, which can leave your portfolio carrying more risk than you originally intended.
What are the main types of portfolio rebalancing strategies?
The main portfolio rebalancing strategies are calendar-based and threshold-based. Calendar methods are more static because trades follow a schedule. Dynamic models include threshold bands, opportunistic execution, and some AI-driven approaches that adapt allocation decisions to market volatility, changing correlations, and more current risk signals.
What tax-efficient strategies are available for rebalancing an investment portfolio?
Tax-efficient options include using new cash flows, dividends, or distributions to rebalance, selling loss positions to offset capital gains through tax loss harvesting, gifting appreciated shares for charitable purposes, and making adjustments inside retirement accounts first. These methods can reduce tax drag in taxable accounts while preserving investment portfolio discipline.
A Truly Unique Wealth Management Experience
Let’s create a financial plan and investment strategy that allows you to live the life of your dreams. Schedule your free consultation today to explore tailored financial strategies designed to secure your future!
Concerns or questions about your tax situation or financial plan? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate markets and developing custom financial plans. To learn more about our approach to financial planning please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.