Consumer spending is the engine of the U.S. economy, accounting for roughly two-thirds of overall economic activity. In theory, when consumers feel financially secure and optimistic, they tend to spend more, driving corporate profits and economic growth. When they feel uncertain, they may tighten their belts. In reality, how consumers behave depends on many factors, especially because not all consumers are alike. For this reason, having a holistic understanding of the financial health of consumers is one of the most important ways for long-term investors to make sense of the current environment.
The picture today is positive but mixed. On one hand, household net worth is near record levels, the job market has improved, retail sales are strong, and gasoline prices are declining. On the other hand, consumer sentiment is near historic lows, savings rates have fallen sharply, debt levels remain elevated, and inflation continues to run above the Federal Reserve’s target.
These conflicting signals reflect an economy that is performing well in general, but is also leaving some households feeling stretched. For long-term investors, understanding both sides of this picture is important for understanding economic trends as well as the importance of following a financial plan.
Consumers are feeling pessimistic despite healthy growth
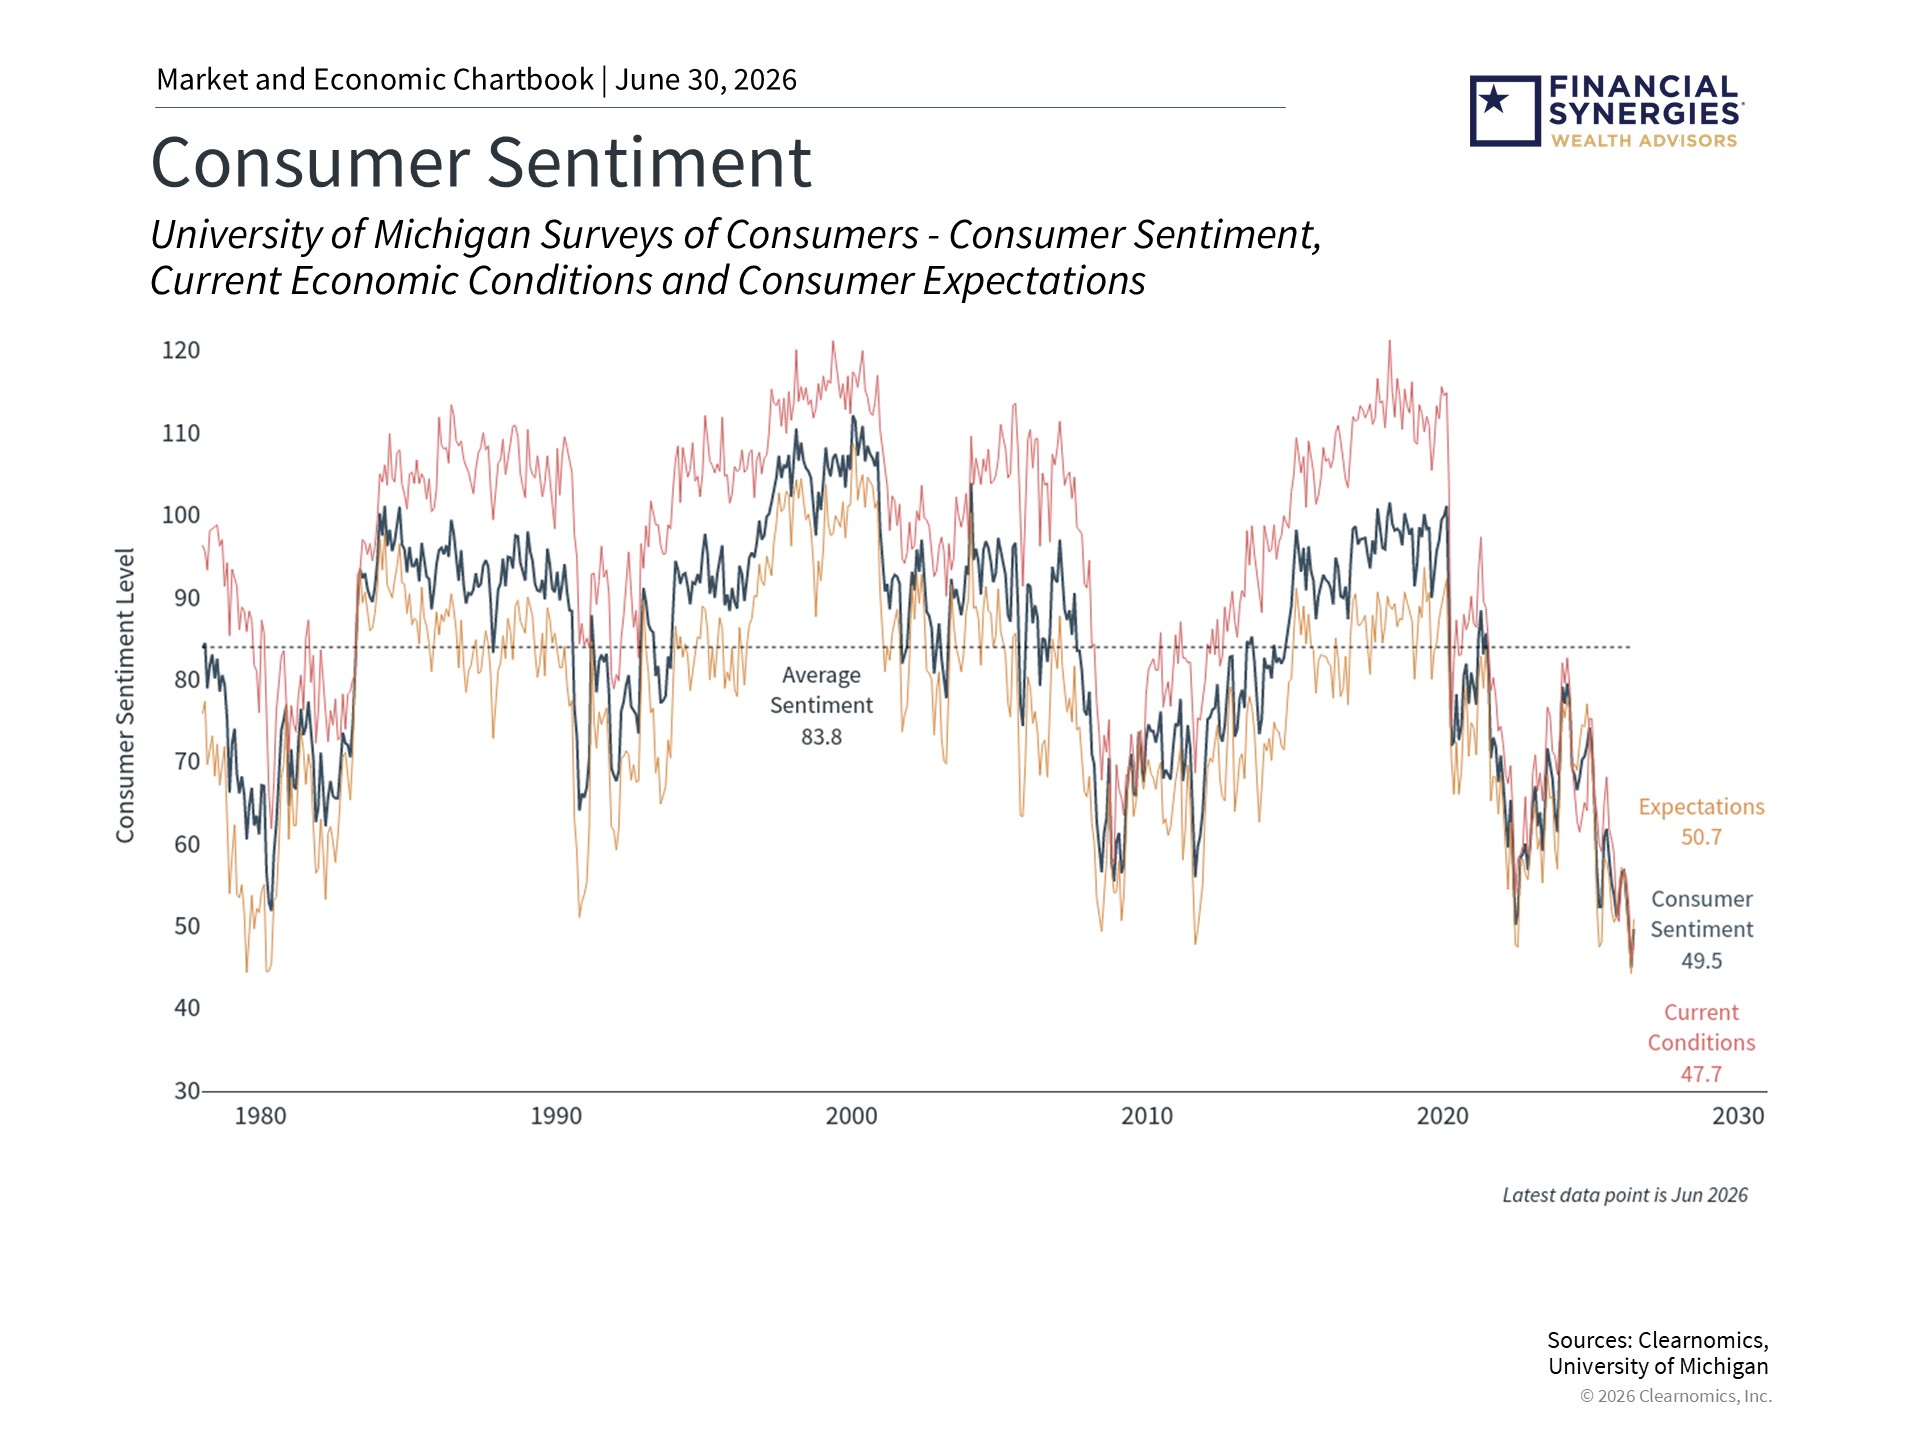
According to the University of Michigan Surveys of Consumers, the consumer sentiment index was 49.5 in June 2026, well below the historical average of 83.8. This places sentiment near its historic low, comparable to levels seen during the worst of the 2008 financial crisis and the early pandemic period. One-year inflation expectations from the same survey have climbed to 4.6%, suggesting that concerns about rising prices remain a primary driver of pessimism.1
While it seems that there should be a direct connection between how consumers feel and whether they are willing to spend, this is not always the case. After all, consumer sentiment figures are based on representative surveys, so there can be data challenges, as well as a difference between how people say they feel and how they are behaving. For instance, retail sales have grown 6.9% year-over-year in the latest report, well above the long-term historical average of 4.7%.2
What explains this gap? An important part of the answer is the inflation that consumers have experienced over the past several years. Even though the rate of inflation has improved, the level of prices for everyday goods and services remains much higher than before the pandemic. Consumers who feel the ongoing weight of higher grocery, housing, and energy bills may feel pessimistic in surveys even as they continue spending for necessities and some discretionary items.
Additionally, the job market, while showing signs of improvement, also carries uncertainty related to the potential impact of artificial intelligence on employment. Wage growth has also slowed even though it remains at a historically strong annual rate of 3.6%. The challenge is that this is below the recent inflation readings driven by energy prices. These concerns spanning many different areas may shape how households think about the future, even if they continue to make purchases.
Household net worth reflects the strength of the economy and markets
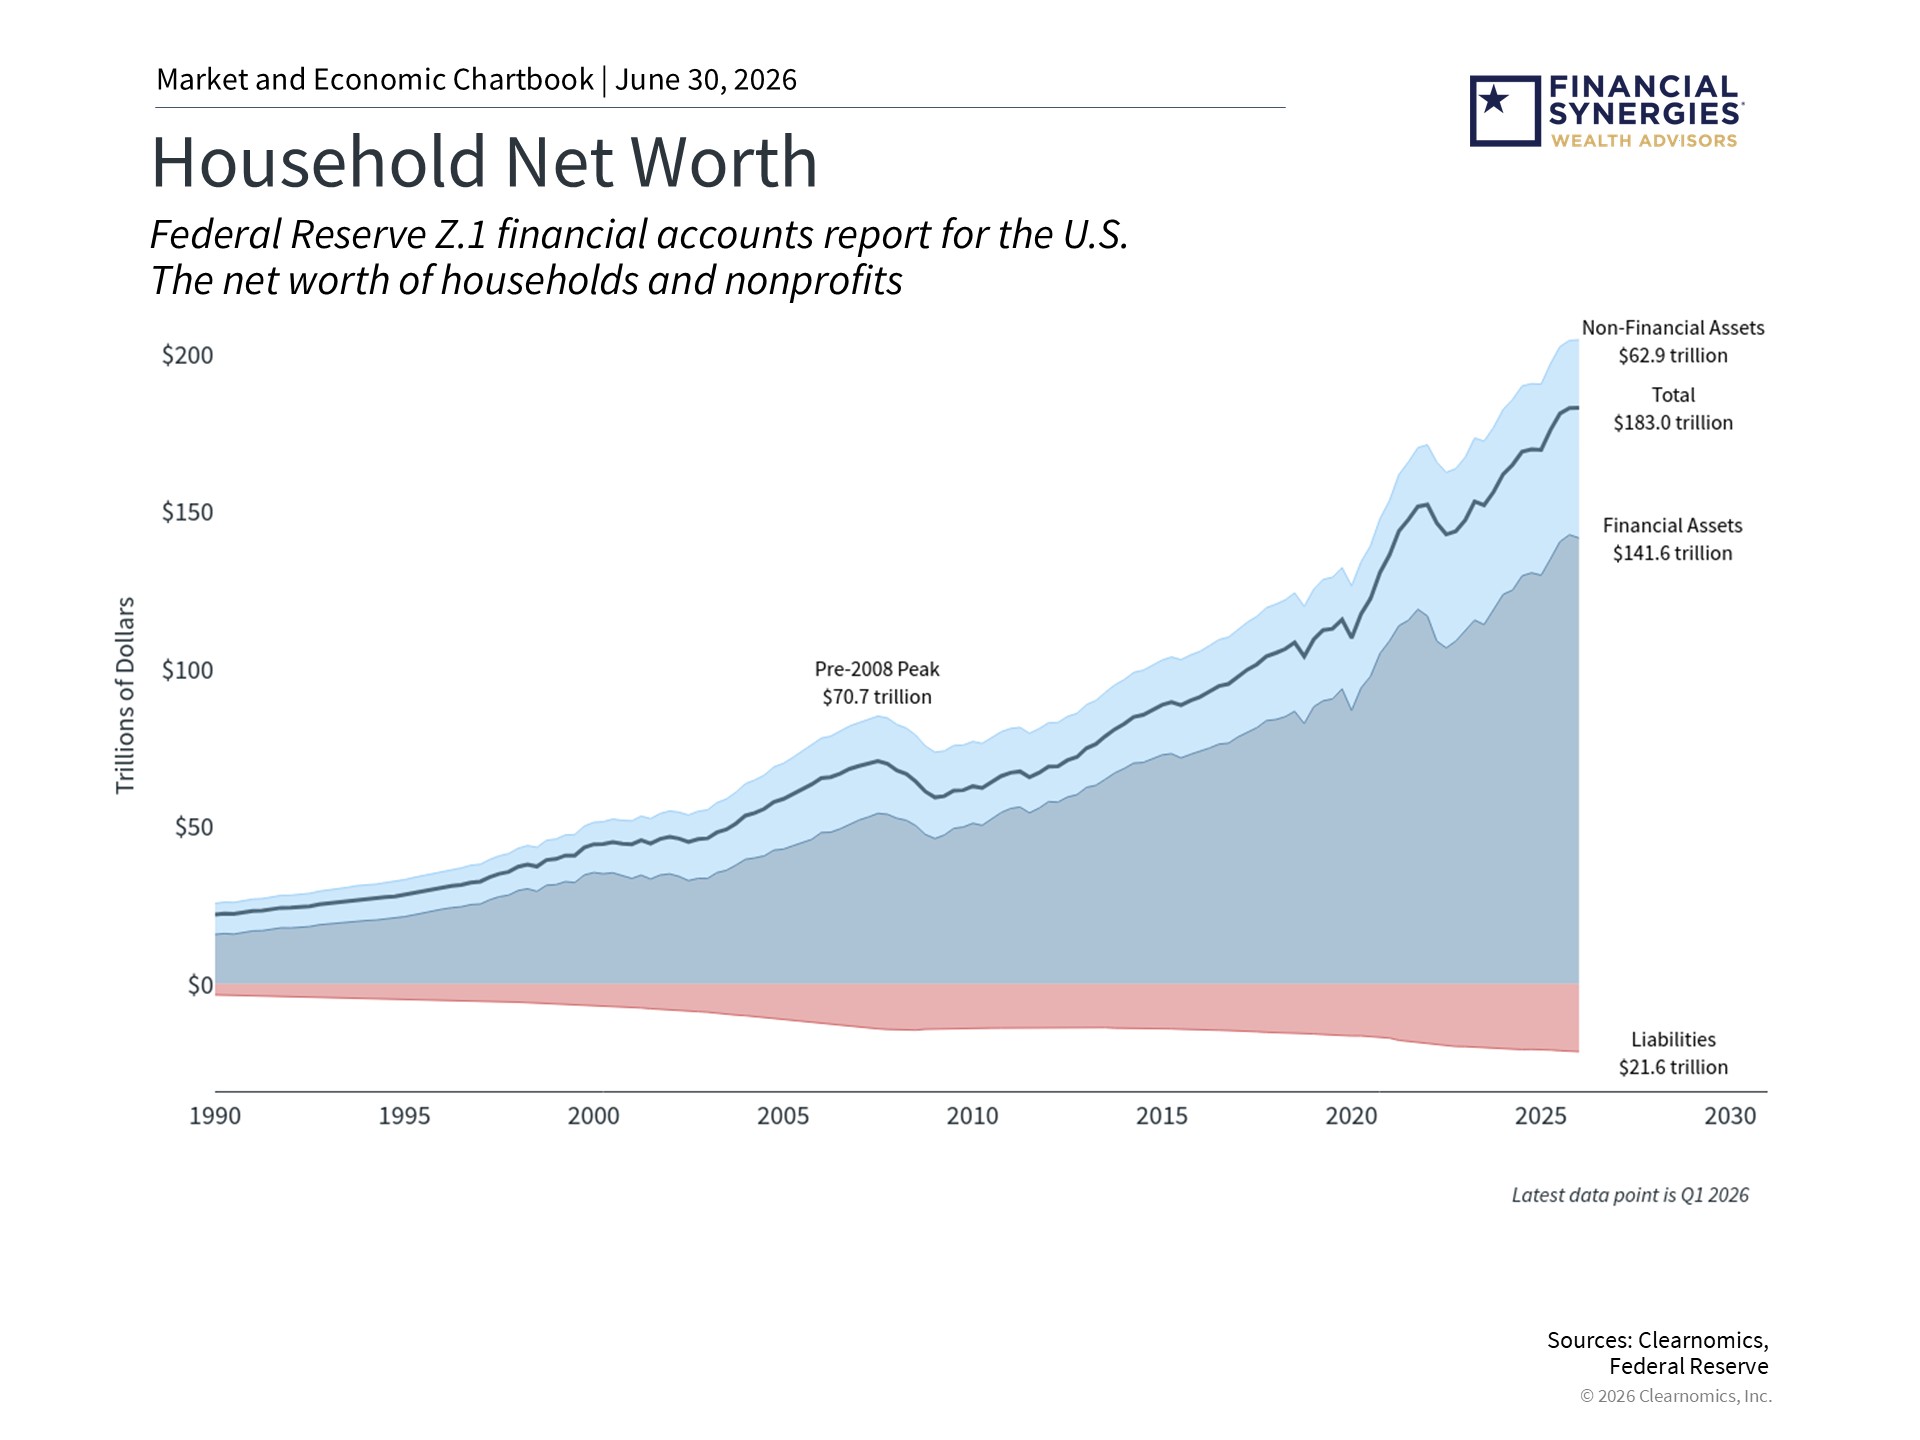
While sentiment is low, the overall balance sheet of American households has never been stronger. Total U.S. household net worth reached $183 trillion in the first quarter of 2026, a record high. Financial assets, including stocks and retirement accounts, have grown substantially over the current market cycle, driven by the stock market. Non-financial assets, such as homes, have also risen in value over the past several years.3
Of course, this masks the variation across income and wealth groups. A popular term right now, for instance, is that we have a “K-shaped” economy. Households with meaningful exposure to financial assets and real estate have seen their balance sheets strengthen considerably. For those without such assets, growth in wages has been strong, but they may also be experiencing higher debt levels which have been increasing steadily for the country as a whole. This includes credit card debt rising to $1.3 trillion, auto loans to $1.7 trillion, and student loan balances also climbing to $1.7 trillion.4
The wealth effect, or the tendency for consumers to spend more when they perceive themselves as wealthier, helps explain why aggregate spending has remained resilient even as sentiment has declined. This has different implications depending on the perspective we take. For the overall health of the economy, it’s preferable if many segments of the population are experiencing financial growth. When it comes to markets and portfolios, what primarily matters is the growth rate of earnings. So, while there may be challenges in some population segments, this does not necessarily mean it translates into a concern for investors.
Savings rates have declined
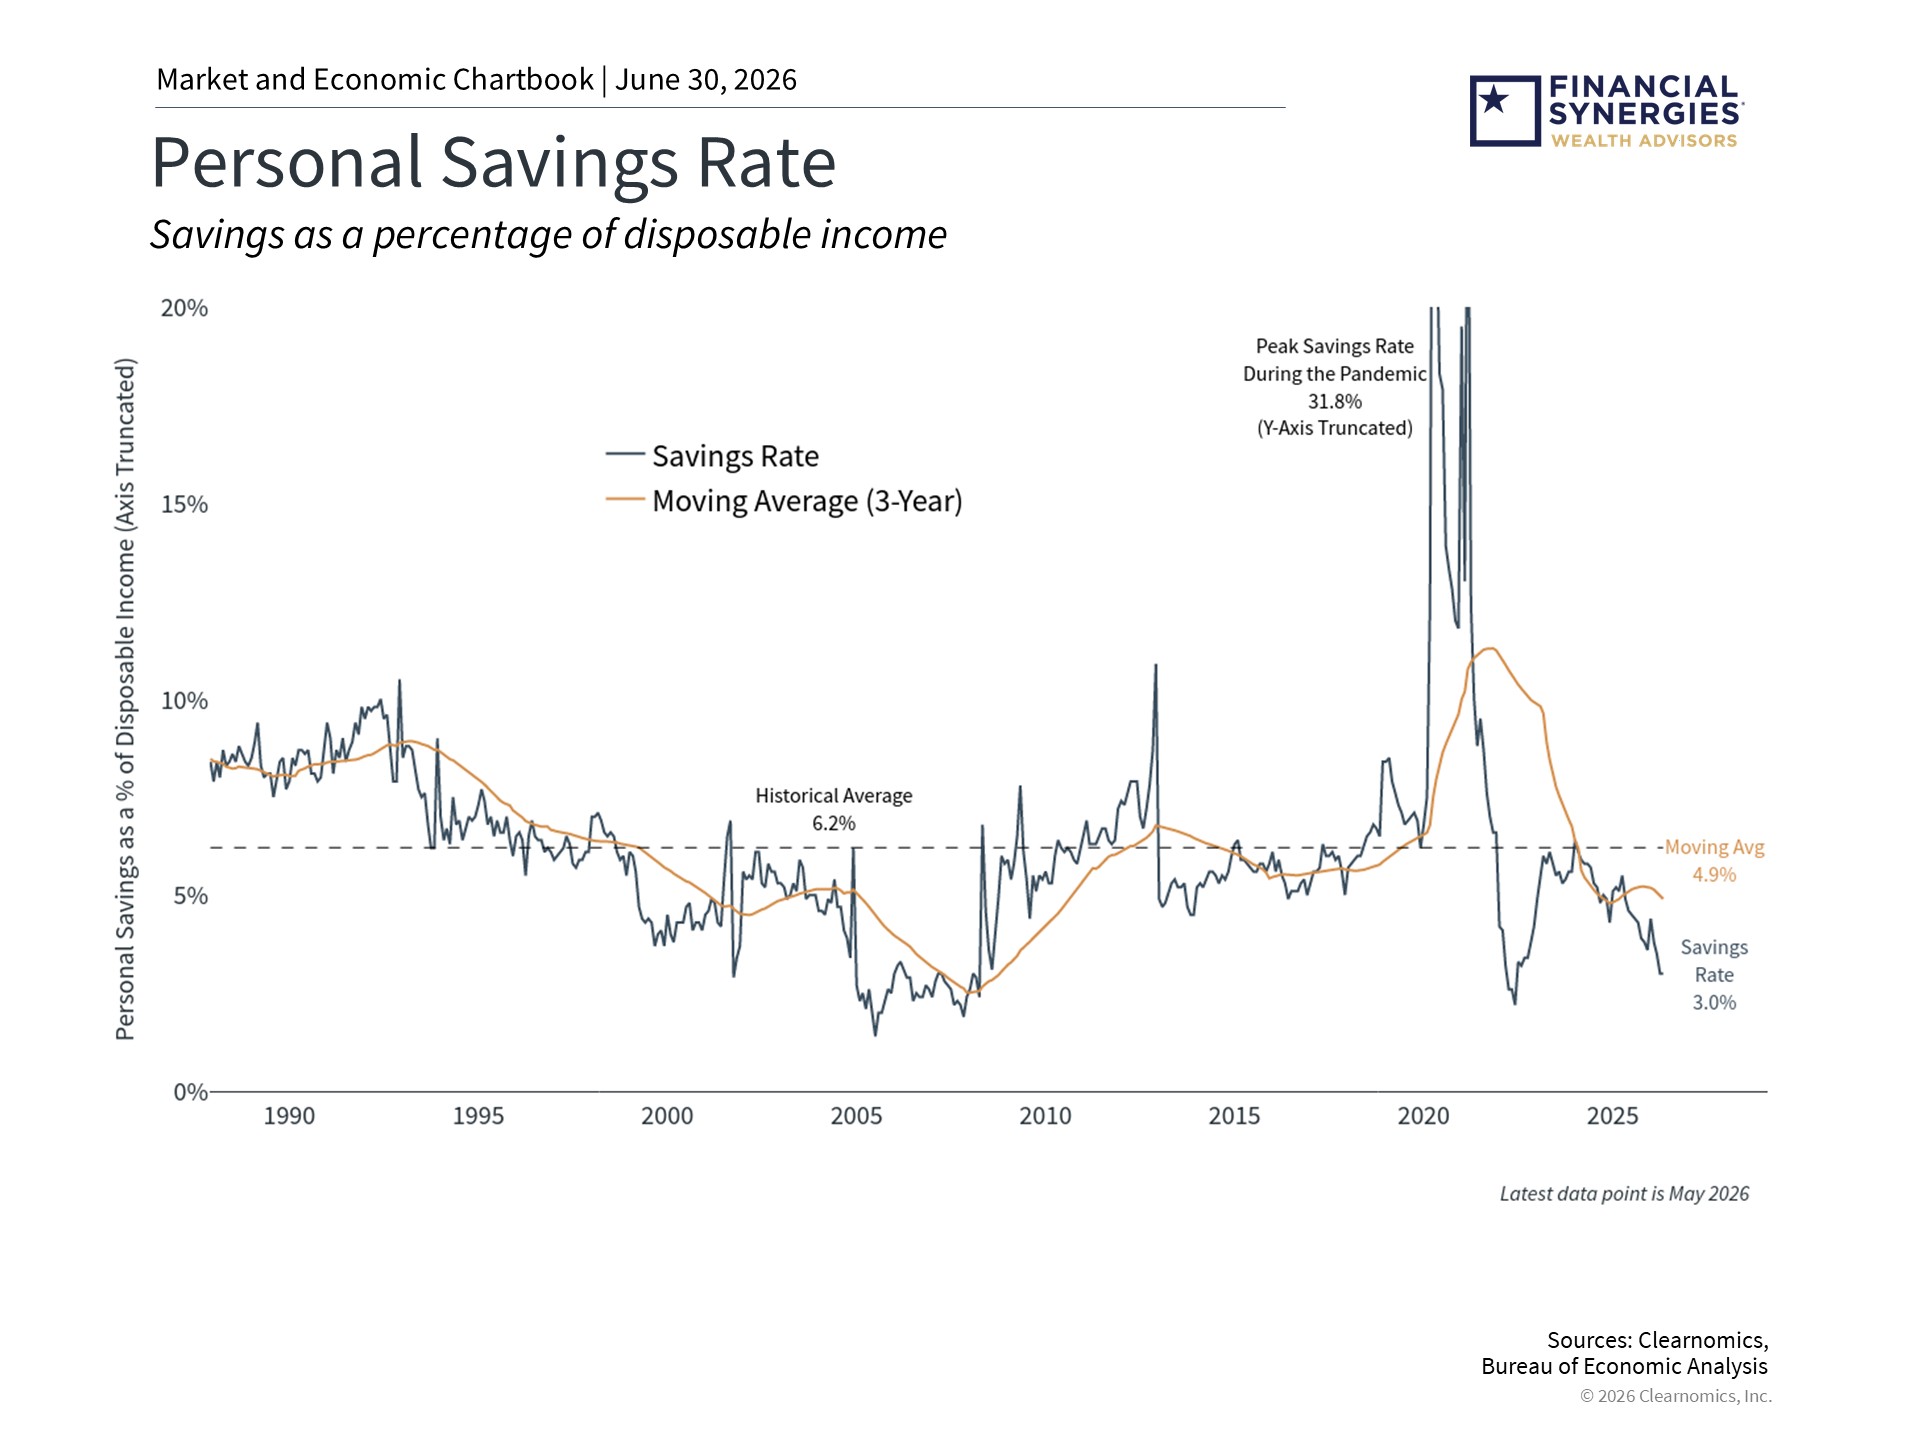
The personal savings rate, which measures the amount of after-tax disposable income that individuals save, has declined to 3.0%, well below the historical average of 6.2%. For much of the 20th century, this rate was much higher, averaging 11.1% from 1960 to 1990. Today’s rates are also a reversal of the pandemic period when they briefly surged above 30% as households received government support and had limited opportunities to spend.5
The reasons for this are again related to inflation and energy prices. Consumer spending has remained strong, which means that the average household has spent rather than saved. Higher prices, including for necessities such as gasoline, also reduce the portion of each paycheck available to set aside. Additionally, demographic trends play a role. As the Baby Boomer generation moves further into retirement, savings rates will naturally decline as they draw down accumulated wealth. These shifts in the population mean that it’s not surprising that the rate has declined over the past several decades.
A low savings rate of 3.0% may leave some households with limited buffers against unexpected expenses or life events. From a financial planning perspective, this is an important area of focus. For long-term investors, the power of compounding means that dollars set aside early in a financial plan grow substantially over decades.
Finally, from a broad market perspective, there are many trends moving in the right direction. For example, oil prices have fallen from recent highs which could provide some inflation relief and help ease some of the pressure that has weighed on consumer sentiment. The job market has also shown improvement in hiring activity, and unemployment remains low. These are positive developments for households and for the outlook for consumer finances.
The bottom line? Consumer spending has been resilient overall, supporting the economy and markets despite mixed signals. For investors, this reinforces both the importance of building a financial plan and staying focused on longer-term trends.
References
1. https://www.sca.isr.umich.edu
2. https://www.census.gov/retail/sales.html
3. https://www.federalreserve.gov/releases/z1
4. https://www.federalreserve.gov/econres/scfindex.htm
5. https://www.bea.gov/data/income-saving/personal-saving-rate
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Consumer Financial Health: Record Lows and Highs
Consumer spending is the engine of the U.S. economy, accounting for roughly two-thirds of overall economic activity. In theory, when consumers feel financially secure and optimistic, they tend to spend more, driving corporate profits and economic growth. When they feel uncertain, they may tighten their belts. In reality, how consumers behave depends on many factors, especially because not all consumers are alike. For this reason, having a holistic understanding of the financial health of consumers is one of the most important ways for long-term investors to make sense of the current environment.
The picture today is positive but mixed. On one hand, household net worth is near record levels, the job market has improved, retail sales are strong, and gasoline prices are declining. On the other hand, consumer sentiment is near historic lows, savings rates have fallen sharply, debt levels remain elevated, and inflation continues to run above the Federal Reserve’s target.
These conflicting signals reflect an economy that is performing well in general, but is also leaving some households feeling stretched. For long-term investors, understanding both sides of this picture is important for understanding economic trends as well as the importance of following a financial plan.
Consumers are feeling pessimistic despite healthy growth
According to the University of Michigan Surveys of Consumers, the consumer sentiment index was 49.5 in June 2026, well below the historical average of 83.8. This places sentiment near its historic low, comparable to levels seen during the worst of the 2008 financial crisis and the early pandemic period. One-year inflation expectations from the same survey have climbed to 4.6%, suggesting that concerns about rising prices remain a primary driver of pessimism.1
While it seems that there should be a direct connection between how consumers feel and whether they are willing to spend, this is not always the case. After all, consumer sentiment figures are based on representative surveys, so there can be data challenges, as well as a difference between how people say they feel and how they are behaving. For instance, retail sales have grown 6.9% year-over-year in the latest report, well above the long-term historical average of 4.7%.2
What explains this gap? An important part of the answer is the inflation that consumers have experienced over the past several years. Even though the rate of inflation has improved, the level of prices for everyday goods and services remains much higher than before the pandemic. Consumers who feel the ongoing weight of higher grocery, housing, and energy bills may feel pessimistic in surveys even as they continue spending for necessities and some discretionary items.
Additionally, the job market, while showing signs of improvement, also carries uncertainty related to the potential impact of artificial intelligence on employment. Wage growth has also slowed even though it remains at a historically strong annual rate of 3.6%. The challenge is that this is below the recent inflation readings driven by energy prices. These concerns spanning many different areas may shape how households think about the future, even if they continue to make purchases.
Household net worth reflects the strength of the economy and markets
While sentiment is low, the overall balance sheet of American households has never been stronger. Total U.S. household net worth reached $183 trillion in the first quarter of 2026, a record high. Financial assets, including stocks and retirement accounts, have grown substantially over the current market cycle, driven by the stock market. Non-financial assets, such as homes, have also risen in value over the past several years.3
Of course, this masks the variation across income and wealth groups. A popular term right now, for instance, is that we have a “K-shaped” economy. Households with meaningful exposure to financial assets and real estate have seen their balance sheets strengthen considerably. For those without such assets, growth in wages has been strong, but they may also be experiencing higher debt levels which have been increasing steadily for the country as a whole. This includes credit card debt rising to $1.3 trillion, auto loans to $1.7 trillion, and student loan balances also climbing to $1.7 trillion.4
The wealth effect, or the tendency for consumers to spend more when they perceive themselves as wealthier, helps explain why aggregate spending has remained resilient even as sentiment has declined. This has different implications depending on the perspective we take. For the overall health of the economy, it’s preferable if many segments of the population are experiencing financial growth. When it comes to markets and portfolios, what primarily matters is the growth rate of earnings. So, while there may be challenges in some population segments, this does not necessarily mean it translates into a concern for investors.
Savings rates have declined
The personal savings rate, which measures the amount of after-tax disposable income that individuals save, has declined to 3.0%, well below the historical average of 6.2%. For much of the 20th century, this rate was much higher, averaging 11.1% from 1960 to 1990. Today’s rates are also a reversal of the pandemic period when they briefly surged above 30% as households received government support and had limited opportunities to spend.5
The reasons for this are again related to inflation and energy prices. Consumer spending has remained strong, which means that the average household has spent rather than saved. Higher prices, including for necessities such as gasoline, also reduce the portion of each paycheck available to set aside. Additionally, demographic trends play a role. As the Baby Boomer generation moves further into retirement, savings rates will naturally decline as they draw down accumulated wealth. These shifts in the population mean that it’s not surprising that the rate has declined over the past several decades.
A low savings rate of 3.0% may leave some households with limited buffers against unexpected expenses or life events. From a financial planning perspective, this is an important area of focus. For long-term investors, the power of compounding means that dollars set aside early in a financial plan grow substantially over decades.
Finally, from a broad market perspective, there are many trends moving in the right direction. For example, oil prices have fallen from recent highs which could provide some inflation relief and help ease some of the pressure that has weighed on consumer sentiment. The job market has also shown improvement in hiring activity, and unemployment remains low. These are positive developments for households and for the outlook for consumer finances.
The bottom line? Consumer spending has been resilient overall, supporting the economy and markets despite mixed signals. For investors, this reinforces both the importance of building a financial plan and staying focused on longer-term trends.
References
1. https://www.sca.isr.umich.edu
2. https://www.census.gov/retail/sales.html
3. https://www.federalreserve.gov/releases/z1
4. https://www.federalreserve.gov/econres/scfindex.htm
5. https://www.bea.gov/data/income-saving/personal-saving-rate
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies:
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Retirement Income Risks: Planning for a Longer Life
What 7% Mortgages Mean for Housing and the Economy
Financial Synergies Named One of the Fastest Growing Private Companies in Houston
Subscribe to Our Blog
Chief Investment Officer | Managing Partner