A Tough Week for Stocks as the AI Trade Cools
Technology shares led a broad pullback that pushed the S&P 500 into correction territory, while high-quality bonds helped cushion the decline.
The Week in Brief
- The S&P 500 Index fell 8.6% this week, its worst week since April 2025, and ended the week more than 10% below its October record, a level investors commonly call a “correction.”
- Technology and AI-related companies drove most of the decline, even though NVIDIA reported quarterly results that beat Wall Street expectations.
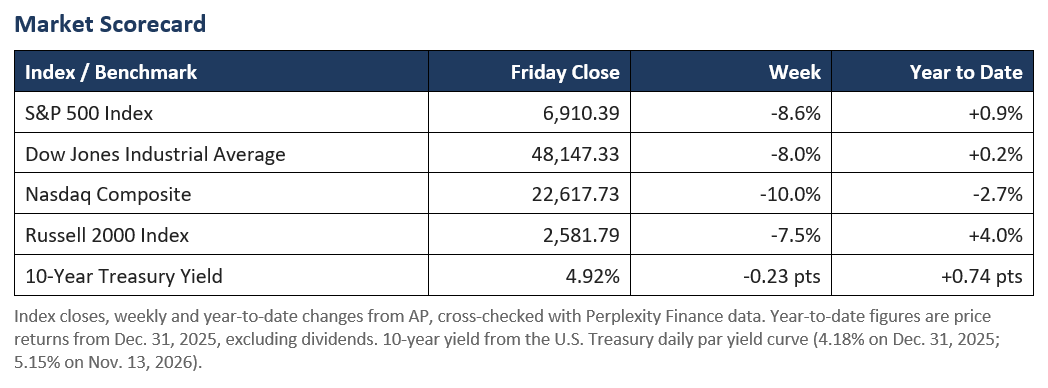
- Bond prices rose as investors looked for safety. The 10-year Treasury yield, a key benchmark for mortgage and borrowing rates, fell to 4.92% from 5.15%.
- The Federal Reserve signaled it may raise interest rates again in December, with inflation still running above its 2% goal.
Stocks
This was one of the more difficult weeks for stocks in recent memory. The S&P 500 Index fell 8.6%, the Dow Jones Industrial Average fell 8.0%, the Nasdaq Composite fell 10.0%, and the small-company Russell 2000 Index fell 7.5%. The S&P 500 declined all five days and closed Friday at 6,910, which leaves it up 0.9% for the year.
The selling centered on artificial intelligence. NVIDIA, the largest AI chipmaker, reported quarterly revenue of $115.8 billion and an outlook above analyst estimates, but its shares still fell about 23% for the week. On Friday, the shares fell about 14% after reports that regulators were looking into the company. Other chip and large technology stocks also fell, and the technology sector dropped about 12.5% for the week.
Anthropic, the company behind the Claude AI assistant, began trading Thursday after a closely watched initial public offering (IPO). Its shares opened well above the offering price but gave back part of those gains by Friday. Many investors appeared to treat the event as a reason to take profits in AI stocks rather than add to them.
There were bright spots. Defensive areas such as consumer staples and utilities held up much better, and several major retailers, including Walmart, Target, and TJX, reported solid results that pointed to steady consumer spending.
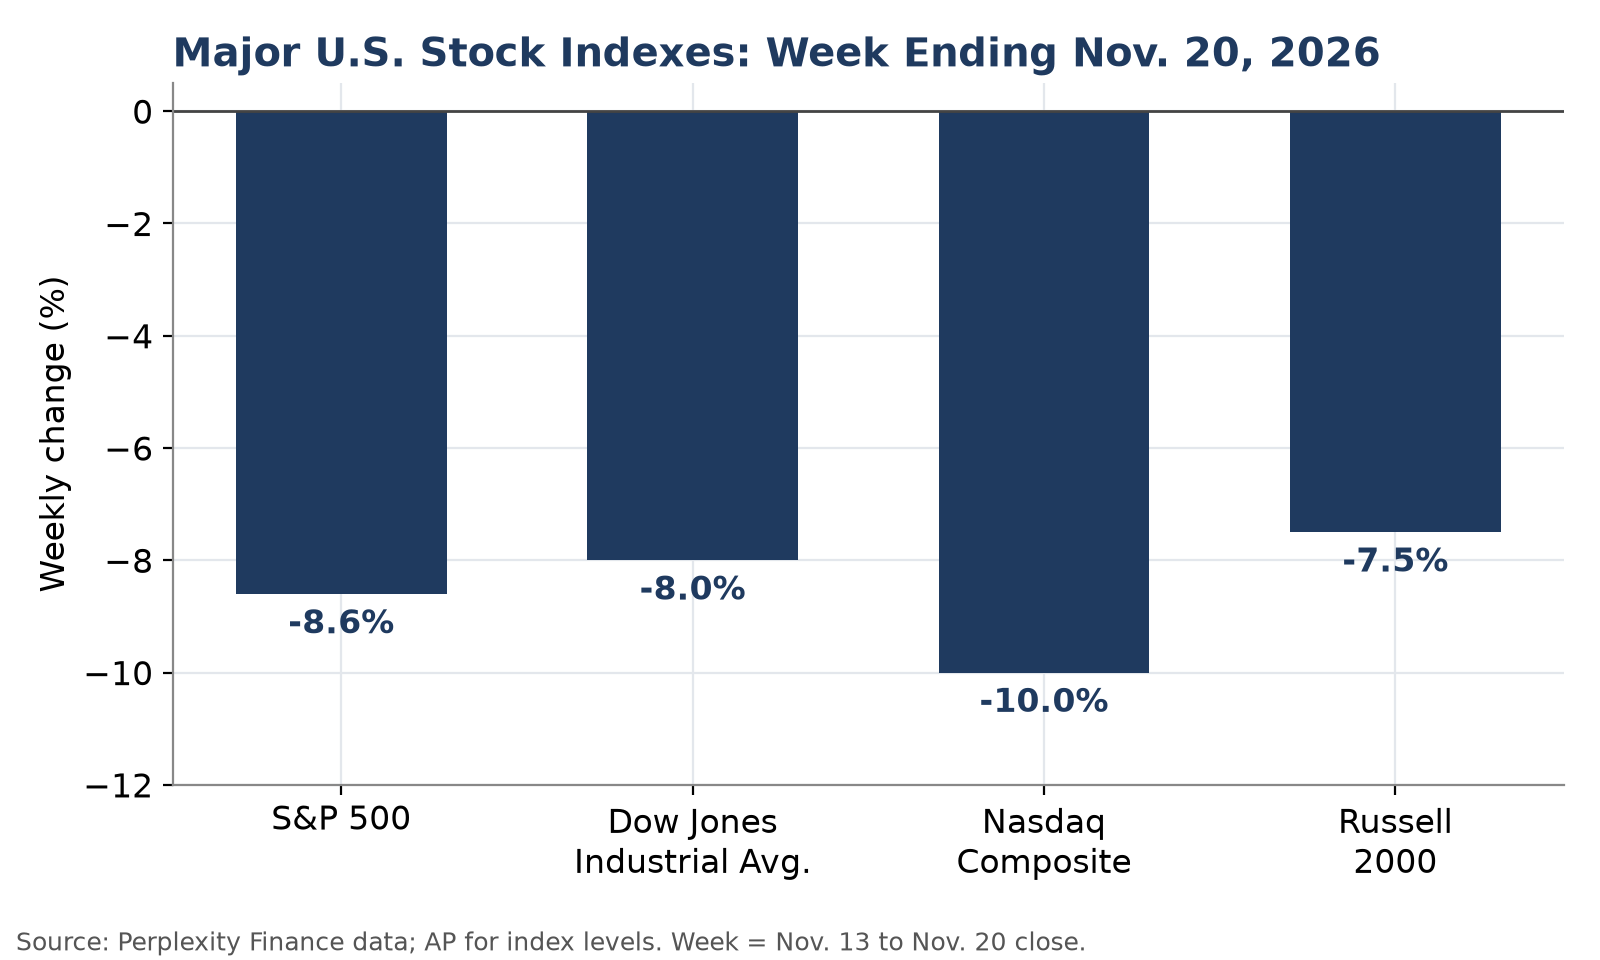
Chart 1. All four major U.S. stock indexes fell between 7.5% and 10.0% this week, with the technology-heavy Nasdaq down the most.
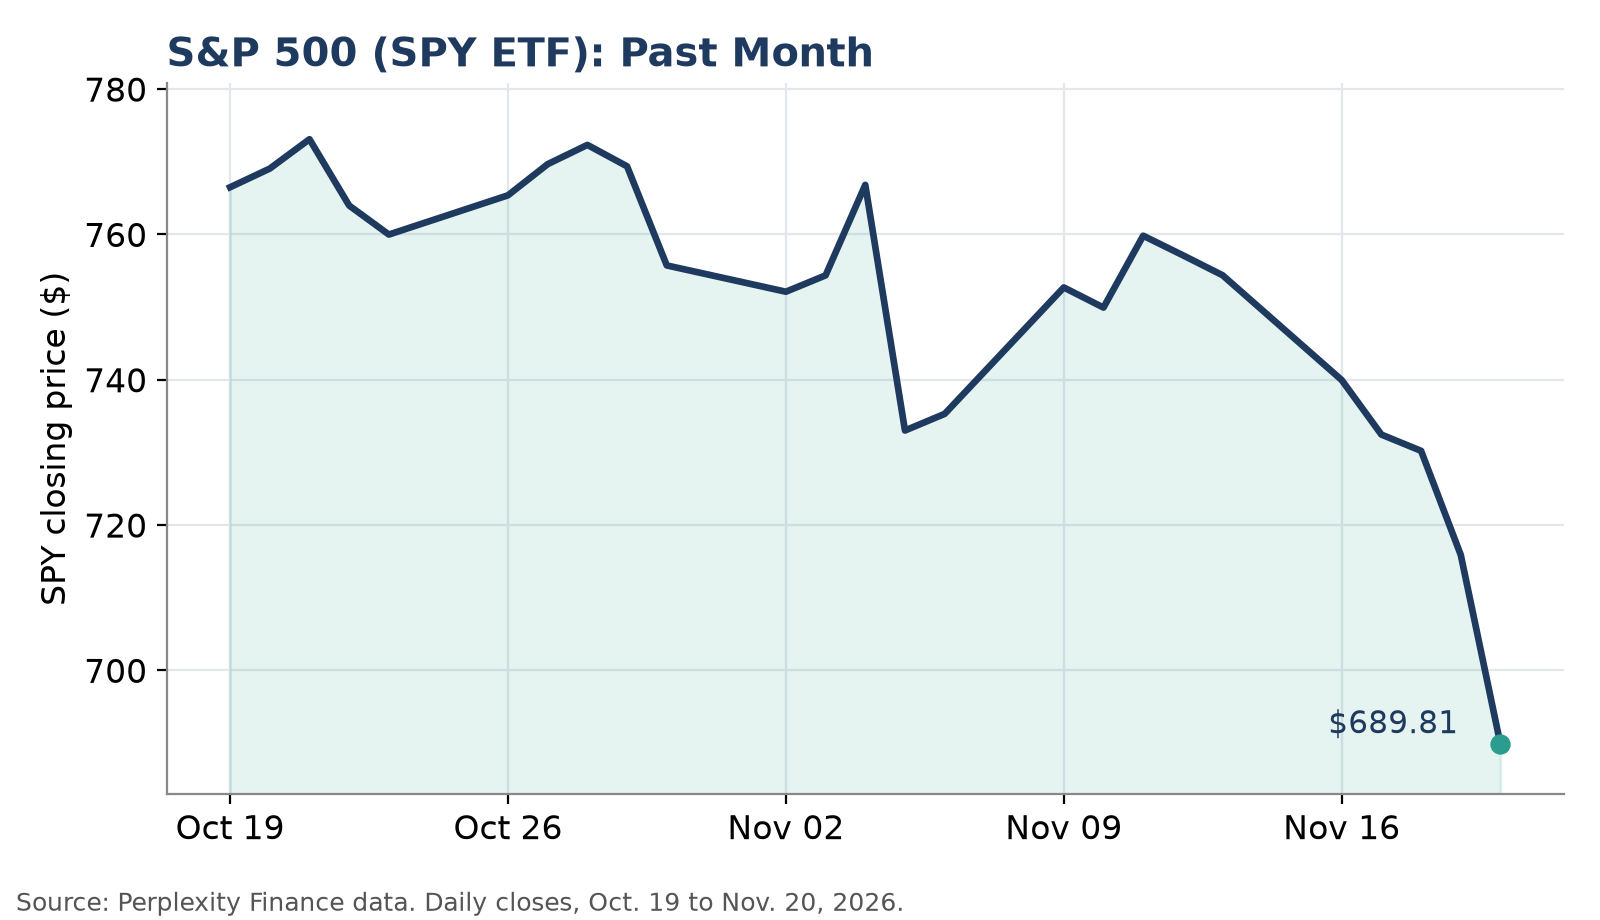
Chart 2. The S&P 500 (shown through the SPY ETF) fell every day this week and ended at its lowest level of the past month.
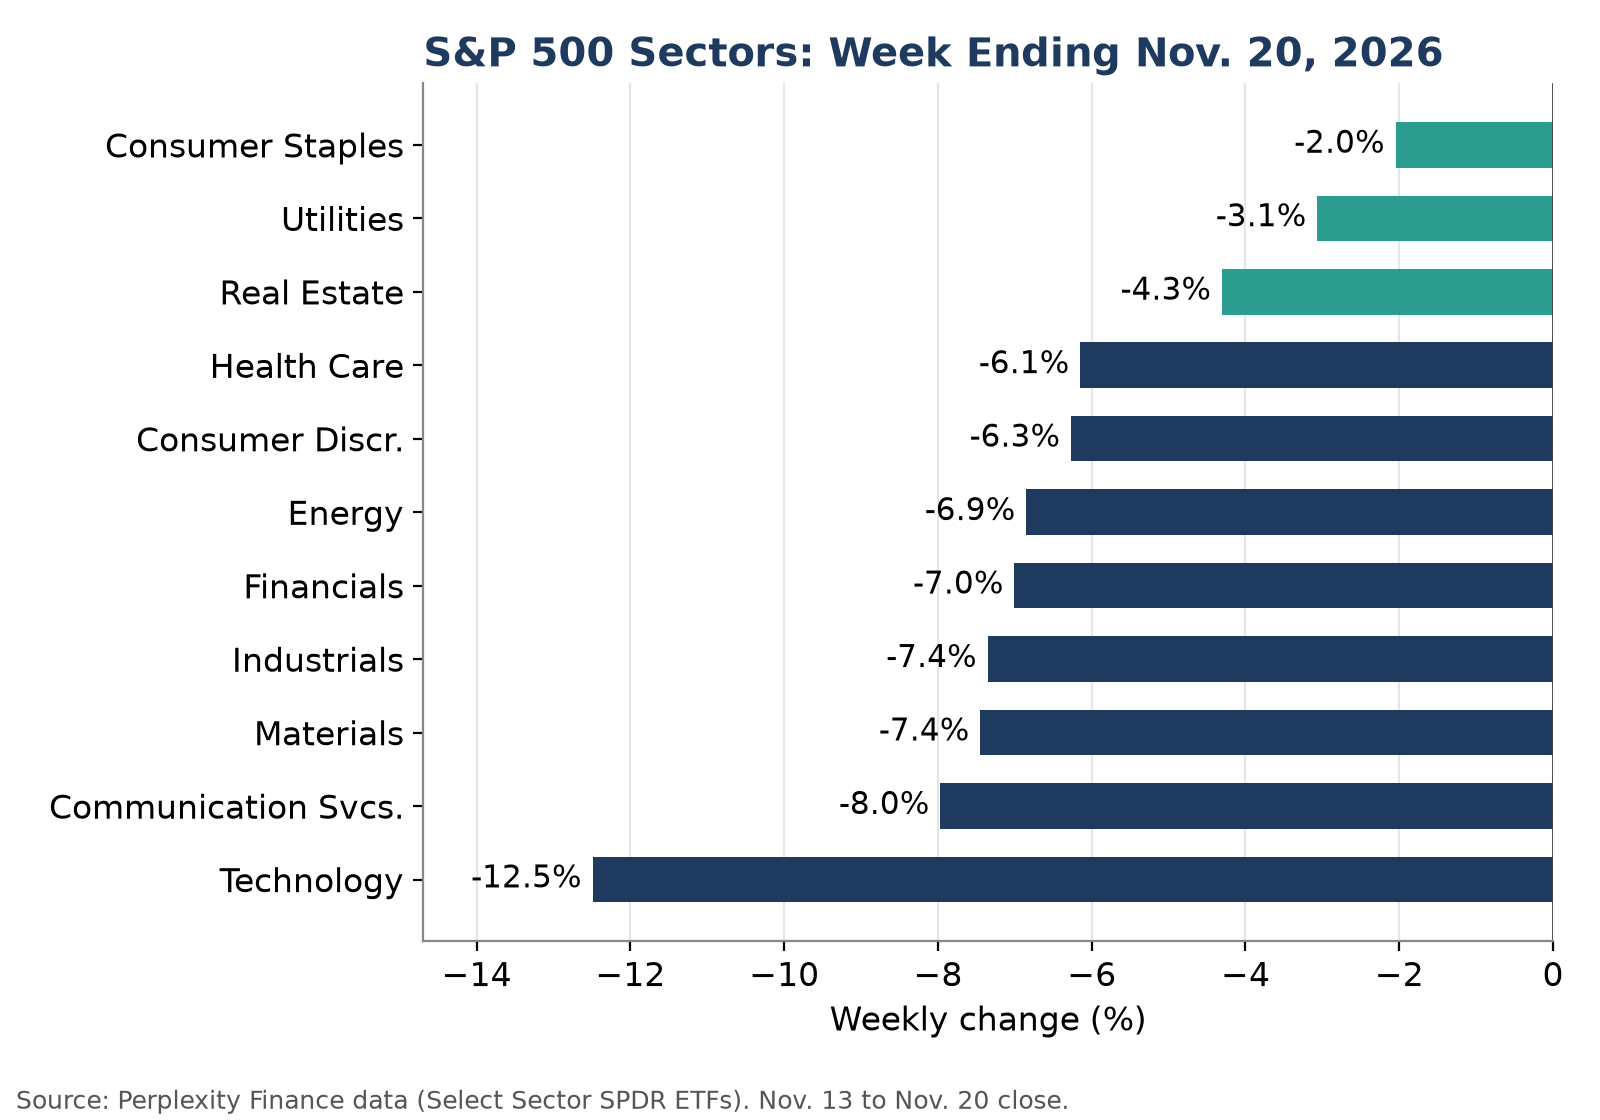
Chart 3. All 11 sectors declined, but defensive areas such as consumer staples and utilities fell far less than technology.
Bonds & Interest Rates
High-quality bonds did what they are designed to do in a diversified portfolio. As stocks fell, investors moved toward Treasuries, pushing bond prices up and yields down. The 10-year Treasury yield fell 0.23 percentage points to 4.92%, and the 2-year yield fell to 4.63% from 4.88%.
Investment-grade corporate bonds and long-term Treasuries gained for the week, while high-yield bonds dipped modestly. Even after this week’s decline, yields remain well above where they started the year, so new bond purchases continue to offer meaningful income.
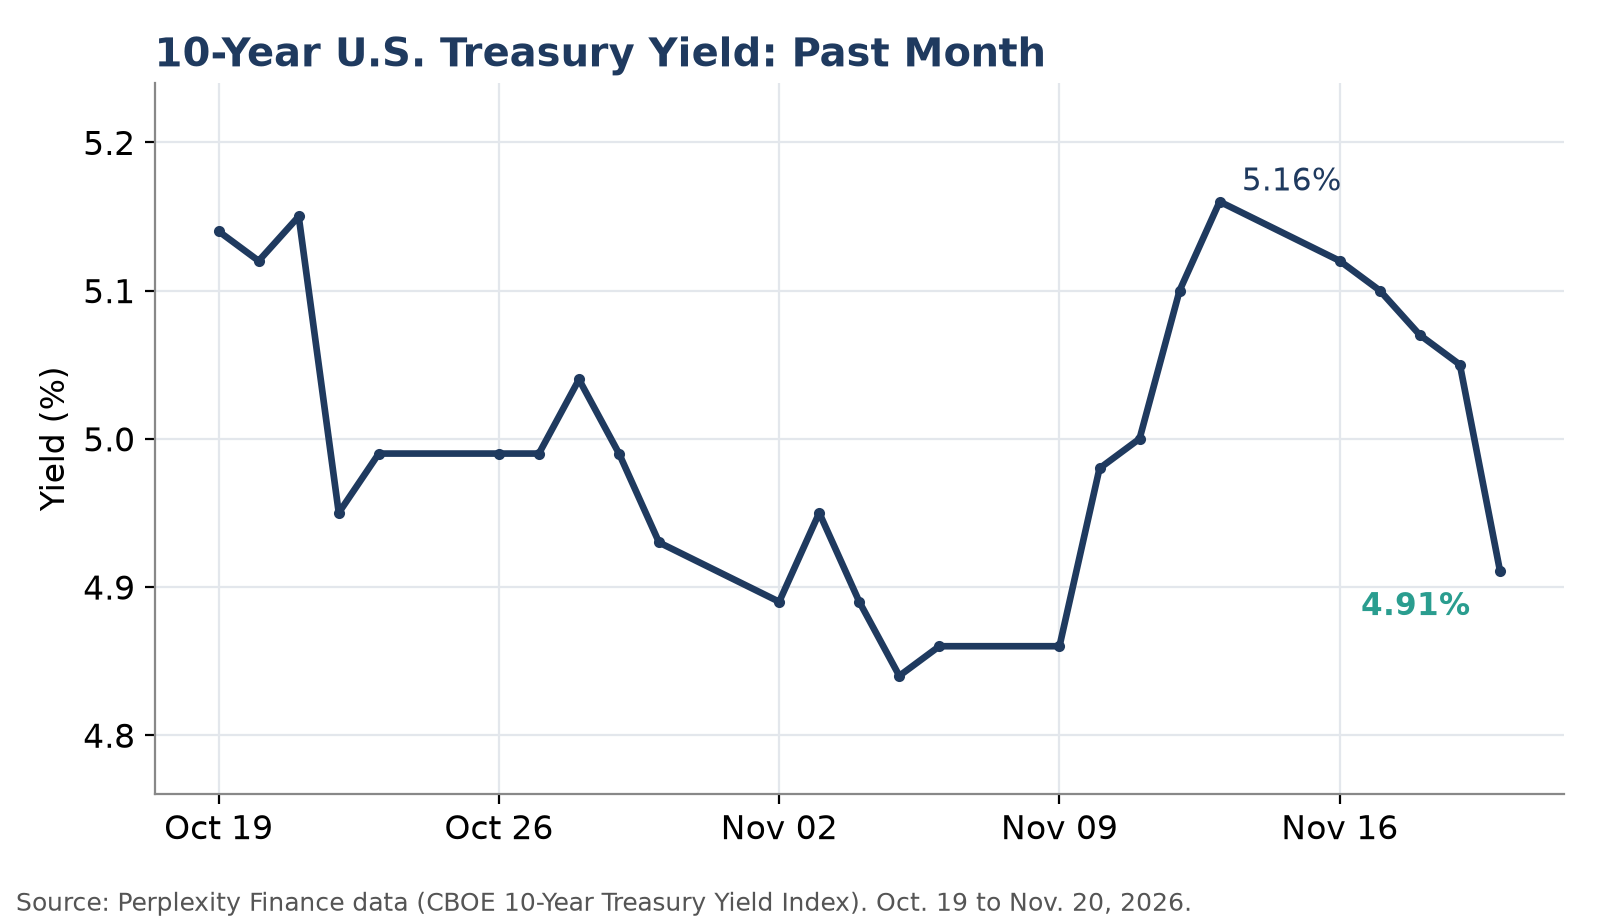
Chart 4. The 10-year Treasury yield fell back below 5% this week as investors moved toward the relative safety of Treasury bonds.
The Economy & the Fed
Economic reports this week were mixed but generally steady. Retail sales rose 0.2% in October, and a key measure that excludes volatile categories rose 0.6%. Weekly jobless claims stayed low at 203,000. Manufacturing surveys from New York and Philadelphia softened, and permits for new homes fell 7.4%, which reflects the impact of higher mortgage rates.
On the inflation front, a University of Michigan survey showed that consumers’ expectations for inflation over the next year fell to 3.7% from 4.7%. That is an encouraging sign, though inflation itself remains above the Fed’s target.
Minutes from the Fed’s October meeting showed that almost all officials see further rate increases as likely appropriate. Several Fed officials said this week they are open to raising rates at the December 8-9 meeting, and markets are pricing in a strong likelihood of an increase.
What We’re Watching This Week
- Wednesday, Nov. 25: the October Personal Consumption Expenditures (PCE) price index, the Fed’s preferred inflation measure, along with an updated estimate of third-quarter economic growth, durable goods orders, and the Fed’s Beige Book survey of regional business conditions.
- Tuesday, Nov. 24: consumer confidence and earnings from Dell and other technology companies.
- U.S. markets are closed Thursday for Thanksgiving and close early, at 1:00 p.m. ET, on Friday.
Our Perspective
Weeks like this one can be unsettling, especially after a strong run for technology stocks. It is worth remembering that pullbacks of 10% or more are a normal part of investing and have happened many times over the past several decades. Markets have historically recovered from them over time, though the timing is never predictable and past results do not guarantee future outcomes.
This week also showed the value of diversification. While technology shares fell sharply, high-quality bonds rose and defensive stock sectors held up comparatively well. Portfolios built across different asset classes are designed with weeks like this in mind.
Rather than reacting to short-term headlines, we continue to focus on your long-term plan, your time horizon, and your comfort with risk. Periods of volatility can also create opportunities to rebalance or harvest tax losses where appropriate. If you have questions about your portfolio, please reach out to your FSWA advisor. We are always glad to talk.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies Wealth Advisors:
Sources
AP via Yakima Herald-Republic: How major U.S. stock indexes fared (Nov. 20, 2026): https://www.yakimaherald.com/news/nation_and_world/business/how-major-us-stock-indexes-fared-friday-11-20-2026/article_963ce6d2-85a3-5fd6-981d-e60b72a58fbb.html
CNBC: Stock market news for Nov. 20, 2026: https://www.cnbc.com/2026/11/19/stock-market-today-live-updates.html
CNBC: Nvidia third-quarter earnings report (Nov. 17, 2026): https://www.cnbc.com/2026/11/17/nvidia-nvda-earnings-report-q3-2027.html
Fortune: Anthropic prices IPO at $83 per share (Nov. 18, 2026): https://fortune.com/2026/11/18/anthropic-prices-ipo-83-per-share-1-5-trillion/
CNN: Anthropic IPO live coverage (Nov. 19, 2026): https://edition.cnn.com/2026/11/19/business/live-news/anthropic-ipo?t=1795124558062
Investopedia: Markets news, Nov. 18, 2026: https://www.investopedia.com/stock-market-today-dow-jones-s-and-p-500-nasdaq-11182026-12261593
Morningstar/Dow Jones: Walmart raises fiscal-year guidance (Nov. 19, 2026): https://www.morningstar.com/news/dow-jones/202611194370/walmart-raises-fiscal-year-guidance-amid-3q-earnings-beat
U.S. Census Bureau: Advance Monthly Retail Sales: https://www.census.gov/retail/sales.html?source=forbes
MT Newswires via Fidelity: U.S. retail sales (Nov. 17, 2026): https://www.fidelity.com/news/article/us-economy/202611171514MIDNIGHTUSEQUITY_A3755926
Reuters: U.S. weekly jobless claims (Nov. 19, 2026): https://www.reuters.com/5f374b32b07b/world/us/us-weekly-jobless-claims-increase-slightly-2026-11-19
Morningstar/Dow Jones: U.S. housing starts (Nov. 18, 2026): https://www.morningstar.com/news/dow-jones/202611184459/us-housing-starts-climb-past-forecasts-in-october
CNBC: Stock market news for Nov. 19, 2026 (Philadelphia Fed survey): https://www.cnbc.com/2026/11/18/stock-market-today-live-updates.html?msockid=0693523f4e226c6808134a294f4a6dfc
University of Michigan: Surveys of Consumers: https://www.sca.isr.umich.edu/
MT Newswires via Fidelity: Consumer sentiment (Nov. 20, 2026): https://www.fidelity.com/news/article/default/202611201009MIDNIGHTUSEQUITY_A3758440
ABA Banking Journal: FOMC minutes (Nov. 2026): https://bankingjournal.aba.com/2026/11/fomc-minutes-show-close-call-over-possible-rate-hike/
CNBC: Stock market news for Nov. 18, 2026 (FOMC minutes): https://www.cnbc.com/2026/11/17/stock-market-today-live-updates.html?msockid=2e6a2f0927846bd00d94371c26da6ab4
StockTitan: Earnings and economic calendar, week of Nov. 23, 2026: https://www.stocktitan.net/articles/earnings-calendar-week-of-november-23-2026
CMC Markets: The week ahead (Nov. 23, 2026): https://www.cmcmarkets.com/en-gb/news-and-analysis/the-week-ahead-global-pmis-us-pce-dell-earnings
U.S. Treasury: Daily Treasury par yield curve rates: https://home.treasury.gov/resource-center/data-chart-center/interest-rates/daily-treasury-rates.csv/2026/all?type=daily_treasury_yield_curve
Perplexity Finance: index, ETF, yield, and sector data: https://www.perplexity.ai/finance
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
 Skip to content

Weekly Market Recap – A Tough Week for Stocks as the AI Trade Cools
A Tough Week for Stocks as the AI Trade Cools
Technology shares led a broad pullback that pushed the S&P 500 into correction territory, while high-quality bonds helped cushion the decline.
The Week in Brief
Stocks
This was one of the more difficult weeks for stocks in recent memory. The S&P 500 Index fell 8.6%, the Dow Jones Industrial Average fell 8.0%, the Nasdaq Composite fell 10.0%, and the small-company Russell 2000 Index fell 7.5%. The S&P 500 declined all five days and closed Friday at 6,910, which leaves it up 0.9% for the year.
The selling centered on artificial intelligence. NVIDIA, the largest AI chipmaker, reported quarterly revenue of $115.8 billion and an outlook above analyst estimates, but its shares still fell about 23% for the week. On Friday, the shares fell about 14% after reports that regulators were looking into the company. Other chip and large technology stocks also fell, and the technology sector dropped about 12.5% for the week.
Anthropic, the company behind the Claude AI assistant, began trading Thursday after a closely watched initial public offering (IPO). Its shares opened well above the offering price but gave back part of those gains by Friday. Many investors appeared to treat the event as a reason to take profits in AI stocks rather than add to them.
There were bright spots. Defensive areas such as consumer staples and utilities held up much better, and several major retailers, including Walmart, Target, and TJX, reported solid results that pointed to steady consumer spending.
Chart 1. All four major U.S. stock indexes fell between 7.5% and 10.0% this week, with the technology-heavy Nasdaq down the most.
Chart 2. The S&P 500 (shown through the SPY ETF) fell every day this week and ended at its lowest level of the past month.
Chart 3. All 11 sectors declined, but defensive areas such as consumer staples and utilities fell far less than technology.
Bonds & Interest Rates
High-quality bonds did what they are designed to do in a diversified portfolio. As stocks fell, investors moved toward Treasuries, pushing bond prices up and yields down. The 10-year Treasury yield fell 0.23 percentage points to 4.92%, and the 2-year yield fell to 4.63% from 4.88%.
Investment-grade corporate bonds and long-term Treasuries gained for the week, while high-yield bonds dipped modestly. Even after this week’s decline, yields remain well above where they started the year, so new bond purchases continue to offer meaningful income.
Chart 4. The 10-year Treasury yield fell back below 5% this week as investors moved toward the relative safety of Treasury bonds.
The Economy & the Fed
Economic reports this week were mixed but generally steady. Retail sales rose 0.2% in October, and a key measure that excludes volatile categories rose 0.6%. Weekly jobless claims stayed low at 203,000. Manufacturing surveys from New York and Philadelphia softened, and permits for new homes fell 7.4%, which reflects the impact of higher mortgage rates.
On the inflation front, a University of Michigan survey showed that consumers’ expectations for inflation over the next year fell to 3.7% from 4.7%. That is an encouraging sign, though inflation itself remains above the Fed’s target.
Minutes from the Fed’s October meeting showed that almost all officials see further rate increases as likely appropriate. Several Fed officials said this week they are open to raising rates at the December 8-9 meeting, and markets are pricing in a strong likelihood of an increase.
What We’re Watching This Week
Our Perspective
Weeks like this one can be unsettling, especially after a strong run for technology stocks. It is worth remembering that pullbacks of 10% or more are a normal part of investing and have happened many times over the past several decades. Markets have historically recovered from them over time, though the timing is never predictable and past results do not guarantee future outcomes.
This week also showed the value of diversification. While technology shares fell sharply, high-quality bonds rose and defensive stock sectors held up comparatively well. Portfolios built across different asset classes are designed with weeks like this in mind.
Rather than reacting to short-term headlines, we continue to focus on your long-term plan, your time horizon, and your comfort with risk. Periods of volatility can also create opportunities to rebalance or harvest tax losses where appropriate. If you have questions about your portfolio, please reach out to your FSWA advisor. We are always glad to talk.
Concerns or questions about how your investment portfolio will hold up in the current market environment? Contact Financial Synergies today.
We are a boutique, financial advisory and total wealth management firm with over 35 years helping clients navigate turbulent markets. To learn more about our approach to investment management and financial planning, please reach out to us. One of our seasoned advisors would be happy to help you build a custom financial plan to help ensure you accomplish your financial goals and objectives. Schedule a conversation with us today.
More relevant articles by Financial Synergies Wealth Advisors:
Sources
AP via Yakima Herald-Republic: How major U.S. stock indexes fared (Nov. 20, 2026): https://www.yakimaherald.com/news/nation_and_world/business/how-major-us-stock-indexes-fared-friday-11-20-2026/article_963ce6d2-85a3-5fd6-981d-e60b72a58fbb.html
CNBC: Stock market news for Nov. 20, 2026: https://www.cnbc.com/2026/11/19/stock-market-today-live-updates.html
CNBC: Nvidia third-quarter earnings report (Nov. 17, 2026): https://www.cnbc.com/2026/11/17/nvidia-nvda-earnings-report-q3-2027.html
Fortune: Anthropic prices IPO at $83 per share (Nov. 18, 2026): https://fortune.com/2026/11/18/anthropic-prices-ipo-83-per-share-1-5-trillion/
CNN: Anthropic IPO live coverage (Nov. 19, 2026): https://edition.cnn.com/2026/11/19/business/live-news/anthropic-ipo?t=1795124558062
Investopedia: Markets news, Nov. 18, 2026: https://www.investopedia.com/stock-market-today-dow-jones-s-and-p-500-nasdaq-11182026-12261593
Morningstar/Dow Jones: Walmart raises fiscal-year guidance (Nov. 19, 2026): https://www.morningstar.com/news/dow-jones/202611194370/walmart-raises-fiscal-year-guidance-amid-3q-earnings-beat
U.S. Census Bureau: Advance Monthly Retail Sales: https://www.census.gov/retail/sales.html?source=forbes
MT Newswires via Fidelity: U.S. retail sales (Nov. 17, 2026): https://www.fidelity.com/news/article/us-economy/202611171514MIDNIGHTUSEQUITY_A3755926
Reuters: U.S. weekly jobless claims (Nov. 19, 2026): https://www.reuters.com/5f374b32b07b/world/us/us-weekly-jobless-claims-increase-slightly-2026-11-19
Morningstar/Dow Jones: U.S. housing starts (Nov. 18, 2026): https://www.morningstar.com/news/dow-jones/202611184459/us-housing-starts-climb-past-forecasts-in-october
CNBC: Stock market news for Nov. 19, 2026 (Philadelphia Fed survey): https://www.cnbc.com/2026/11/18/stock-market-today-live-updates.html?msockid=0693523f4e226c6808134a294f4a6dfc
University of Michigan: Surveys of Consumers: https://www.sca.isr.umich.edu/
MT Newswires via Fidelity: Consumer sentiment (Nov. 20, 2026): https://www.fidelity.com/news/article/default/202611201009MIDNIGHTUSEQUITY_A3758440
ABA Banking Journal: FOMC minutes (Nov. 2026): https://bankingjournal.aba.com/2026/11/fomc-minutes-show-close-call-over-possible-rate-hike/
CNBC: Stock market news for Nov. 18, 2026 (FOMC minutes): https://www.cnbc.com/2026/11/17/stock-market-today-live-updates.html?msockid=2e6a2f0927846bd00d94371c26da6ab4
StockTitan: Earnings and economic calendar, week of Nov. 23, 2026: https://www.stocktitan.net/articles/earnings-calendar-week-of-november-23-2026
CMC Markets: The week ahead (Nov. 23, 2026): https://www.cmcmarkets.com/en-gb/news-and-analysis/the-week-ahead-global-pmis-us-pce-dell-earnings
U.S. Treasury: Daily Treasury par yield curve rates: https://home.treasury.gov/resource-center/data-chart-center/interest-rates/daily-treasury-rates.csv/2026/all?type=daily_treasury_yield_curve
Perplexity Finance: index, ETF, yield, and sector data: https://www.perplexity.ai/finance
Blog Disclosures
This content, which contains security-related opinions and/or information, is provided for informational purposes only and should not be relied upon in any manner as professional advice, or an endorsement of any practices, products or services. There can be no guarantees or assurances that the views expressed here will be applicable for any particular facts or circumstances, and should not be relied upon in any manner. You should consult your own financial advisors as to legal, business, tax, and other related matters concerning any investment.
The commentary in this “post” (including any related blogs, videos, and social media) reflects the personal opinions, viewpoints, and analyses of the Financial Synergies Wealth Advisors, Inc. employees providing such comments, and should not be regarded as the views of Financial Synergies Wealth Advisors, Inc. or its respective affiliates or as a description of advisory services provided by Financial Synergies Wealth Advisors, Inc. or performance returns of any Financial Synergies Wealth Advisors, Inc. client.
Any opinions expressed herein do not constitute or imply endorsement, sponsorship, or recommendation by Financial Synergies Wealth Advisors, Inc. or its employees. The views reflected in the commentary are subject to change at any time without notice.
Nothing on this website constitutes investment or financial planning advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. It also should not be construed as an offer soliciting the purchase or sale of any security mentioned. Nor should it be construed as an offer to provide investment advisory services by Financial Synergies Wealth Advisors, Inc.
Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Financial Synergies Wealth Advisors, Inc. manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
Any charts provided here or on any related Financial Synergies Wealth Advisors, Inc. personnel content outlets are for informational purposes only, and should also not be relied upon when making any investment decision. Any indices referenced for comparison are unmanaged and cannot be invested into directly. As always please remember investing involves risk and possible loss of principal capital; please seek advice from a licensed professional. Any projections, estimates, forecasts, targets, prospects and/or opinions expressed in these materials are subject to change without notice and may differ or be contrary to opinions expressed by others. Information in charts have been obtained from third-party sources and data, and may include those from portfolio securities of funds managed by Financial Synergies Wealth Advisors, Inc. While taken from sources believed to be reliable, Financial Synergies Wealth Advisors, Inc. has not independently verified such information and makes no representations about the enduring accuracy of the information or its appropriateness for a given situation. All content speaks only as of the date indicated.
Financial Synergies Wealth Advisors, Inc. is a registered investment adviser. Advisory services are only offered to clients or prospective clients where Financial Synergies Wealth Advisors, Inc. and its representatives are properly licensed or exempt from licensure. Investments in securities involve the risk of loss. Past performance is no guarantee of future results.
See Full Disclosures Page Here
Recent Posts
Weekly Market Recap – A Tough Week for Stocks as the AI Trade Cools
Chart of the Month | What History Says About Stocks When the Fed Starts Raising Rates
What Leadership Changes at Nvidia Mean for AI Trends
Subscribe to Our Blog
Chief Investment Officer | Managing Partner